
Uplift Ventures’ €100m Fund Is A Layered Jungheinrich Platform
Uplift Ventures’ €100m fund sits inside a Jungheinrich-backed platform with separate GP, management and partner vehicles, not one undifferentiated pool.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
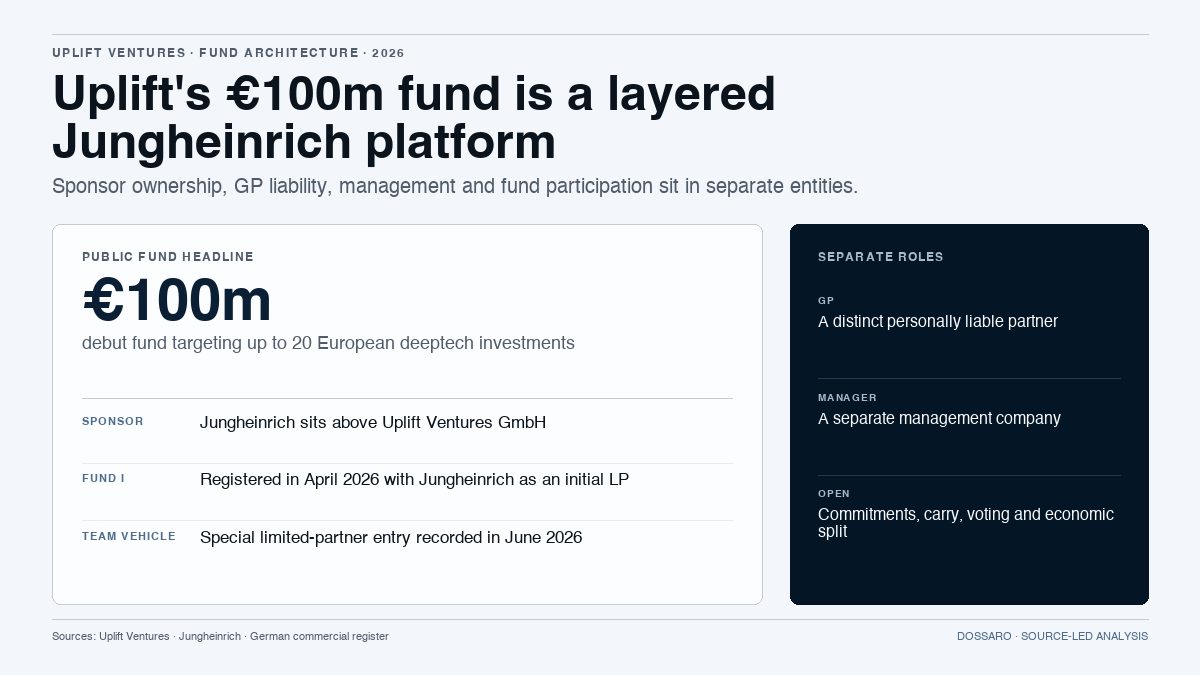
Uplift Ventures’ €100 million debut fund is presented publicly as a Jungheinrich-backed vehicle for European deeptech. The German register shows a more layered arrangement: Jungheinrich sits above a sponsor-owned platform, a separate company is the fund’s general partner, another is the management company, and the people on the investment team appear in a special limited-partner vehicle admitted later.
That is not a semantic distinction. It separates sponsor ownership, general-partner liability, management economics and fund participation across dated legal entities. The public launch tells investors what the platform intends to deploy. The register tells them which companies and partnerships carry each role. Neither source, on its own, proves the ultimate economic split.
The evidence supports a precise conclusion. Jungheinrich Aktiengesellschaft acquired the company that became Uplift Ventures GmbH in December 2024. Uplift Ventures GmbH then owned the GP and management companies after November 2025 reorganisations. Uplift Ventures Fund I GmbH & Co. KG was registered in April 2026 with Jungheinrich as an initial limited partner, and a separate limited-partner vehicle was admitted in June. The register does not disclose commitments, carried interest, voting arrangements or the percentage held by any partner.
The public launch describes a strategy, not a cap table
Jungheinrich’s official announcement dated 4 September 2026 says Uplift Ventures has launched a €100 million venture-capital fund. It names Physical AI, energy, enterprise AI and logistics as focus areas, with investments in Europe, the United States and Asia and up to 20 investments. The announcement identifies Christian Noske as general partner and names Kerk Ole Wichmann, Christina Hammes and Maike Steding on the team.
Tech.eu reported the launch on 2 September as a €100 million fund for European deeptech start-ups, with selective commitments to smaller deeptech funds. Sifted described it as backed solely by German material-handling company Jungheinrich. Those accounts are consistent with a corporate-sponsored platform. They do not identify the legal ownership of the GP, the fund’s limited-partner terms or the economics of the managers’ vehicle.
The €100 million figure is therefore a fund-size statement, not a disclosed capital table. It should not be divided among the entities below without the partnership agreement or subscription records. The register’s €100 liability figures for listed limited partners are nominal register amounts, not evidence that a partner committed €100 or that all partners have equal economics.
Five legal layers carry five different questions
The current German register state can be read as a sequence rather than a single ownership chart.
| Entity or event | Register evidence | What it establishes | What remains open |
|---|---|---|---|
| Uplift Ventures GmbH, Hamburg HRB 189208 | 5 December 2024 shareholder list records Jungheinrich Aktiengesellschaft as the 100% shareholder after a 3 December notarial deed | Jungheinrich owns the platform company | The list does not disclose the fund’s commitments or return waterfall |
| Uplift Ventures GP GmbH, HRB 194585 | 17 February 2026 shareholder list records Uplift Ventures GmbH as sole shareholder; the entity was formerly SCUR-Alpha 258 GmbH | The GP sits under the sponsor-owned platform | General-partner liability and carry terms are not public |
| Uplift Ventures Management GmbH, HRB 197256 | 18 February 2026 shareholder list records Uplift Ventures GmbH as sole shareholder; the entity was formerly SCUR-Alpha 815 GmbH | Management is legally separate from the GP | Employment, fee and incentive arrangements are not disclosed |
| Uplift Ventures Fund I GmbH & Co. KG, HRA 133447 | The April 2026 chronological extract shows Jungheinrich as an initial limited partner; a special limited partner was admitted in June | Fund participation was recorded in stages | The register does not show €100 million as a legal commitment or allocate units |
| Uplift Ventures Special Limited Partner GmbH & Co. KG, HRA 133446 | The April 2026 extract lists Christina Hammes, Maike Steding and Kerk Ole Wichmann as limited partners, each with a €100 liability sum | The managers have a separate partnership vehicle | It does not show their economic percentage, carry or voting rights |
The table distinguishes legal role from economic outcome. A general partner can carry unlimited liability without owning the fund. A management company can employ the team without being a fund partner. A limited-partner vehicle can hold an interest without the public register showing its size or priority. Those distinctions are routine in private funds, but they matter when a corporate backer is described as the sole source of a large pool of capital.
The dates show how the platform was assembled
The first visible step is the sponsor change at Uplift Ventures GmbH. The 30 October 2024 shareholder list for the then-named SCUR-Alpha 239 GmbH recorded SCUR24 Holding GmbH as holder of all 25,000 one-euro shares. A second list taken into the register on 5 December 2024 recorded a transfer of all shares to Jungheinrich Aktiengesellschaft under a notarial deed dated 3 December. The register therefore places the sponsor acquisition before the fund was registered.
The platform entities followed. Uplift Ventures GP GmbH’s 17 February 2026 shareholder list records Uplift Ventures GmbH as the sole owner of 25,000 one-euro shares. The entity had previously been SCUR-Alpha 258 GmbH and the transfer is tied to a 28 November 2025 deed. Uplift Ventures Management GmbH shows the same sole parent relationship in its 18 February 2026 list; it was previously SCUR-Alpha 815 GmbH and the same November deed is cited.
Fund I was registered on 1 April 2026. Its current extract names Uplift Ventures GP GmbH as the personally liable partner, with Jungheinrich Aktiengesellschaft and the special limited-partner vehicle as limited partners. The chronological extract records Jungheinrich at formation and the special limited partner’s admission on 12 June. The related HRA 133446 vehicle lists Hammes, Steding and Wichmann as its limited partners from 1 April.
The sequence matters because it does not look like a single company simply opening a bank account for a €100 million fund. It looks like a sponsor-owned operating platform was assembled first, then the GP, management and partnership layers were placed beneath it, with manager participation documented after the fund vehicle existed.
What “Jungheinrich-backed” tells investors, and what it does not
“Jungheinrich-backed” is a useful description of sponsorship. The register confirms a direct corporate ownership link at the platform level and a direct limited-partner position for Jungheinrich in Fund I. It does not prove that Jungheinrich is the only economic beneficiary, that it made the entire €100 million commitment, or that every investment decision is controlled at the parent level.
The register also does not prove that the managers own part of the fund in the ordinary equity sense. Their special limited-partner vehicle may carry economics, governance rights, or a contractual interest that is not expressed in the extract. The only public fact is that the vehicle exists, names three people as limited partners and was admitted in the same year as the fund’s launch. Treating that as a percentage would turn a role signal into an unsupported cap-table claim.
For founders seeking capital, the distinction changes where diligence should focus. The public launch gives a clear sector and stage thesis, including late Seed and Series A opportunities and selective fund commitments. The legal structure tells a founder to ask which entity signs the term sheet, which entity is the limited partner, who has appointment or removal rights at the GP, and whether the manager vehicle has consent or carry rights. Those questions cannot be answered by the €100 million headline alone.
The same distinction matters for counterparties. A supplier or service provider dealing with the management company is not automatically dealing with the fund. A claim against the GP is not necessarily a claim against Jungheinrich. The German register gives the entity boundaries; the partnership agreement, service contracts and fund disclosures would be needed to map recourse and cash flows. That is the same diligence problem explored in Runway Venture Capital’s Fund II structure, where legal roles also carry more information than a headline fund size.
The next document that would change the analysis
The strongest unresolved question is economic, not administrative: what do the Fund I partnership agreement and subscription documents say about commitments, voting, carry and the special limited partner’s rights? The current public register records the parties and admission dates but not those terms. It also does not state whether the €100 million is a committed amount, a target, or a capital base assembled through multiple closings.
Until those documents become public, the defensible reading is narrower. Uplift Ventures is a Jungheinrich-owned platform with a separate GP and management company. Jungheinrich is an initial Fund I limited partner. A manager-linked special limited-partner vehicle was admitted later. The public launch supplies the fund’s size and strategy, while the German register supplies the legal sequence. Together they show a layered platform, not one undifferentiated pot of money.
That is the commercial point investors can use today. Read the sponsor announcement for intent, then read the entity chain for who can sign, who can be liable and who is recorded as a partner. The missing partnership terms are not a footnote. They are the next document watchpoint for any claim about ownership, control or payout.
Continue reading
Related Research
RunwayVC's €40m Fund II Sits Behind A NOK30,000 Fund Vehicle
RunwayVC's €40m Fund II is registered as a NOK30,000 alternative-investment vehicle, while a separate five-person manager carries the governance layer.
Auxxo's €33.3m Fund Close Shows Why LP Count Is Not Capital Control
Auxxo's €33.3m Female Catalyst Fund II closed after staged LP entries, but Berlin filings show nominal Haftsumme is not a map of capital or control.
The Public Investors Behind White Star Capital Fund IV
White Star Capital's $250 million Fund IV spans France, Quebec and Guernsey, with Aéroports de Paris and La Caisse named as investors in public filings.
Fundcraft's €12m Growth Financing Sat Beside a €1.24m Internal Capital Conversion
Fundcraft announced €12m of group growth financing while its French AIFM converted €1.24m of shareholder debt into capital without a cash remittance.