
Fundcraft's €12m Growth Financing Sat Beside a €1.24m Internal Capital Conversion
Fundcraft announced €12m of group growth financing while its French AIFM converted €1.24m of shareholder debt into capital without a cash remittance.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
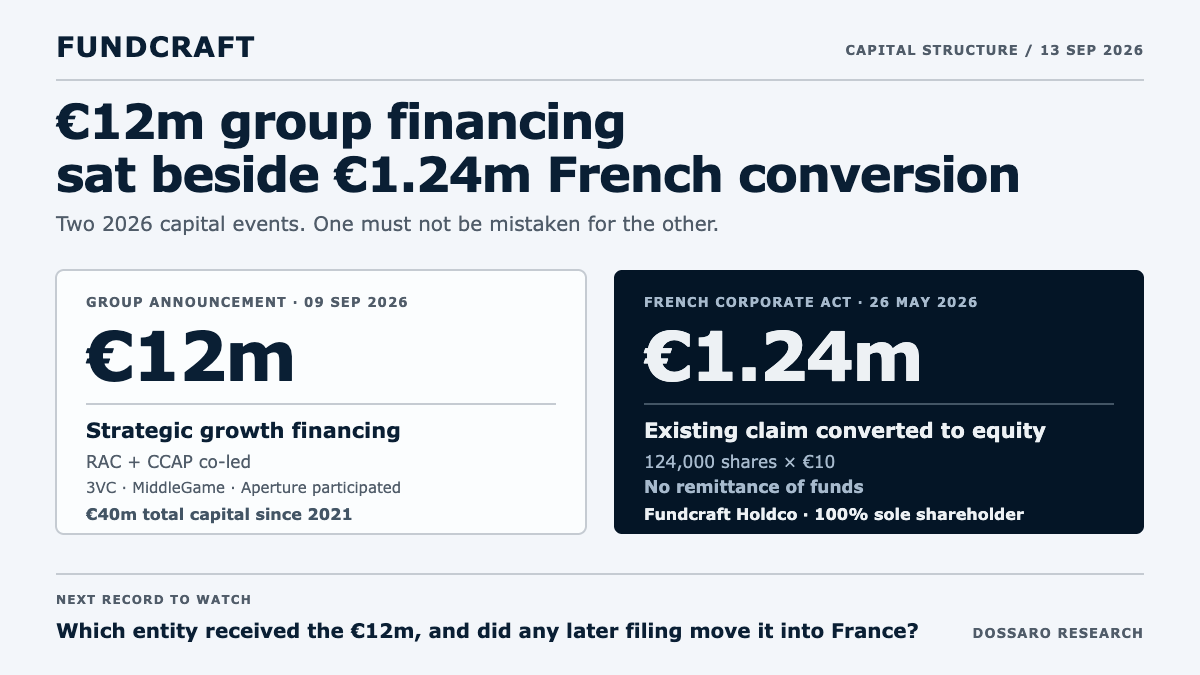
Fundcraft's €12 million growth financing and its French capitalisation were two different entries on the group's 2026 funding map. The company announced the financing on 9 September, naming Riverside Acceleration Capital and CCAP Investments as co-leads and 3VC, MiddleGame Ventures and Aperture Capital as participating existing investors. A French register act dated 26 May records a separate €1.24 million increase in the nominal capital of FUNDCRAFT FRANCE SAS.
The French act says all 124,000 new €10 shares were subscribed by Fundcraft Holdco S.à r.l., the existing sole shareholder. It also says the subscription involved no remittance of funds: the amount was settled by compensation with the shareholder's current-account claim against the French company. The result was a larger regulated vehicle with the same 100% shareholder, not a disclosed €1.24 million cash injection from the new financing syndicate.
That distinction is the useful finding for investors, fund managers and counterparties. The public announcement describes group-level growth capital. The French filing describes an internal balance-sheet conversion that supports a French regulated activity. The available records do not allocate any part of the €12 million to the French subsidiary.
The €12m announcement describes group expansion
Fundcraft's official announcement is explicit about the event and its scope. Dated 9 September 2026, it calls the transaction €12 million of strategic growth financing. Riverside Acceleration Capital, the growth-stage investment strategy of The Riverside Company, and CCAP Investments co-led it. 3VC, MiddleGame Ventures and Aperture Capital are listed as existing investors that participated.
The announcement says the financing takes Fundcraft's total capital secured since its founding in 2021 to €40 million. It says the money will support expansion across jurisdictions, more complex private-market operating models, institutional buyout capabilities and the company's artificial-intelligence strategy. Fundcraft also says its platform supports more than 20,000 limited partner (LP) subscriptions across nearly 300 funds, and that it signed as many new clients in the first half of 2026 as in all of 2025. Those operating figures are company statements, not figures from the French register.
The French version of the announcement repeats the amount, investor group and €40 million total. Independent coverage from FinTech Futures on 11 September also reports €12 million of strategic growth financing, the same investor group and the expansion of digital fund operations. The cross-check supports the public event and its date. It does not provide a valuation, instrument schedule or entity-by-entity allocation.
The company links the financing to its French expansion. It says a separate alternative investment fund manager (AIFM) licence was granted by the French Autorité des marchés financiers (AMF) in June 2026, followed by mandates for French fund launches with more than €1 billion in combined commitments and subscription targets. Those are the group's stated ambitions. They do not show that the French legal entity received the new outside capital.
The French act records an internal capital event
The exact French entity is FUNDCRAFT FRANCE SAS, SIREN 994786382, at 4 Quai des Célestins in Paris. Its 26 May sole-shareholder decision, filed in the French National Register of Enterprises on 15 June, identifies Fundcraft Holdco S.à r.l. as the sole shareholder. The act increases nominal capital from €10,000 to €1,250,000 by issuing 124,000 new shares at €10 each.
The arithmetic is straightforward: 124,000 shares multiplied by €10 equals €1,240,000, and €10,000 plus €1,240,000 equals the post-event nominal capital of €1,250,000. The act then records 125,000 fully paid shares of €10 each. A proposal for a capital increase reserved for employees was rejected.
The payment wording changes the economic reading. The decision says the subscription was not accompanied by a remittance of funds and that the full amount was settled by compensation with the current account held by the sole shareholder against the company. In practical terms, an existing shareholder claim was exchanged for permanent equity in the French subsidiary. That is a debt-to-equity conversion as a description of the accounting mechanism, not evidence of a new outside subscription.
The same decision amends the corporate purpose to cover, within the AMF-approved programme, portfolio management, alternative investment fund management, investment advice and work connected with acquisitions and disposals. It appoints Rodolphe Letovsky as director general alongside President Thomas Ibanez and director general Julien De Mayer. The regulated purpose and the capital conversion therefore sit in one corporate act, while the public financing announcement sits at group level.
| Date | Public or legal event | Amount or state | What it establishes | What it does not establish |
|---|---|---|---|---|
| 26 May 2026 | Fundcraft France sole-shareholder decision | €1.24m nominal increase | 124,000 new €10 shares were subscribed by Fundcraft Holdco and settled against its current-account claim | No cash remittance, outside subscriber or link to the €12m financing |
| 15 June 2026 | French register filing of the decision | €1.25m capital and 125,000 shares | The French vehicle's post-increase legal capital and regulated-purpose amendments | No valuation, shareholder-level price or investor allocation |
| June 2026 | AMF authorisation cited by Fundcraft | Separate French AIFM licence | The group says the French platform could support regulated fund launches | No proof that the €12m was paid into FUNDCRAFT FRANCE SAS |
| 9 September 2026 | Group strategic growth financing announced | €12m; €40m total since 2021 | RAC and CCAP co-led a group financing with existing investors participating | No public entity allocation, instrument mix or valuation |
The €1.24m changed the claim, not the shareholder
Fundcraft Holdco subscribed for every new share in the French act. Because the company had one shareholder before the issue and the act records the same holder after it, the filing leaves the French vehicle wholly controlled by Fundcraft Holdco. The event strengthens the subsidiary's nominal capital without introducing a new name to its shareholder line.
It also changes the position of the Holdco. Before the issue, the current-account claim sat as a claim against the French company. After compensation, the same €1.24 million is represented by equity in the subsidiary. A creditor claim and an equity position do not rank in the same way if the subsidiary later has to absorb losses or distribute value. The filing proves the conversion, but it does not disclose the original balance's age, interest, intercompany terms or tax treatment.
The €1.25 million number should therefore not be treated as a valuation. Nominal capital is the legal amount attached to the shares, not the price an investor paid for the business. The act states that the new shares were issued at par and that the Holdco's claim was used to settle the subscription. It does not state a share premium, a negotiated company value or a return expectation.
This is the same reading discipline used in E2D's Luxembourg AIFM structure, where a manager vehicle and a fund vehicle answer different ownership questions. It also helps when reading Uplift Ventures' fund architecture: a capital figure only becomes economically useful after the reader identifies the entity, the instrument and the party that subscribed.
Why the two ledgers should stay separate
The group announcement and the French act answer different questions. The announcement identifies the capital providers and the commercial programme. The act identifies the legal entity, the sole shareholder, the nominal amount, the share count and the settlement mechanism. Combining the two would turn a group financing into a claim about a subsidiary that the sources do not make.
That separation matters because the French vehicle is the part of the structure carrying the AMF-regulated portfolio-management purpose. Regulatory capital can be built by an internal conversion even when a parent or wider group raises outside growth capital for product development, hiring, market entry and technology. An internal conversion can also remove a shareholder claim from the subsidiary's creditor stack while leaving voting control unchanged. None of those structural consequences requires an allegation that the public announcement was misleading.
The public record still leaves one commercially important bridge open: whether any later group financing proceeds were used to replenish or replace the Holdco current-account claim. The French decision does not identify the source of the claim beyond the sole shareholder, and the financing announcement does not disclose the recipient entities, valuation or instrument mix. No available source shows that RAC or CCAP funded the €1.24 million conversion.
For investors and counterparties, the diligence request is specific. A group financing document, intercompany ledger or later filing that allocates the €12 million would show whether the growth capital stayed at a parent level, moved into the French vehicle, or was spread across several operating entities. A subsequent French shareholder or capital filing would show whether the Holdco remains the sole shareholder. Until those records appear, the safest map has two ledgers: outside growth financing for the group and internal capitalisation for the regulated French subsidiary.
The next record should connect group capital to entity economics
Fundcraft has publicly disclosed a €12 million strategic growth financing and a €40 million cumulative capital figure. Its French legal record separately shows a €1.24 million nominal capital increase, 124,000 new shares and a payment by compensation with an existing shareholder current-account claim. The act also shows an AMF-oriented corporate purpose and a French vehicle that remains wholly controlled by Fundcraft Holdco.
The strongest supported conclusion is therefore narrow: the French capital event is not evidence that the €12 million financing was paid into FUNDCRAFT FRANCE SAS. It is evidence that Fundcraft used an internal claim conversion to capitalise the entity that carries its French regulated activity. The economic relationship between that conversion and the group financing remains unallocated in the public record.
The next document to watch is the one that connects the ledgers: a subscription or intercompany record naming the financing recipient and terms, a later French filing showing a new holder or capital step, or group accounts that describe the movement of the Holdco current-account balance. Without that bridge, the public financing headline and the French nominal-capital number should remain separate facts.
Continue reading
Related Research
E2D's €500m Defence-Fund Target Has a Luxembourg Vehicle, Not a Public LP Ledger
E2D’s €500m defence-fund target now has a Luxembourg vehicle, an IQ EQ AIFM and a July first close, but LP commitments and allocation control remain undisclosed.
Uplift Ventures’ €100m Fund Is A Layered Jungheinrich Platform
Uplift Ventures’ €100m fund sits inside a Jungheinrich-backed platform with separate GP, management and partner vehicles, not one undifferentiated pool.
Mustard Seed's €150m First Close Is Already a Deployment Vehicle
Mustard Seed + Partners says nearly €150m is closed and €55m is deployed, but public records still leave LP commitments and fund control unallocated.
Kaiko's $110m Round Arrived With a €35.5m Share-Funded Roll-Up
Kaiko's $110m strategic round arrived beside €35.5m of share-funded acquisitions, issuing 553,134 shares while investor allocations remain undisclosed.