
Mustard Seed's €150m First Close Is Already a Deployment Vehicle
Mustard Seed + Partners says nearly €150m is closed and €55m is deployed, but public records still leave LP commitments and fund control unallocated.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
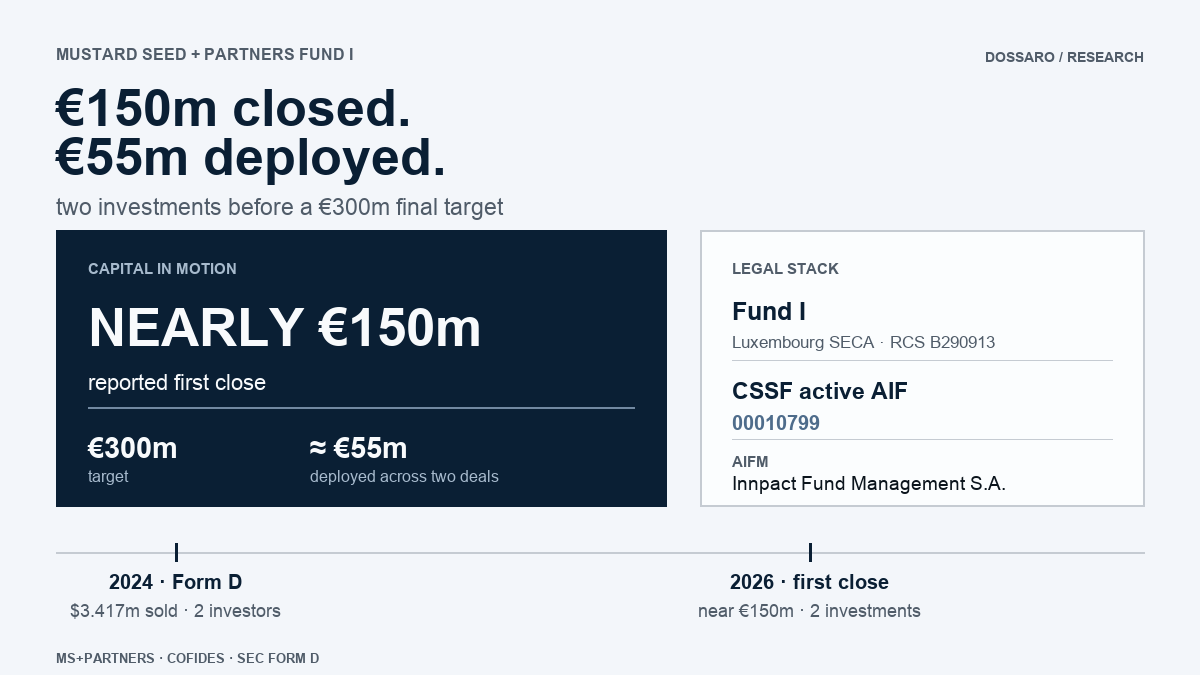
Mustard Seed + Partners says it has closed close to €150 million for a €300 million fund and already completed two investments. In a separate 30 June release, Spanish state-owned investor COFIDES said the same vehicle had deployed approximately €55 million across two deals. Together, the disclosures establish more than a fundraising target: Fund I is operating as a deployment vehicle while its final close remains ahead.
That distinction matters for anyone underwriting the fund. The public record identifies a Luxembourg vehicle, an alternative investment fund manager and a public-capital channel. It still does not allocate the reported close between limited partners or show which rights travel with each commitment. The useful reading is therefore specific: nearly €150 million is reported as closed, roughly €55 million is reported as deployed, and the capital account behind those numbers remains private.
The first close already has two portfolio assets
The 1 September announcement from MS+PARTNERS says the firm raised close to €150 million toward a €300 million target. It names the European Investment Fund as an anchor and lists COFIDES, BlackRock Private Equity Partners and C. Hoare & Co among the supporting institutions, alongside founders, family offices and senior private-equity professionals. The announcement says the final close is expected by the end of 2026.
The same release says two investments were already complete. The first is iLERNA, a Spanish online vocational-education platform acquired alongside Jacobs Capital. The second is Maritime Robotics, a Norwegian developer of autonomous maritime systems. Those are not pipeline logos. They are the first visible uses of the vehicle’s capital, even though the announcement does not publish ticket sizes, ownership percentages or governance terms.
COFIDES provides an independent timing check. Its official English release on 30 June records a €30 million investment through the Social Impact Fund and says approximately €55 million had been deployed across the two investments at that point. If the rounded deployment and first-close figures are compared directly, €55 million is about 37 percent of €150 million. The dates and qualifiers mean that is an orientation, not a paid-in capital statement. It does show that the vehicle was putting money to work before the first-close announcement.
| Publicly stated measure | Amount or status | What it establishes |
|---|---|---|
| Reported first close | Close to €150m | Capital the manager says is closed, without an LP-by-LP split |
| Fund target | €300m | The remaining fundraising ambition before final close |
| COFIDES investment | €30m | A public-capital channel, not a disclosed ownership percentage |
| Reported deployment | Approx. €55m across two investments | An operating portfolio, without ticket or control allocation |
| 2024 Form D notice | $3.417m sold against a $300m offering | An earlier offering notice, not a 2026 close composition |
The legal vehicle is visible, but the capital account is not
The fund has a more concrete identity than the launch headline suggests. Luxembourg records identify Mustard Seed + Partners Fund I, a société en commandite par actions (SECA) at 5 Allée Scheffer, L-2520 Luxembourg, with RCS number B290913. The Luxembourg financial regulator’s fund register identifies the vehicle as active alternative investment fund 00010799 and maps it to Innpact Fund Management S.A. as alternative investment fund manager.
Innpact’s project reference supplies the public context for that stack. It says Innpact was selected as the manager in 2024, Mustard Seed Impact Limited is the investment adviser, the vehicle began in November 2024 and it is a Luxembourg reserved alternative investment fund. Innpact also describes an Article 9 classification under the Sustainable Finance Disclosure Regulation and a €10 million to €40 million sweet spot for growth-equity investments.
That division of roles is important. The fund vehicle holds the investment programme, Innpact is the regulated manager named in the public relationship, and Mustard Seed Impact Limited is identified as adviser. None of those facts, on their own, gives an outside reader the LP voting map or tells a seller which investor can approve a particular acquisition. They make the fund traceable; they do not make its internal capital account public.
The distinction between a named vehicle and the economics behind it also appears in Runway Venture Capital's Fund II structure, where the legal wrapper is easier to identify than the investor-level rights.
A 2024 Form D records an earlier, smaller offering
The earliest hard financing figure comes from a U.S. Securities and Exchange Commission Form D filed in December 2024. The issuer is named Mustard Seed Partners Fund I, without the plus sign used in the 2026 announcement. It lists Luxembourg as the jurisdiction, the same 5 Allée Scheffer address and Mustard Seed + Partners GP, S.à r.l. as general partner.
The notice records a first sale on 12 December 2024, a total offering amount of $300 million, $3,417,115 sold and $296,582,885 remaining. It reports two investors and a minimum accepted investment of $132,065. The filing marks both equity and pooled-investment-fund interests as the securities offered. The SEC states that it has not reviewed the notice for accuracy or completeness.
The arithmetic is revealing but limited. The amount sold was roughly 1.1 percent of the stated offering amount at the time. That is evidence of an earlier offering stage, not proof that only two investors funded the 2026 fund or that the 2024 dollars sit outside the reported first close. The near-identical name, matching address and named general partner connect the records as a plausible legal sequence, but they do not substitute for a limited partnership agreement or a capital-call ledger.
This is why the Form D does not contradict the later announcement. A fund can solicit or admit capital over time, reserve money for follow-ons and add institutional commitments before a public first-close milestone. The filing shows that fundraising activity was underway in 2024. It does not show how the reported €150 million was assembled two years later.
COFIDES adds public capital, not a public control right
COFIDES describes its €30 million commitment as an investment from Spain’s Social Impact Fund, financed through the country’s Recovery, Transformation and Resilience Plan and the European Union’s NextGenerationEU instrument. COFIDES is state-owned and says the vehicle is intended to support Spanish companies in later growth stages. The release places the fund within a public-private impact strategy rather than presenting the €30 million as a direct investment in either portfolio company.
That distinction has a practical consequence. A public anchor can broaden the fund’s mandate and help it finance larger growth situations, but the €30 million number cannot be converted into a 20 percent stake in Fund I. The public release gives a commitment amount and policy channel, not a share class, fee arrangement, priority or vote. The same boundary applies to the other institutions named by MS+PARTNERS: their presence signals backing, but their individual economic rights are not published in the sources above.
What the structure changes for underwriting
MS+PARTNERS describes a strategy aimed at founder-led lower-mid-market businesses with enterprise values between €50 million and €500 million. Its two disclosed assets fit that operating thesis: vocational education in Spain and autonomous maritime technology in Norway. The combination of a near-€150 million close and €55 million already deployed suggests a manager moving quickly from fundraising to portfolio construction.
For a founder or seller, that changes the diligence question. The relevant issue is no longer whether the manager has a credible target. It is how much capital remains available for the next acquisition, how much is reserved for the existing two assets and which investment committee or investor-consent rules govern deployment. The public sources cannot answer those questions, and the two completed deals do not reveal whether Fund I holds a controlling or minority position.
For an LP, the distinction is between reported commitments and usable capital. “Close to €150 million” is a manager disclosure, while “approximately €55 million deployed” is a portfolio-use disclosure from COFIDES. Neither figure states paid-in capital, uncalled commitments or the timing of capital calls. The numbers show an active vehicle, not a complete liquidity schedule.
The missing commitment ledger
The next document that would change this reading is not another launch quote. It is the fund’s commitment schedule, audited accounts or partnership agreement, together with a portfolio disclosure that sets out ownership and governance. Those records could show how the EIF, COFIDES, BlackRock Private Equity Partners, C. Hoare & Co and the private investors rank against one another and how much of the first close is available for new deals.
Until then, the defensible conclusion is narrower and more useful than the headline alone. Mustard Seed + Partners has a traceable Luxembourg Fund I, a named manager and adviser, a reported first close near €150 million and two investments backed by an independent €55 million deployment figure. The public record still stops short of the LP economics and control rights that determine who can direct the next euro.
Continue reading
Related Research
RunwayVC's €40m Fund II Sits Behind A NOK30,000 Fund Vehicle
RunwayVC's €40m Fund II is registered as a NOK30,000 alternative-investment vehicle, while a separate five-person manager carries the governance layer.
WAD Capital's €130m Fund Separates Search From Acquisition
WAD Capital's €130m debut fund has two dated Belgian vehicles: Seed Fund I for search and Invest Fund I for acquisitions, with EIF anchoring its first close.
Auxxo's €33.3m Fund Close Shows Why LP Count Is Not Capital Control
Auxxo's €33.3m Female Catalyst Fund II closed after staged LP entries, but Berlin filings show nominal Haftsumme is not a map of capital or control.
Fundcraft's €12m Growth Financing Sat Beside a €1.24m Internal Capital Conversion
Fundcraft announced €12m of group growth financing while its French AIFM converted €1.24m of shareholder debt into capital without a cash remittance.