
Kaiko's $110m Round Arrived With a €35.5m Share-Funded Roll-Up
Kaiko's $110m strategic round arrived beside €35.5m of share-funded acquisitions, issuing 553,134 shares while investor allocations remain undisclosed.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
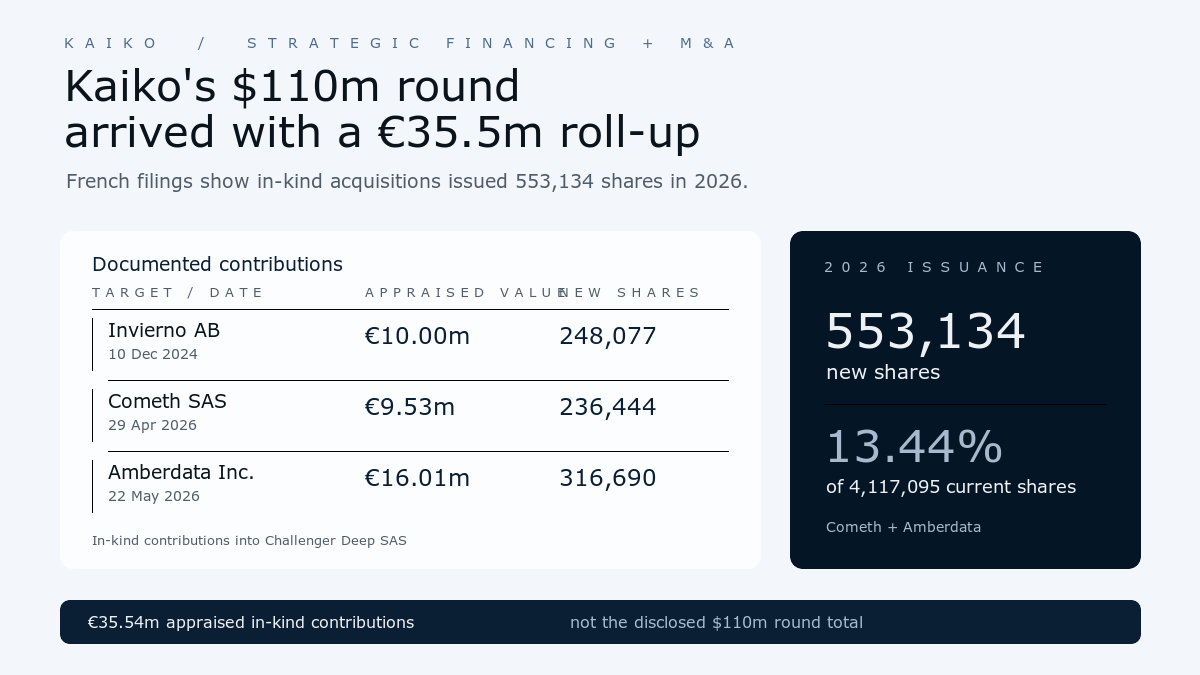
Kaiko's 14 September 2026 announcement says S&P Global led a strategic investment that extended its Series B to $110 million. The filing trail shows a second, less visible transaction: Challenger Deep SAS, the French company behind Kaiko, acquired Invierno AB, Cometh SAS and Amberdata Inc. through contributions of shares rather than a disclosed cash purchase.
The three contribution reports appraise those assets at a combined €35.54 million. Challenger Deep issued 248,077 shares for Invierno in December 2024, then 236,444 CMT preferred shares for Cometh and 316,690 ordinary shares for Amberdata in 2026. The two 2026 contributions alone added 553,134 shares, equal to 13.44% of the 4,117,095 shares in the latest statutes.
That is not a reconciliation of the $110 million round. The appraised values are contribution values, not a company valuation or the amount of cash raised from S&P Global and its co-investors. They do change the economic reading of the announcement: Kaiko is using its equity structure to absorb acquired data and infrastructure businesses, while the strategic investors' allocation and the identities of the 2026 contributors remain undisclosed.
| Date | Filed or public event | What it establishes |
|---|---|---|
| 10 Dec 2024 | Invierno contribution report filed | €10.00m appraised contribution; 248,077 new €1 shares and €9.75m premium |
| 29 Apr 2026 | Cometh contribution report filed | €9.531m appraised contribution; 236,444 CMT preferred shares |
| 22 May 2026 | Amberdata contribution report filed | €16.006m appraised contribution; 316,690 new ordinary shares |
| 8 Sep 2026 | Current statutes filed (dated 1 Jun) | 4,117,095 issued shares, including the 236,444 CMT preferred shares |
| 14 Sep 2026 | S&P Global investment announced | Series B extended to $110m; investor percentages and terms not published |
The $110m announcement names institutions, not allocations
Kaiko's announcement says S&P Global led the Series B extension and that BNP Paribas, Bpifrance, Broadridge, Canton Foundation, Coinbase Ventures, DRW Venture Capital, Nasdaq Ventures, Royal Bank of Canada, Stellar and Susquehanna Private Equity Investments also joined. Existing shareholders Anthemis, Point Nine and Revaia participated as well.
The S&P Global release places the investment in a wider partnership. It points to a co-branded digital-asset index suite and the tokenisation of the iBoxx U.S. Treasuries Index. S&P says Kaiko supports more than 250 financial firms, institutions and regulators. Reuters' independent report describes the raise as a sign of mainstream financial institutions' interest in digital-asset markets and says Kaiko's products cover more than 150 exchanges and crypto protocols. CoinDesk likewise reports that the new money will expand infrastructure for markets operating around the clock.
None of those public accounts states how much of the $110 million was new cash, how much was secondary, or how the investors split the share classes. CoinDesk notes that Kaiko's 2022 Series B raised $53 million and that the valuation remains undisclosed. The extension headline therefore tells customers and counterparties that institutional backing has deepened, but it does not provide a post-money cap table.
The legal identity is also specific. Pappers' profile identifies CHALLENGER DEEP, trading as Kaiko, as an active French SAS with SIREN 807 388 376 and stated capital of €4,117,095. The contribution reports name the same company as the beneficiary. This is the entity whose shares absorb the acquisition consideration.
Invierno established the share-funded acquisition pattern
The December 2024 Invierno report covers the contribution of all 7,890,479 issued shares of Swedish company Invierno AB. The contribution value was set at €10 million in the share contribution agreement. Instead of paying cash, Challenger Deep issued 248,077 new shares with a nominal value of €1 each and recorded €9,751,906.87 as contribution premium.
The report names three contributor groups and assigns their portions of the appraised value: Wint Startup 1559 AB contributed 6,680,003 Invierno shares for €8,465,903.02 of value; Octopus Titan VCT PLC contributed 1,028,905 for €1,303,982.94; and Octopus Investments Nominees Limited contributed 181,571 for €230,114.04. Those amounts add to €10 million and explain why the transaction created a new holder block in Challenger Deep without a disclosed cash purchase price.
An apport report is an independent valuation check for the contribution. It does not establish the price at which a future investor bought Challenger Deep shares, and it does not say that the €10 million was cash available for Kaiko's operating budget. It does establish that the Invierno business and its contributors entered the French company's equity structure.
Cometh and Amberdata widened the 2026 denominator
The 2026 reports use the same legal mechanism but different share classes and targets. The Cometh report values 1,816,940 Cometh SAS shares at €9,531,059.21. In return, Challenger Deep issued 236,444 statutory preferred shares labelled ADP CMT and recorded €9,294,613.64 of contribution premium. The report does not disclose the names of the contributors in its public text.
The Amberdata report values 10 million shares of Delaware company Amberdata Inc. at €16,005,512.60. The consideration was 316,690 new ordinary shares in Challenger Deep. Its cover and purpose section describe an acquisition of 100% of Amberdata's capital and voting rights through the share contribution agreement signed on 12 May 2026.
The latest Challenger Deep statutes show the resulting €4,117,095 capital divided into 1,034,743 ordinary shares, 787,129 seed-designated shares, 927,821 A-designated shares, 1,130,958 B-designated shares and 236,444 CMT preferred shares. The labels describe the classes for statutory purposes. They do not by themselves disclose the S&P Global issue price, voting agreement or liquidation preference.
| Acquired business | Contribution value | Shares issued by Challenger Deep | Share-class or cash detail |
|---|---|---|---|
| Invierno AB | €10,000,000.00 | 248,077 | €1 ordinary shares plus €9,751,906.87 contribution premium |
| Cometh SAS | €9,531,059.21 | 236,444 | ADP CMT preferred shares plus €9,294,613.64 premium |
| Amberdata Inc. | €16,005,512.60 | 316,690 | New ordinary shares; contributor identities not shown in the report |
| Total | €35,536,571.81 | 801,211 | 2024 and 2026 in-kind contributions combined |
The total share count includes the 248,077 Invierno shares issued in 2024. The 2026 total is 553,134 shares, made up of the Cometh and Amberdata blocks.
What 13.44% of current capital means
The 553,134 shares issued for Cometh and Amberdata represent 13.44% of the 4,117,095 shares in the current statutes. Cometh represents 5.74% and Amberdata 7.69% on the same denominator. The percentages are calculated from issued shares, not from a fully diluted cap table and not from voting or payout rights that may differ by class.
That denominator matters because the 2026 issuances do not simply add assets to an unchanged ownership map. Existing Challenger Deep holders own a smaller percentage after the contributions, while the Cometh contributors hold a preferred class and the Amberdata contributors hold ordinary shares. The 2024 Invierno issue had already created a separate contributor block. The company therefore carries acquired businesses and their former owners inside one enlarged equity structure.
The 13.44% figure should not be read as S&P Global's stake. The filing documents do not identify which of the 2026 shares belong to the strategic investors named in the September release, and the public announcement does not state an investor percentage. It is equally unsupported to say that the €35.54 million of contribution values is part of the $110 million in new cash. The documents show two overlapping financing and acquisition processes, not a single ledger that reconciles them.
A roll-up financed with shares changes who bears the risk
The structure gives Kaiko a way to buy operating assets without publishing a cash cheque for each acquisition. The acquired companies and their contributors receive exposure to Challenger Deep's future value. Existing holders absorb dilution and integration risk, while the company gains products, customers and data infrastructure that management says support regulated on-chain finance.
The risk is not only execution. The contribution values are appraisals tied to the relevant agreements. They are not a market price for Kaiko, and they do not prove that any acquired asset will generate that value. Amberdata and Cometh contributors may benefit if the enlarged platform grows, but the public records do not show their negotiated rights. The ADP CMT label signals a distinct class for Cometh, yet the contribution report alone does not provide a complete preference waterfall.
The investor coalition adds another layer. S&P Global and the banks, exchanges and funds listed by Kaiko may be strategic validators as well as capital providers. Their commercial access could help Kaiko sell indices, reference rates and risk tools into tokenised markets. Their exact economic exposure is still a filing question. Until a new capital decision, shareholder record or transaction disclosure maps those positions, the public investor list cannot be matched to the share-funded roll-up.
This is the same distinction visible in other private-market financings. INLEAP's cumulative €20 million headline sits above an 80/20 shareholder snapshot, while Open Cosmos' €300 million round leaves the founder with most ordinary shares but not first claim on every payout. Kaiko's evidence adds a third pattern: acquisition consideration itself can arrive as new shares while the financing headline is described separately.
The evidence boundary is the point
The high-confidence findings are the 14 September Series B extension to $110 million, S&P Global's lead role, the named participating institutions, the exact French entity, the three appraised in-kind contributions and the 553,134 shares issued for Cometh and Amberdata. The arithmetic is transparent: €10 million plus €9,531,059.21 plus €16,005,512.60 equals €35,536,571.81, and 553,134 divided by 4,117,095 equals 13.44%.
The evidence does not establish the round's valuation, S&P Global's percentage, the identity of the Cometh or Amberdata contributors, a cash-versus-secondary split, liquidation preferences, voting agreements or investor returns. It does not show that the three contribution values are proceeds from the $110 million extension, and it does not prove that any holder made a gain or loss.
The next decision-changing records would be a capital decision or updated statutes that identify the September issue, a shareholder or beneficial-owner disclosure that maps the new investors, and any transaction document that states consideration or preference terms. Until then, the defensible conclusion is narrow: Kaiko's strategic round is accompanied by a documented share-funded roll-up worth at least €35.5 million on apport valuations, and that roll-up changes the ownership denominator even though the new-money allocation remains private.
Continue reading
Related Research
INLEAP’s €20m Funding Headline Was Cumulative; Founders Held 80% in the 2025 List
INLEAP says it has raised about €20m since founding, while its latest filed shareholder list shows founder holding companies with 80% and outside holders with 20%.
Open Cosmos' Founder Held About 41% Before Its €300m Round
Open Cosmos' €300m round sits above a register where founder Rafael Jorda held about 41% of stated capital and preferred shares ranked ahead of ordinary.
Volta's $300m Raise Had A 30.5x Nominal Share-Price Ladder
Volta's $300m raise hid a 30.5x nominal price ladder from $58 Seed shares to $1,769.91 Series A stock, plus preferred rights and $2m of debt set-off.
Fundcraft's €12m Growth Financing Sat Beside a €1.24m Internal Capital Conversion
Fundcraft announced €12m of group growth financing while its French AIFM converted €1.24m of shareholder debt into capital without a cash remittance.