
Sprints’ €725m Fund V Sits Above a £654,887 Manager Balance Sheet
Sprints says Fund V closed at a €725m hard cap, while UK filings show £2.07m cash, £654,887 net assets and two new HSBC security filings remain outstanding.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
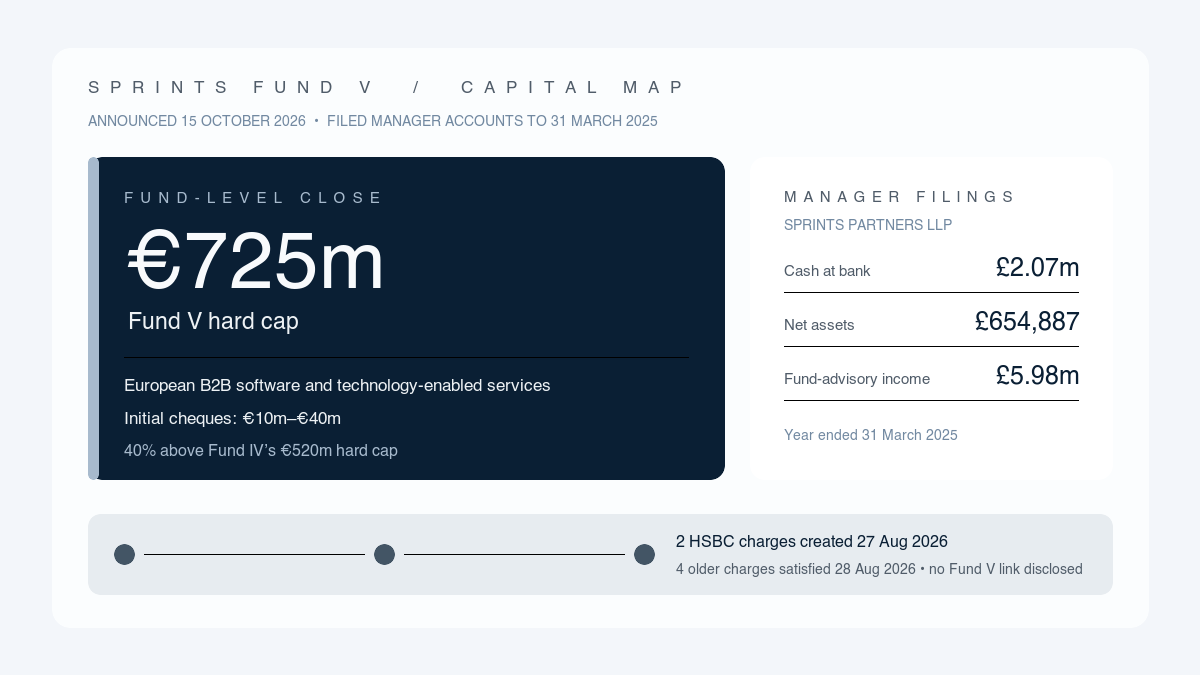
Sprints says its fifth fund closed at a €725 million hard cap. The latest filed accounts of SPRINTS PARTNERS LLP, the UK manager identified by Companies House as OC450548, show £2.07 million of cash and £654,887 of net assets. Those are not contradictory numbers. They belong to different legal and economic boxes.
The 15 October announcement describes Fund V as an oversubscribed European B2B software and technology-enabled-services fund, with a 40% increase on the €520 million hard cap reported for Fund IV. The manager’s accounts for the period ended 31 March 2025 instead describe a partnership that earned £5.98 million of fund-advisory income, held £2.07 million in cash and classified £654,887 as loans and other debts due to members. The accounts do not present a ledger for Fund V or for limited-partner commitments.
That split is the useful finding. A fund headline is a statement about capital formation at a vehicle level. A manager balance sheet is a statement about the assets, obligations and service economics of one operating entity. Reading the first as the second would overstate the manager’s own liquidity; reading the second as the whole platform would understate the capital available to the fund.
The €725m headline belongs to the fund vehicle
Sprints’ Fund V announcement, published on 15 October 2026, says the fund reached a €725 million hard cap and was oversubscribed. It describes a strategy focused on European B2B software and technology-enabled services, with initial cheques of €10 million to €40 million. The release says the hard cap is 40% above Fund IV’s €520 million and presents the close as a disciplined expansion of the platform.
Sprints’ own public site carries the same commercial framing and identifies Sprints Partners LLP at 28 Savile Row. The announcement does not name a UK Companies House number for a Fund V limited-partner vehicle, publish a commitment schedule, or state how much capital has been called. It also does not say that €725 million is cash owned by Sprints Partners LLP.
That is normal for a fund close. Commitments can sit in a limited partnership or another fund structure while a manager or adviser earns fees for operating the platform. The distinction is also visible in other recent fund reporting, including Nauta’s first-close and UK-manager split and Graduate Ventures’ vehicle architecture. The relevant question is not whether the headline and the statutory accounts match. It is which entity each number describes.
The filed accounts show a fee-generating operating partnership
The latest accounts for SPRINTS PARTNERS LLP cover the period from incorporation on 9 January 2024 to 31 March 2025. The filing is a small LLP accounts package, so it omits the income statement from the public copy. The notes still disclose the operating picture.
Fund-advisory income from related parties was £5,975,688. The balance sheet reports £2,070,543 of cash at bank and in hand, £875,238 of debtors and £2,332 of fixed-asset investments. Total assets were £2,945,781. The amount due from group undertakings was £762,069, described as interest-free, unsecured and repayable on demand.
At the other end of the balance sheet, net assets attributable to members were £654,887. The same amount is shown as loans and other debts due to members, with £531 of members’ capital and £654,356 of other amounts. The notes say those member loans rank equally with unsecured creditors in a winding up. That is a description of the LLP’s accounting and partnership economics, not a statement about the ownership of Fund V’s portfolio or the commitments of its investors.
| Filed manager measure | Amount | What it establishes |
|---|---|---|
| Fund-advisory income, year ended 31 March 2025 | £5,975,688 | Related-party service activity recorded by the LLP |
| Cash at bank and in hand | £2,070,543 | Liquidity reported by Sprints Partners LLP at its year-end |
| Net assets attributable to members | £654,887 | Members’ interests in the UK LLP accounts, not Fund V commitments |
| Amounts due from group undertakings | £762,069 | An intercompany receivable, not a limited-partner cash account |
The accounts therefore support a narrow but important conclusion: the UK entity is a service and advisory partnership with its own cash, receivables and member balances. They do not provide a balance-sheet shortcut for a €725 million fund close.
Two HSBC charges changed the public security picture
The Companies House charges page shows six registered charges for SPRINTS PARTNERS LLP. Four older charges are marked satisfied on 28 August 2026. Two new charges were created on 27 August 2026, delivered for filing on 2 September and remain outstanding on the page.
The underlying filings make the pair more specific without making its commercial purpose speculative. One registration, charge code OC45 0548 0006, is in favour of HSBC Innovation Bank as secured party and says it contains fixed charges and a negative pledge. Its security-interest agreement covers contract rights, including the investment-advisory agreement between Sprints Partners LLP and Sprints II GP Limited relating to Sprints II LP.
The second, charge code OC45 0548 0005, is in favour of HSBC Innovation Bank as lender. Its instrument is titled “Sprints Manco Charge Over Accounts” and creates first fixed charges over money standing to the credit of specified accounts and related rights. Both instruments refer to facility documents and secured obligations. Neither filing discloses a facility amount, a borrower schedule for Fund V, or a statement that the security was raised to finance the new fund.
The timing is worth recording, but it is not a distress signal. Four prior charges were satisfied one day after the new charges were created, while the new pair stayed outstanding. That sequence could reflect a refinancing, a release and re-documentation, or another facility change. The public documents do not establish which explanation is correct. What they do establish is a new security package around contract rights and accounts at the manager, alongside a much larger fund close announced in the same period.
What the public close does not establish
The €725 million figure does not identify Fund V’s legal issuer, the amount already called from limited partners, the date of first drawdown or the proportion reserved for follow-on investments. It also does not disclose management fees, carried interest, the fund’s bank balances or the entities that will hold portfolio positions.
The UK accounts do not fill those gaps. Their £5.98 million of fund-advisory income is a related-party revenue line for the year ended 31 March 2025, more than a year before the Fund V announcement. The £2.07 million cash balance is a year-end balance at Sprints Partners LLP. The £654,887 member-interest figure is an accounting measure of that LLP. None is a proxy for committed or callable capital in the new fund.
The same discipline applies to the charges. A fixed charge over accounts can protect a lender’s rights over cash in specified accounts. A charge over advisory-contract rights can give a lender recourse to contractual income or other benefits. Neither filing says who ultimately benefits from Fund V, which investor vehicle is the counterparty, or how the security interacts with the fund’s limited-partnership documents.
The underwriting question is deployment, not headline size
For founders, the €10 million to €40 million initial-cheque range is more actionable than the hard-cap number alone. It gives a public range for the intended entry points, while the announced €725 million sets a scale against which deployment pace and reserve policy will eventually be judged. A larger fund can write larger or more numerous cheques, but the release does not promise a particular annual deployment rate or portfolio count.
For a lender or supplier dealing with Sprints Partners LLP, the relevant evidence is the LLP’s own cash, receivables, member balances and security arrangements. For a founder negotiating with a Fund V investment vehicle, the relevant counterparty is the entity that subscribes, holds shares and exercises governance rights. For a limited partner, the decisive documents are the commitment, drawdown, distribution and governance terms of the fund vehicle.
This is why the manager-versus-fund split matters commercially. Treating €725 million as the manager’s cash could produce a false view of liquidity and creditor protection. Treating £2.07 million as the platform’s investable capital could produce the opposite error. Both numbers can be true at the same time because they answer different questions.
The next filing that would connect the boxes
The decision-changing watchpoint is a filing or closing document that names Fund V’s legal vehicle and shows how commitments are called and held. A fund-level account, partnership filing, offering document or later announcement with the issuer’s register number could connect the €725 million to a specific entity. A subsequent Sprints Partners LLP filing could also show whether the new HSBC security package remains in place and how the manager’s receivables and cash changed after the close.
Until that evidence appears, the strongest safe conclusion is precise: Sprints announced a €725 million Fund V hard cap, while its latest public UK accounts show a £5.98 million advisory business, £2.07 million cash and £654,887 net assets at the manager. The charges page adds two outstanding HSBC filings created on 27 August 2026, but it does not turn the fund headline into manager cash or prove why the security was put in place.
Continue reading
Related Research
Nauta's €60m Fund VI Close Sits Above a £2.25m UK Manager
Nauta’s €60m Fund VI first close sits at fund level, while its UK manager reports £2.25m of service revenue, £161,189 cash and a £767,578 parent debtor.
Graduate Ventures' €125m Fund II Sits in a Dutch Cooperative
Graduate Ventures' €125m Fund II maps to a Dutch cooperative beside separate manager and seed-capital companies, clarifying structure without LP economics.
Gaius' €50m Fund Changed Its Registered Limited-Partner Layer
Gaius' €50m succession fund moved its registered limited-partner layer into carry and team vehicles, while the €200 liability is not fund capital.
Sosteneo's €450m Fund II Headline Blends Commitments and Co-Investment
Sosteneo says Fund II has more than €450m in total commitments, but its first close includes co-investment capital; the Luxembourg RAIF and AIFM are clear.