
Sofinnova's €82m MD Start IV Fund Uses A €20,000 French UP Wrapper
Sofinnova's €82m MD Start IV fund is managed through a French UP vehicle with €20,000 of capital and one €10,000 SLP share, not an €82m balance sheet.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
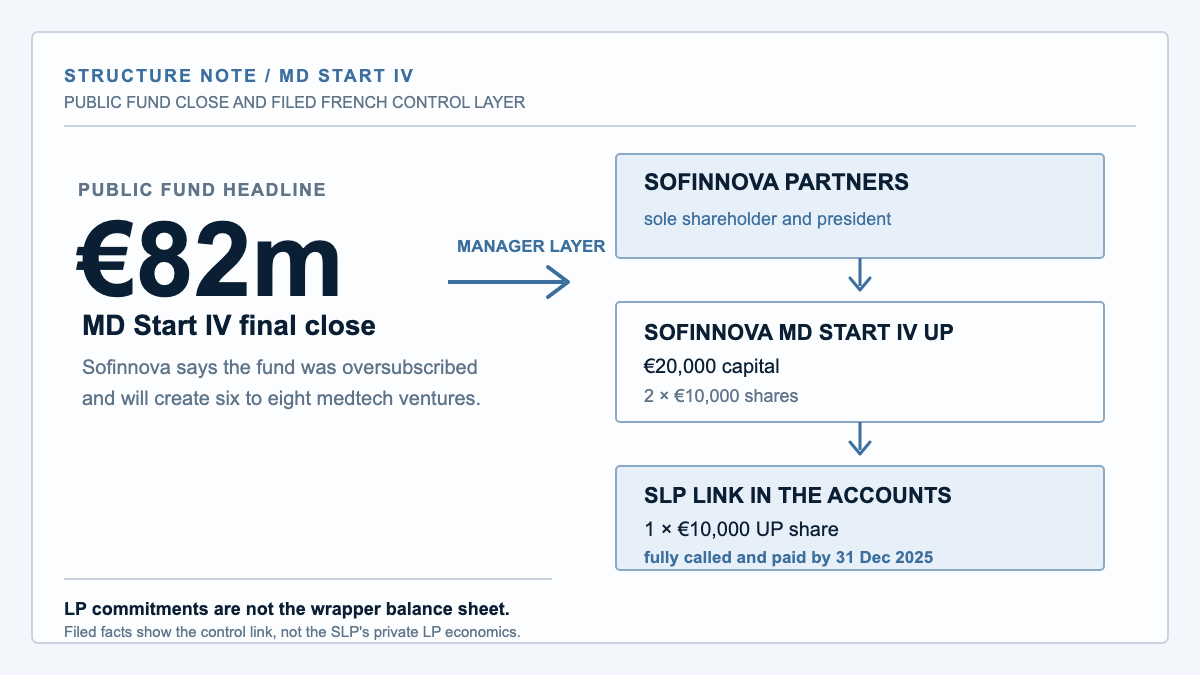
Sofinnova Partners' €82 million final close for MD Start IV is connected to a French company with €20,000 of share capital and one €10,000 share in the fund's société de libre partenariat (SLP). The legal wrapper is not an €82 million balance sheet. It is the manager-controlled layer that links Sofinnova Partners to the fund vehicle.
That distinction changes what the public close means. Sofinnova's announcement describes an oversubscribed fund that will create six to eight medtech companies across Europe and the United States over the next five years. The French corporate record describes a separate SAS, SOFINNOVA MD START IV UP, whose sole shareholder and president is Sofinnova Partners. Its statutes give the company a purpose that includes acting as general partner and/or manager in a French SLP, while its first accounts show a €10,000 investment in one UP share of SOFINNOVA MD START IV S.L.P.
The documents therefore make the control architecture visible without disclosing the limited-partner commitments behind the €82 million headline. For investors and counterparties, the useful question is not whether a €20,000 company can contain €82 million. It is which rights sit in the wrapper, which capital sits in the SLP, and which economics remain outside the public record.
The headline fund and the legal wrapper are different layers
The 28 September Sofinnova announcement says MD Start IV reached an €82 million final close and was oversubscribed. The firm says the fund extends its company-creation strategy and will support six to eight new medtech ventures over five years. Sofinnova also describes itself as managing more than €4 billion across its platform.
The French register record concerns a different legal person. Pappers identifies SOFINNOVA MD START IV UP as an active SAS, SIREN 931 480 933, incorporated on 25 July 2024 at Sofinnova's Paris address. It reports €20,000 of share capital and names Sofinnova Partners as president. The CNMV record for Sofinnova MD Start IV S.L.P. separately identifies the French fund and Sofinnova Partners as its manager.
| Layer | Source-backed fact | Business meaning |
|---|---|---|
| Public fund | MD Start IV announced an oversubscribed €82m final close on 28 September 2026 | The figure is the fund's public fundraising headline, not the capital of the French UP company |
| French UP vehicle | SOFINNOVA MD START IV UP is an active SAS with €20,000 capital and Sofinnova Partners as sole shareholder and president | The visible manager-controlled entity supplies a legal and governance layer around the SLP |
| SLP | The UP company's accounts identify one €10,000 “UP” share in SOFINNOVA MD START IV S.L.P. | The filed investment connects the wrapper to the fund vehicle without publishing the fund's LP register |
The separation is familiar in private-market structures. A fund can have substantial commitments from limited partners while a general-partner or “UP” company holds only the small share needed for its role in the partnership. The public record supports that architecture here. It does not support treating the wrapper's paid-in capital as a proxy for the fund's size, or treating the fund's headline size as money held by the wrapper.
Two €10,000 shares put Sofinnova Partners at the control layer
The incorporation documents are unusually direct about the first step. The statutes set the SAS's capital at €20,000, divided into two shares of €10,000 each. The subscriber list names Sofinnova Partners, SIREN 413 388 596, as the sole subscriber for both shares and records €20,000 paid. A deposit certificate from Société Générale Securities Services records the deposit made in July 2024.
The statutes also define the company's object. It includes participation, as a general partner and/or manager, in any French société de libre partenariat, along with acquiring, subscribing for, holding and managing securities. That is a functional description of a fund-control vehicle, not a statement that the SAS owns all of the SLP's assets.
The role is consistent with the MD Start strategy page, which presents Sofinnova as the hands-on company builder and names the team leading the strategy. It is also consistent with the CNMV record, which lists Sofinnova Partners as manager of the fund. The sources converge on the manager relationship while leaving the LP economics private.
The one-share link is the key filed fact. In the first annual accounts, the French UP company records a €10,000 financial investment identified as one “UP” share in SOFINNOVA MD START IV S.L.P. The notes say that the share was acquired in 2024 and fully called and paid by 31 December 2025. One share can be enough to carry a prescribed partner or management role. It does not need to equal the fund's capital commitments.
The first accounts show what the wrapper actually carries
The annual accounts cover 22 July 2024 to 31 December 2025 and were filed on 8 September 2026. They show the small vehicle's resources after the setup and the purchase of the SLP share:
| Account item at 31 December 2025 | Filed amount | Reading supported by the accounts |
|---|---|---|
| Share capital | €20,000 | The two €10,000 shares subscribed by Sofinnova Partners |
| Cash | €10,301.15 | Cash remaining after the wrapper's setup and operating movements |
| Financial investment | €10,000 | One UP share in SOFINNOVA MD START IV S.L.P., fully called and paid |
| Net result | €256.15 | A small accounting profit, not a measure of the fund's performance |
The account values add up to a simple but important boundary: the UP company's visible assets are roughly €20,301, not €82 million. That is not a contradiction in a partnership structure. It is evidence that the fund's LP commitments and portfolio assets sit elsewhere, in the SLP and its related banking and custody arrangements, rather than in the SAS's balance sheet.
The same point appears in the deposit and subscriber documents. They prove how Sofinnova Partners funded the wrapper at formation. They do not prove how much each limited partner committed to MD Start IV, how much has been called, or how the fund will allocate capital between new company creation and follow-on support.
Why the small wrapper matters to investors
The practical value of the French record is not a surprise about the size of the fund. It is a map of where different risks and rights are likely to sit. Sofinnova Partners is visible as the sole shareholder and president of the UP company. The UP company holds one share in the SLP and is designed to act as a general partner and/or manager. The public announcement, meanwhile, speaks for the fund's investment programme and LP backing.
That map matters in diligence. If a counterparty is assessing who can bind the fund, the UP company's statutes and the fund's partnership documents are more relevant than the wrapper's cash balance. If an investor is assessing capital at risk, the LP commitment schedule, capital-call notices and SLP accounts are the relevant documents. If a creditor is assessing recourse, the question is whether a claim sits against the UP, the SLP or another service entity. The four public documents used here answer only the first part of that chain.
Other European fund structures show the same separation. Headline's EU VIII records distinguish a Luxembourg fund from the entities associated with its management layer, while Titanbay's ELTIF platform shows how a regulated investment vehicle can be formed separately from the platform that distributes or manages it. Those examples do not prove Sofinnova's fee or ownership terms. They show why a wrapper's nominal capital should not be read as a fund-size number.
The structure also disciplines the public narrative. Sofinnova can truthfully describe an €82 million final close while the UP company's accounts truthfully show €20,000 of capital. The two facts refer to different entities. The mistake would be to collapse them into one balance sheet, or to infer from the small wrapper that the fund itself is undercapitalised.
The next document would answer the economic questions
The current record proves a manager-controlled French wrapper, its €20,000 formation capital, its €10,000 investment in one UP share and the public €82 million fund close. It does not publish the SLP's limited partners, commitment amounts, capital-call status, carried-interest terms, management-fee flows or the distribution of voting and economic rights between the partner classes.
Those questions are not academic. They determine whether the €82 million is fully committed, how much has been called, what the UP share entitles Sofinnova Partners to do, and whether any economics are paid at the wrapper or fund level. A prospectus, partnership agreement, SLP annual accounts or investor report could settle them. The public CNMV listing confirms the fund and manager relationship, but it does not supply those private terms.
The safe conclusion is therefore affirmative and narrow: Sofinnova MD Start IV is publicly presented as an €82 million fund, and its control layer is a French UP company with €20,000 of capital and one fully paid €10,000 share in the SLP. The wrapper explains who sits at the manager layer. It is not evidence that the fund raised only €20,000, and it is not the fund's balance sheet.
Continue reading
Related Research
Headline's $400m Fund Is Real. Its Manager Map Is Not Yet Singular
Headline's $400m EU VIII is an active Luxembourg AIF, but CSSF and CNMV records map it to two AIFM relationships while LP economics remain undisclosed.
Titanbay's Luxembourg platform predates LFDE's €1,000 ELTIF launch
Titanbay's Luxembourg SICAV was formed months before LFDE's €1,000 ELTIF launch, putting a legal platform behind the public private-markets partnership.
Project Ventures’ £5m Fund Splits General-Partner Vote From Carry
Project Ventures’ £5m fund gives Infra One 75%+ voting rights in the general partner while Project Ventures Consulting holds 75%+ of surplus assets.
ECIIF's €10m Guarantee Covers Loans, Not Its Equity Risk
ECIIF II closed €21.45m toward an €80m target, but its €10m InvestEU guarantee protects qualifying loans, not the fund's equity investments.