
Project Ventures’ £5m Fund Splits General-Partner Vote From Carry
Project Ventures’ £5m fund gives Infra One 75%+ voting rights in the general partner while Project Ventures Consulting holds 75%+ of surplus assets.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
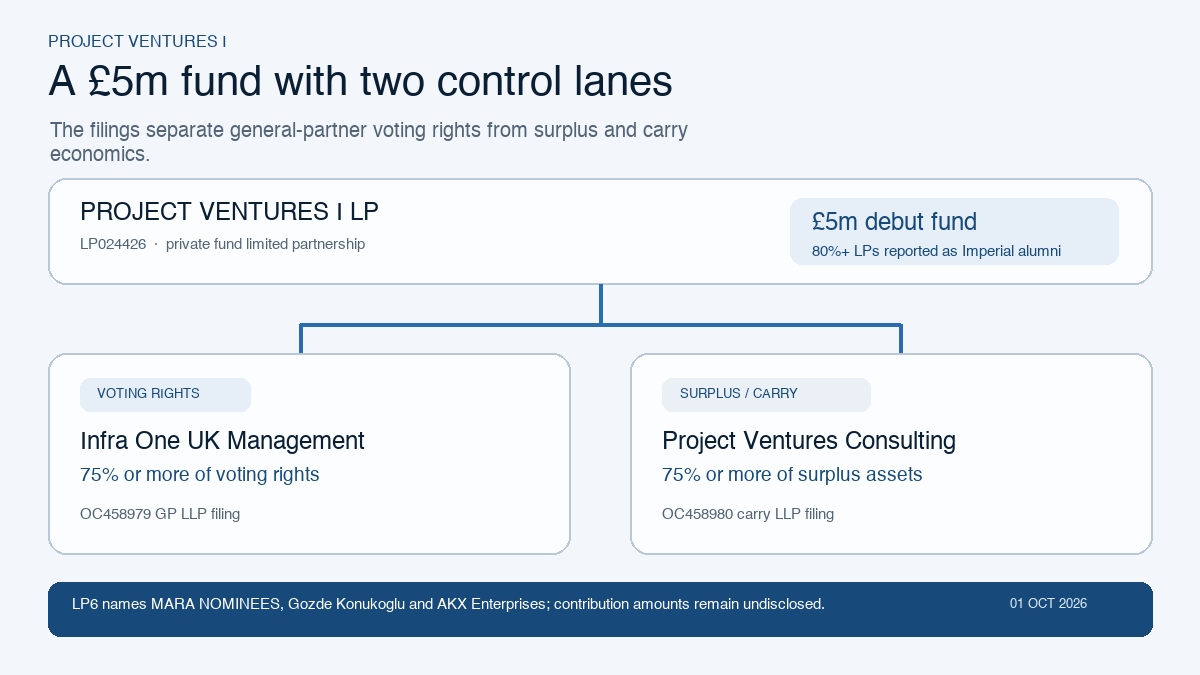
Project Ventures launched a £5 million fund with an Imperial College London alumni pitch. Its Companies House filings show a more specific economic design: the general partner (GP) voting rights sit with Infra One UK Management Limited, while Project Ventures Consulting Ltd holds the right to at least 75% of surplus assets in both the general-partner and carry vehicles.
That split separates who can vote in the fund’s management entities from who receives their residual economics. The public launch story says more than 80% of limited partners are Imperial alumni and that the fund targets pre-seed and seed deeptech and artificial-intelligence companies. The filings add the governance layer that a fundraising announcement cannot: the alumni network is the sourcing story, while the legal entities divide control and carry.
A £5m alumni fund has a two-part management stack
Project Ventures’ own site describes an early-stage investment firm rooted in the Imperial ecosystem and focused on deep tech and artificial intelligence. It names Shahryar Barati as founder and general partner and identifies Project Ventures Consulting Ltd, company number 15265851, as the trading entity. Tech.eu’s launch report puts the debut fund at £5 million, with £100,000 to £300,000 cheques and three investments already completed. It also reports that more than 80% of limited partners are Imperial alumni.
The legal fund is PROJECT VENTURES I LP, registered as LP024426. A 22 December 2025 filing designates it as a private fund limited partnership. The same filing names PROJECT VENTURES I GP LLP as general partner and PROJECT VENTURES I CARRY LLP as limited partner for the registration. The two management vehicles were incorporated on 1 December 2025 under numbers OC458979 and OC458980.
The fund and the management stack therefore answer different questions. The launch describes whom Project Ventures wants to back and where its network comes from. The filings show which entities sit between those investors and the fund’s governance and residual economics.
The fund’s limited-partner register names three later entrants
The 24 March 2026 LP6 filing for Project Ventures I LP says that three limited partners were admitted: MARA NOMINEES LIMITED, Gozde Konukoglu and AKX ENTERPRISES LTD. The form does not state the amount contributed by any of them. That distinction matters because the public launch’s “80% Imperial alumni” statistic is a statement about the wider LP population, not proof that any named entrant is an alumnus or that any one entrant supplied a particular share of the £5 million.
The filing makes the legal admission visible without turning it into an ownership ranking. MARA NOMINEES LIMITED is a nominee, and the register does not identify the underlying investor. AKX ENTERPRISES LTD is a corporate entrant, but the LP6 does not disclose its commitment or its economic rights. Konukoglu is named personally, yet the form still gives no contribution amount.
This is the first break between the fund’s marketing language and its economic record. The alumni statistic describes a community around the fund. The LP6 names the legal partners who entered at that point in time, but it cannot establish their capital weights.
Infra One controls the general-partner vote while Project Ventures Consulting holds the residual side
The incorporation filing for PROJECT VENTURES I GP LLP identifies two corporate designated members: Infra One UK Management Limited, company number 15516742, and Project Ventures Consulting Ltd, company number 15265851. The filing records two different rights. Infra One holds, directly or indirectly, 75% or more of the LLP’s voting rights. Project Ventures Consulting holds, directly or indirectly, the right to share in 75% or more of the surplus assets on a winding up.
The carry vehicle repeats the allocation in the opposite order of emphasis. Its incorporation filing names Project Ventures Consulting and Infra One as the two designated members. Project Ventures Consulting holds the 75% or more surplus-assets right, while Infra One holds 75% or more of the voting rights.
| Layer | Filed legal fact | Commercial meaning | What remains private |
|---|---|---|---|
| Project Ventures I LP | LP024426 was designated a private fund limited partnership on 22 December 2025 | The fund is the pooled investment vehicle | LP commitments, allocations and return terms |
| Project Ventures I GP LLP | Infra One has 75%+ of voting rights; Project Ventures Consulting has 75%+ of surplus assets | Governance votes and residual value sit with different corporate members | The agreement’s full decision and distribution mechanics |
| Project Ventures I Carry LLP | Project Ventures Consulting has 75%+ of surplus assets; Infra One has 75%+ of voting rights | The carry vehicle mirrors the separation between vote and residual economics | The size and trigger of any carry distribution |
| LP6 admission | MARA Nominees, Gozde Konukoglu and AKX Enterprises were admitted | The legal LP register is more specific than the alumni headline | Each entrant’s contribution and beneficial owner |
The distinction is not a claim that the structure is unusual or improper. Fund partnerships commonly separate a management decision-maker from entities that participate in carried or residual economics. The filing does establish a narrower point: the company that can control votes is not the company that is identified with the 75% or more surplus-asset right.
That is the governance fact an investor, founder or competing manager would need to carry into diligence. A fund can have a strong community brand while its legal control and carry routes run through a separate sponsor platform.
The Allocator One connection explains the platform, not the LP economics
Infra One’s public materials describe a fund-operations platform associated with Allocator One. They promote fund formation, capital calls, LP contributions and compliance as a service for emerging managers. The Companies House filing for Project Ventures I GP LLP does not say that Infra One is the fund’s investment adviser, nor does it assign it a share of investment profits. It records the 75% or more voting-rights position in the GP and carries the entity’s legal name.
Project Ventures Consulting is the firm’s public-facing trading company. Project Ventures’ website says it is an independent venture capital firm and makes clear that references to Imperial College London describe the origin and network of the firm, not an endorsement by the university. Tech.eu reports the strategy as pre-seed and seed investing across robotics, healthcare, climate, energy and advanced manufacturing.
Together, the public and filed sources give a coherent commercial explanation. Project Ventures brings the Imperial network and investment thesis. Infra One supplies a platform connected to fund administration and holds the GP vote. Project Ventures Consulting retains the residual side identified in the GP and carry filings. What they do not provide is a private-partner waterfall, a carry percentage or a contribution schedule.
“Imperial alumni fund” is a sourcing proposition, not a control map
For founders, the alumni network may be the immediate value proposition: access to Imperial-linked deal flow, technical expertise and early cheques. For limited partners, the more material questions are governance and economics. Who can approve an investment? Which entity receives management or carry income? What happens if the sponsor platform changes? The public launch and the LP6 answer only parts of those questions.
The EQT and Coller manager-carry record shows why a fund manager’s legal entities can matter as much as the headline commitment. Project Ventures is smaller and earlier, but the same diligence principle applies. The £5 million size does not tell an LP how votes, residual value and admission rights are allocated.
The structure also limits what can be said about the named LPs. A nominee entry is not a beneficial-owner disclosure. A corporate LP entry is not a commitment amount. And an alumni statistic is not a cap table. The filings show the legal perimeter, not the private returns that may sit behind it.
The next document is the partnership agreement, not another launch story
Project Ventures has made three investments and plans to close its debut fund by summer 2027, according to Tech.eu. The next decision-changing document is therefore not a new announcement about the Imperial network. It is the partnership agreement, an amended LP filing, or accounts for the GP and carry entities that show how investment decisions, management fees and residual distributions work in practice.
The current record supports a precise conclusion. Project Ventures’ fund is legally pooled in a private fund limited partnership, its LP register names three later entrants without contribution amounts, and its GP and carry filings place 75% or more of voting rights with Infra One while assigning 75% or more of surplus assets to Project Ventures Consulting. The public alumni narrative explains access to founders. The filed control split explains who sits behind the economics.
Continue reading
Related Research
EQT Bought Coller's Manager and Carry Rights, Not Its Fund Assets
EQT's $3.2bn Coller deal buys management and GP entities plus carry rights, while Companies House shows the UK operating manager rather than fund assets.
E2D's €500m Defence-Fund Target Has a Luxembourg Vehicle, Not a Public LP Ledger
E2D’s €500m defence-fund target now has a Luxembourg vehicle, an IQ EQ AIFM and a July first close, but LP commitments and allocation control remain undisclosed.
Uplift Ventures’ €100m Fund Is A Layered Jungheinrich Platform
Uplift Ventures’ €100m fund sits inside a Jungheinrich-backed platform with separate GP, management and partner vehicles, not one undifferentiated pool.
Trigify’s HubSpot Exit Left 2,149 B Shares Unexplained
Trigify said its team was joining HubSpot. Companies House filings show fund:AI’s 5.68% A-share position and 2,149 non-voting B shares issued on 23 September.