
Olenbee’s €7m Round Follows €2.82m of Priced Equity and Share-Convertible Debt
Olenbee announced a €7m round after French filings recorded €2.82m of priced share issues and €475k of obligations converted into 22,568 shares, without naming holders.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
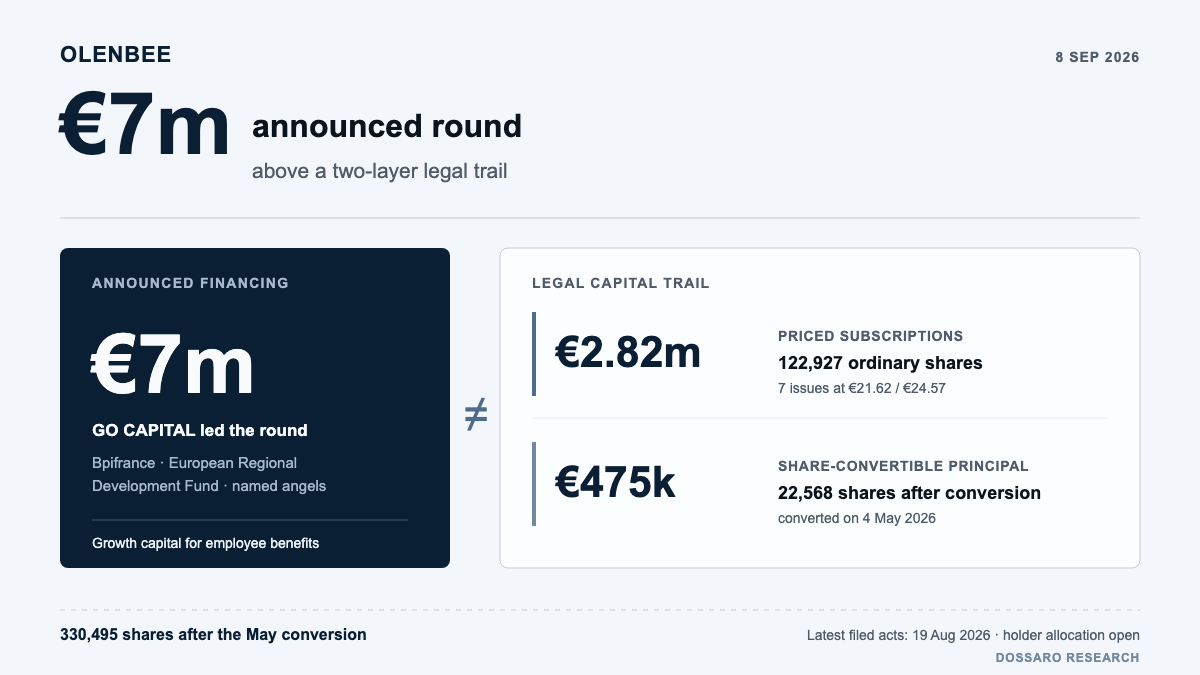
Olenbee’s €7 million financing announcement sits on top of a much smaller but clearly priced legal trail. French company records show €2.82 million of stated subscription value across seven ordinary-share issues, followed by €475,000 of obligations converted into 22,568 shares. The register therefore shows a sequence of private placements and share-convertible debt, not one visible €7 million ordinary-equity issue.
That distinction changes what a financing reader can underwrite. The public round establishes Olenbee’s growth ambition and named backers. The filings establish price points, share counts and the point at which convertible obligations became equity. They do not connect a particular investor to a particular percentage or allocate the September headline across the legal capital record.
The €7m announcement is a growth promise
GO Capital’s 8 September announcement says Olenbee raised €7 million to expand its artificial-intelligence and open-banking infrastructure for employee benefits. It names GO CAPITAL, Bpifrance, the European Regional Development Fund, Val de France Angels and All’n Breizh among the backers. Olenbee says the money will help it grow its French customer and user base, target 80,000 users by early 2027 and extend beyond meal vouchers and gift cards into cashback, culture and mobility.
Fintech Global’s independent report confirms the €7 million round, the GO CAPITAL-led backing and the public-cofinancing and angel participation. It describes Olenbee as a French financial-technology company founded in 2024 that connects employee benefits with everyday card spending. Neither public account supplies a valuation, an instrument schedule or an entity-level allocation.
The announcement is a group and product statement. The legal record concerns OLENBEE, a French société par actions simplifiée registered in Rouen under SIREN 933025371. Keeping those scopes separate prevents a headline financing number from being mistaken for the nominal capital of the operating company.
The register shows a priced share ladder
The company’s amended statutes set an initial €185,000 cash contribution on 9 September 2024, divided into 185,000 ordinary shares with a €1 nominal value. Subsequent decisions repeatedly removed preferential subscription rights for defined categories and issued ordinary shares at two prices. The October 2025 capital decision records the four 2025 tranches; the February and March 2026 acts and 13 March record carry the later price.
| Date of issue | Ordinary shares | Price per share | Stated subscription value |
|---|---|---|---|
| 9 Dec 2024 | 30,865 | €21.62 | €667,301.30 |
| 25 Apr 2025 | 17,814 | €21.62 | €385,138.68 |
| 18 Jul 2025 | 11,565 | €21.62 | €250,035.30 |
| 8 Sep 2025 | 9,137 | €21.62 | €197,541.94 |
| 4 Feb 2026 | 8,954 | €24.57 | €219,999.78 |
| 24 Feb 2026 | 11,014 | €24.57 | €270,613.98 |
| 3 Apr 2026 | 33,578 | €24.57 | €825,011.46 |
Together, the seven issues created 122,927 shares and state €2,815,642.44 of subscription value. The last tranche included €794,986.92 paid in cash and €30,024.54 settled by compensation with a current-account claim. The total is therefore best read as priced subscription value, not as proof that every euro was fresh cash at the April closing.
The two price points are still commercially useful. The first four issues were priced at €21.62 per share. The February and April 2026 issues used €24.57, including a €23.57 issue premium over the €1 nominal value. The records show the terms offered to targeted subscriber categories, but they do not name the people or funds behind the ordinary-share lines.
Convertible obligations added a second layer
Olenbee also issued obligations redeemable into ordinary shares, known in the filings as ORA2025. The 28 October 2025 issue comprised 170,000 obligations, the 14 November issue 255,000 and the 15 January 2026 issue 50,000. The 4 May 2026 president’s decision records their conversion at maturity into 8,104, 12,113 and 2,351 ordinary shares, respectively.
The conversion produced 22,568 shares against €475,000 of principal plus accrued interest. Principal divided by the converted-share count implies about €21.05 per share before interest. That is a calculation from the conversion record, not a disclosed holder price or a company valuation. The decision lists lines by obligation quantity, interest and resulting shares, so it proves the instrument path without identifying who received the stock.
The conversion also changes the denominator used in any dilution discussion. Before it, the April issues had taken nominal capital to €307,927. The conversion decision says the company then issued 22,568 shares and moved capital to €330,495. The updated statutes repeat €330,495 in Article 7, although their cover page says €330,945. The article text and the execution decision are the consistent basis for the arithmetic; the cover-page difference remains a document-level discrepancy.
If the original 185,000 shares remained outstanding and no other classes existed, the 330,495-share post-conversion denominator would put the original pool at about 56.0 percent, the seven priced issues at 37.2 percent and the converted obligations at 6.8 percent. This is a structural scenario, not a holder-level cap table. Transfers, other rights or a later September issue could change it.
The visible capital is not the announced round
The priced issues and the ORA principal add up to about €3.29 million. Roughly €3.71 million of the €7 million announcement is outside those visible amounts. That gap is not evidence that the public round failed to close. The announcement could include debt, grants, a later subscription after the latest filing or proceeds booked in a related entity. It does show why “€7 million raised” and “€7 million of new ordinary shares in OLENBEE” are different claims.
The timing supports that reading. The latest returned acts were filed on 19 August 2026, while the public announcement is dated 8 September. A filing lag could therefore account for some or all of the September capital not yet appearing in the register. Conversely, the public figure may deliberately combine equity with other financing sources. The available record cannot choose between those explanations.
Fundcraft’s recent financing illustrates the same entity-scope problem: a €12 million group growth round sat beside a French subsidiary’s €1.24 million internal capital conversion, and the French act did not turn the group headline into subsidiary cash. Zuriq’s preferred-share analysis shows the complementary issue: a round becomes more informative when the legal share class and rights are visible. Olenbee’s public materials currently supply neither a post-round class schedule nor holder mapping.
What investors can underwrite now
The evidence supports three firm conclusions. First, Olenbee has announced a €7 million financing backed by GO CAPITAL, public co-financiers and angels to scale a real-time employee-benefits platform. Second, OLENBEE’s RNE history records €2.82 million of priced ordinary-share subscriptions across 2024–26, with a higher 2026 price. Third, €475,000 of ORA2025 principal was converted into 22,568 ordinary shares in May 2026.
Those facts make the financing quality more legible than the headline alone. The company used repeated targeted issues rather than one single visible placement. It also carried share-convertible obligations through 2025 and early 2026, then converted them into stock before the September announcement. For a venture investor, the next diligence task is to reconcile the public round’s instrument mix with the 330,495-share legal denominator. For a buyer or later-stage investor, it is to establish whether the September money sits in OLENBEE, a parent or a financing vehicle.
The records still do not support percentages for GO CAPITAL, Bpifrance, the European Regional Development Fund, Val de France Angels, All’n Breizh or any individual angel. They also do not establish whether the latest headline includes grants or debt, or whether every announced euro had arrived by 8 September. Those are allocation questions, not reasons to rewrite the documented issue history.
The next filing that would close the gap
The next useful record is a post-September capital increase, updated statutes or shareholder document that names the issuer, instrument and subscriber allocations. It would show whether the €7 million was a fresh issue at a new price, a package combining equity with debt or grants, or a financing completed after the August filing cut-off.
Until that record appears, Olenbee’s financing should be read as a two-ledger event. The public ledger says €7 million will fund product and market expansion. The legal ledger says the company reached that announcement through €2.82 million of priced share subscriptions and €475,000 of obligations converted into shares. The headline establishes scale; the filings establish the capital mechanics that investors still need to reconcile.
Continue reading
Related Research
Fundcraft's €12m Growth Financing Sat Beside a €1.24m Internal Capital Conversion
Fundcraft announced €12m of group growth financing while its French AIFM converted €1.24m of shareholder debt into capital without a cash remittance.
ZuriQ's $25.5m Seed Created A 28.6% Preferred Block
ZuriQ's $25.5m seed closed legally in May, creating a 28.6% preferred block and adding a Quantonation-linked director before its July reveal.
Volta's $300m Raise Had A 30.5x Nominal Share-Price Ladder
Volta's $300m raise hid a 30.5x nominal price ladder from $58 Seed shares to $1,769.91 Series A stock, plus preferred rights and $2m of debt set-off.
Skylance’s €500k NRW.BANK Round Turns Debt Into a Control Question
NRW.BANK is putting €500,000 into Skylance through debt conversion and fresh capital, while the last known register remains founder-owned 50/25/25.