
HyImpulse's €50m Round Lands on a 76.43% Holding Block
HyImpulse's €50m financing meets a register where HylImpulse Holding and Schwarz Holding held 76.43% before the round, leaving post-round control unresolved.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
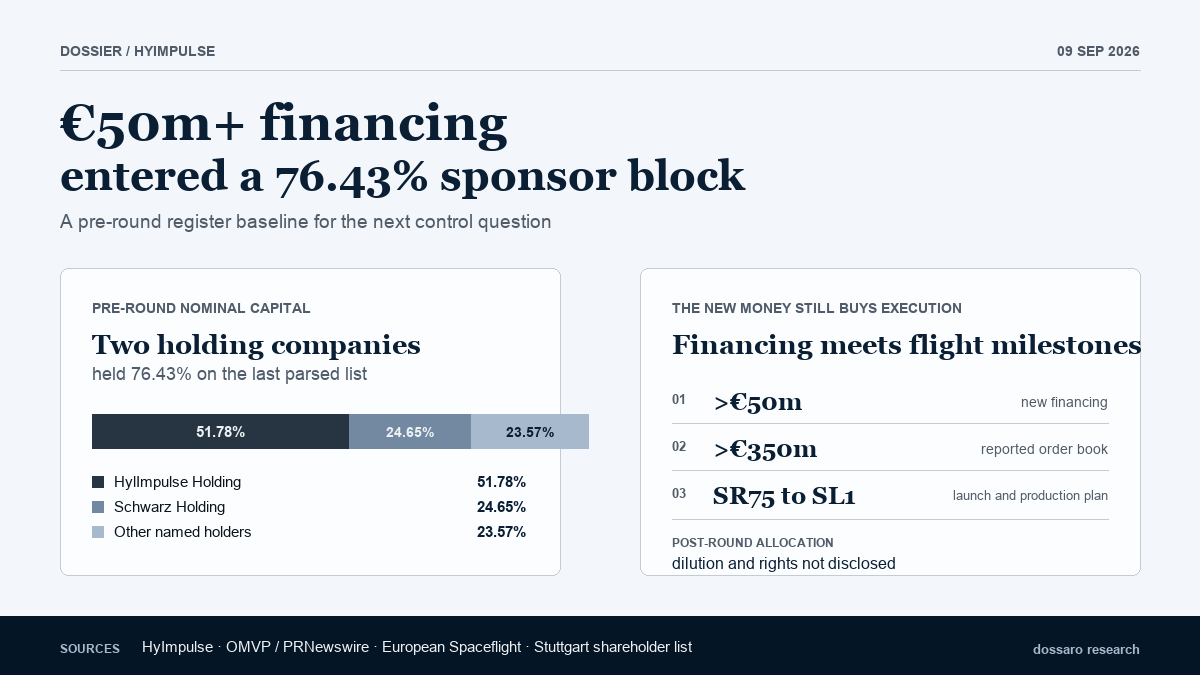
HyImpulse's more than €50 million financing is landing on a register whose last parsed shareholder list assigned 76.43% of the company to two holding vehicles. That is not a post-money cap table. It is the clearest available starting line for the new capital: HylImpulse Holding GmbH and Schwarz Holding GmbH controlled the legal entity before the round that is now being sold as a sovereignty and launch-capacity story.
The distinction changes the commercial reading. HyImpulse says the financing will fund a second SR75 launch, the maiden flight of its SL1 orbital vehicle, production expansion and commercial and defence growth. It also reports an order book above €350 million. Those are substantial demand and execution signals, but the public announcement does not state the new investors' cheques, issue price, share classes, dilution or voting rights. The unresolved question is therefore who now carries control and launch risk, not whether the round exists.
The financing headline is stronger than the ownership disclosure
HyImpulse's own press-release archive lists the 2 September 2026 announcement as a financing of more than €50 million to scale commercial suborbital and orbital operations. The OMVP release on PRNewswire calls the investment co-led financing and says OMVP was the only US participant selected. The company says the money will support the second SR75 launch, SL1's maiden orbital flight, expanded production and commercial operations.
The independent descriptions add useful context but do not fill the cap-table gap. European Spaceflight and TechFundingNews identify JOIN Capital and Ace Capital Partners as the co-leads, alongside North Ventures, BW-Capital, Bayern Kapital, the German Aerospace Centre and returning Campus Founders Ventures. The public record therefore carries two lead descriptions, one from the US investor and another from independent coverage. Neither account gives an investor-by-investor allocation.
| Public signal | What the sources establish | What remains unreported |
|---|---|---|
| Series A extension | More than €50m of new financing, described by the company and investors as equity funding | Subscription amounts, issue price, class rights and post-round ownership |
| Commercial demand | An order book above €350m across suborbital and orbital programmes | Recognised revenue, cash collected, margin or delivery certainty |
| Capital purpose | A second SR75 flight, SL1's maiden flight, production and commercial or defence growth | Milestone dates beyond the sources' stated plans and the capital still required |
| Investor frame | OMVP, JOIN, Ace, North Ventures, BW-Capital, Bayern Kapital, DLR and Campus Founders Ventures are named across the releases | Which participant led legally, received which securities or obtained governance rights |
The earlier HyImpulse analysis on dossaro treated the event as a public-private commercialisation bet because that was the strongest public-source finding at the time. The new register evidence makes the next question more precise. The financing entered a company that was not an unowned project vehicle. It entered a concentrated legal shareholder base with an identifiable block at the top and a long tail of smaller positions below it.
A 76.43% block was visible before the round
The exact legal entity is HyImpulse Technologies GmbH, registered with the local court of Stuttgart as HRB 764976 and based in Neuenstadt am Kocher. The company imprint confirms that identity. A shareholder list taken into the register file on 4 December 2025 records €47,561 of registered capital and 13 named holders. The list refers to a 25 July 2025 notarial deed and a 4 November 2025 managing-director resolution.
HylImpulse Holding GmbH held €24,628, or 51.78%, while Schwarz Holding GmbH held €11,722, or 24.65%. Adding those two displayed percentages gives 76.43%. The remaining named holders account for the residual 23.57% after subtracting the two largest positions. This is a calculation from nominal share amounts in the register. It is not a valuation, a measure of cash invested or an estimate of the September 2026 post-money ownership.
| Holder in the 4 December 2025 list | Nominal amount | Stated share |
|---|---|---|
| HylImpulse Holding GmbH | €24,628 | 51.78% |
| Schwarz Holding GmbH | €11,722 | 24.65% |
| Campus Founders Ventures GmbH | €3,615 | 7.60% |
| Helantic GmbH & Co. KG | €1,446 | 3.04% |
| GIMIC GmbH | €1,446 | 3.04% |
| Sparkassenbeteiligungsgesellschaft Heilbronn-Franken mbH & Co. KG | €362 | 0.76% |
| Start-up BW Innovation Fonds GmbH & Co. KG | €867 | 1.82% |
| MBG Mittelständische Beteiligungsgesellschaft Baden-Württemberg GmbH | €217 | 0.46% |
| BTRON GmbH | €615 | 1.29% |
| Global Resilience Innovation Fund SCS SICAV-RAIF | €1,446 | 3.04% |
| VIENNA POINT a.s. | €542 | 1.14% |
| HIT Investment SPV UG (haftungsbeschränkt) & Co. KG | €303 | 0.64% |
| Thomas Gütermann | €352 | 0.74% |
| Total registered capital | €47,561 | 100% |
The top two positions matter because they create a measurable control base before the new money arrives. A 76.43% nominal block can support ordinary shareholder resolutions under many German GmbH situations, but the list alone does not reveal voting agreements, reserved matters, investor consent rights or any preferred economics. It shows the distribution of registered shares, not every way control can be exercised.
The remaining 23.57% carried a mixed investor history
The minority side is not a single outside fund. Campus Founders Ventures is the largest named position below the two holding companies at 7.60%. Helantic and GIMIC each hold 3.04%. The list also names Sparkassenbeteiligungsgesellschaft Heilbronn-Franken, Start-up BW Innovation Fonds and MBG, as well as BTRON, the Luxembourg Global Resilience Innovation Fund, Czech-listed VIENNA POINT, HIT Investment SPV and Thomas Gütermann.
That mix helps explain why the financing cannot be reduced to a founder-versus-venture-capital story. It includes regional and public-backed vehicles, cross-border investors and individual or special-purpose positions. The register does not say that any one of those holders acts for another, shares a voting agreement or has a board right. Their legal names are evidence of positions in the list, not proof of a common control group.
The filing also marks the HIT Investment SPV and Thomas Gütermann shares as having arisen through a capital increase. That detail shows that the pre-round structure already included issued-capital changes rather than only founder transfers. It still does not identify the price or instrument behind the September 2026 financing. The Phantasma financing analysis illustrates the same diligence boundary from another sector: the share register can set the starting line while a strategic investor's cheque remains different from its eventual equity percentage.
New money does not map directly to new control
The public financing language invites a quick conversion from cheque size to ownership. That conversion would be unsafe here. The round is reported as more than €50 million, but the sources do not disclose the pre-money valuation, the exact amount subscribed by each participant, the number of new shares or whether any securities were issued with conversion or preference rights.
Even the lead-investor description needs to be kept source-specific. OMVP presents itself as a co-lead. European Spaceflight and TechFundingNews describe JOIN and Ace as co-leads. That difference may reflect several instruments, different release ownership or a loose use of the word lead. It is not evidence that one participant controls HyImpulse.
The same discipline applies to the order book. The company reports more than €350 million of demand across its programmes. Comparing the two lower bounds, €350 million divided by €50 million equals 7, but that is only a floor-to-floor arithmetic reference. Because both figures are thresholds, it is not an actual order-book-to-capital ratio. The order book can include contracts, options or milestone-linked commitments, and the reviewed sources do not provide a customer schedule or cash-conversion timetable.
The economic consequence is that the new equity must buy evidence, not only runway. HyImpulse has to turn capital into launches, production throughput and customer delivery. If the post-round register later shows the two holding companies retaining a large majority, the financing will look like concentrated sponsorship of a scale-up plan. If new shares materially dilute them or give investors consent rights, the same announcement will mark a control transition. The public material cannot choose between those outcomes yet.
The next test is flight evidence, not another headline
The company says its hybrid propulsion platform supports both suborbital and orbital vehicles. It completed an SR75 flight from the Koonibba Test Range in South Australia in 2024. Independent coverage says the second SR75 flight is being prepared for SaxaVord Spaceport in Scotland, while the new financing release places SL1's maiden flight and production expansion in the use-of-capital plan.
Those milestones connect ownership to commercial risk. A second flight can test repeatability and customer delivery. SL1's first orbital attempt will test a larger vehicle and a different operating model. Production expansion raises fixed costs before the order book becomes recognised revenue. Public and private investors may share the strategic objective of European launch capacity, yet the legal allocation of losses, preferences and decision rights will determine who absorbs a missed launch or an extended schedule.
This is why the register's 76.43% block is commercially useful even though it is historical. It tells customers, employees and investors that the new financing started from a company with a visible sponsor base. It also provides a benchmark against which the next shareholder list can be read. Without that benchmark, a future percentage would be a number without a clear before-state.
What the next filings should settle
The next decisive documents are the post-round shareholder list, the subscriber or allotment material and any notarial deed tied to the 2026 capital increase. They should show whether the round was entirely primary issuance, included transfers or used instruments that will convert later. They may also reveal issue price, share classes, dilution, voting rights and investor-level consent provisions.
Until those records are accessible, the strongest defensible conclusion is narrow. HyImpulse has announced more than €50 million for a launch programme with an order book above €350 million. Its last parsed shareholder list, dated 4 December 2025, shows HylImpulse Holding and Schwarz Holding at 76.43% of nominal capital. The financing is therefore a measurable control-and-execution transition in waiting, not a verified post-money control change.
Continue reading
Related Research
HyImpulse's €50m Series A Turns Rocket Sovereignty Into a Public-Private Risk Bet
HyImpulse's €50m Series A extension pairs public and private capital with a €350m order book, but filings do not yet show who bears the new equity risk.
Phantasma’s €2.6m Round Makes Factory Access Visible Before Control
Phantasma Labs says Jet supplied €2.1m of a €2.6m round, while its last shareholder list shows founder transfers and a 37.72% outside block.
Nscale's $3bn AI Debt Sits on a New Holding-Company Security Stack
Nscale's $3bn AI-data-centre facilities follow a holding-company roll-up, a $3.695bn premium reset and GLAS charges over parent and Arkon equity.
Open Cosmos' Founder Held About 41% Before Its €300m Round
Open Cosmos' €300m round sits above a register where founder Rafael Jorda held about 41% of stated capital and preferred shares ranked ahead of ordinary.