
Forbion's €2.3bn Close Has a Visible $1.014bn US Split
Forbion's €2.3bn close spans growth and venture vehicles; SEC filings show $1.014bn sold across 37 investors, not one pool, with no LP allocation published.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
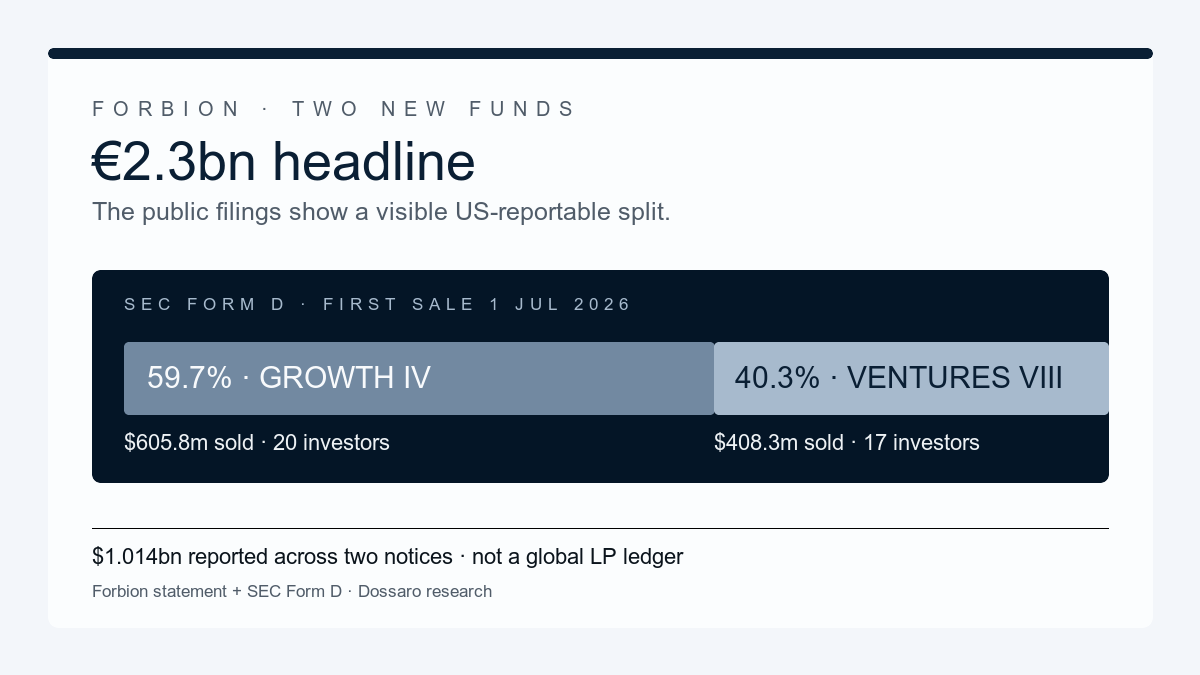
Forbion announced a €2.3 billion close across two life-sciences funds. The public filings show that the headline already contains a meaningful strategy split: the growth vehicle reported $605.8 million sold to 20 investors, while the venture vehicle reported $408.3 million sold to 17. Together, those US Form D notices disclose $1.014 billion, divided 59.7% to growth and 40.3% to venture.
That is not a reconstruction of the global close. Form D is a US exempt-offering notice, and Forbion's announcement describes a wider international fundraise. The filings do, however, make the two legal vehicles and their reportable capital visible in a way the single headline does not. They also show why naming the limited partners is not the same as assigning their commitments to a fund.
Forbion's 6 October announcement says the raise is its largest to date, lifts assets under management to approximately €7.5 billion and gives the two funds capacity to finance about 30 portfolio companies. It names MN, PGGM, KfW Capital, the Kauffman Foundation and Eli Lilly and Company among the participating institutions and corporates. The announcement describes the size and strategy. The SEC notices add a dated, vehicle-level view of the capital that was reported in the United States.
The headline combines two different investment jobs
Forbion Growth Opportunities Fund IV is described as a later-stage biopharma strategy for companies in Europe and North America. Forbion Ventures Fund VIII is described as a therapeutics-focused strategy that can invest in existing businesses and new ventures built around promising assets and teams. They sit under one Forbion fundraising announcement, but they are not one issuer.
The official SEC records identify the issuers as Forbion Growth Opportunities Fund IV Cooperatief U.A. and Forbion Ventures Fund VIII Cooperatief U.A. Both notices classify the issuer as a pooled investment fund and describe an indefinite offering. The records therefore speak to offerings by two legal vehicles, not to a single Forbion account that can be allocated by simply dividing the headline amount.
The same legal-vehicle distinction appears in the Spanish regulator's public data. The CNMV record for Growth IV identifies the fund as foreign alternative investment fund number 6813, for professional clients, with FCPM III Services B.V. named as management company. The CNMV list also identifies Ventures VIII as fund number 6814. Those regulatory records establish a fund and manager layer. They do not publish the limited-partner ledger.
What the two Form D notices disclose
The Growth IV notice was filed on 9 July 2026 after a first sale on 1 July. It records $605,761,800 sold, 20 investors and a minimum investment accepted of $3,430,830. The Ventures VIII notice was filed on the same date and records $408,325,200 sold to 17 investors. Its first sale date is also 1 July. Both notices report an offering amount and remaining amount as indefinite, which means the reported proceeds are not a stated final fund size.
The arithmetic is simple but useful. Adding the two reported amounts gives $1,014,087,000. Growth IV represents 59.7% of that disclosed total, and Ventures VIII represents 40.3%.
| Vehicle | Official Form D issuer | First sale | Amount sold | Investors | Share of the two-notice total | What the filing supports |
|---|---|---|---|---|---|---|
| Growth IV | Forbion Growth Opportunities Fund IV Cooperatief U.A. | 1 Jul 2026 | $605,761,800 | 20 | 59.7% | A US-reportable pooled-fund offering by the growth vehicle |
| Ventures VIII | Forbion Ventures Fund VIII Cooperatief U.A. | 1 Jul 2026 | $408,325,200 | 17 | 40.3% | A US-reportable pooled-fund offering by the venture vehicle |
| Combined | Two separate issuers | 1 Jul 2026 | $1,014,087,000 | 37 | 100.0% | The visible sum of these two notices only |
The table is a view of disclosed US offerings, not a capital-allocation model. Form D does not say that all of the investors in either notice are US institutions, and it does not list the amount subscribed by each investor. The number of investors is a count of investors already invested in the offering, not a count of all institutions named in Forbion's announcement.
Why the $1.014bn should not be compared as a missing €1.3bn
The temptation is to subtract the two Form D amounts from the €2.3 billion headline and label the difference unreported capital. That would overstate what the documents can prove. There are at least four reasons the scopes need to remain separate.
First, the Form D notices are dollar-denominated filings under a US private-offering exemption, while Forbion's announcement is a euro-denominated global fundraising figure. Currency conversion alone changes the comparison. Second, a US notice can cover a reportable slice of a fund that accepts commitments through several jurisdictions and vehicles. Third, a close announcement can describe commitments or a fund size that is not the same as cash sold under one notice on one filing date. Fourth, the two notices say the offering amount is indefinite, so they do not establish a final maximum or final close amount for either fund.
Forbion's own release says the two funds together will finance approximately 30 portfolio companies and that first investments have already been completed. That is evidence of intended deployment capacity and activity, not a statement that the $1.014 billion is the amount available for those companies. The Growth IV Form D and Ventures VIII Form D are the primary sources for the reported dollar amounts and investor counts.
A named LP is not an allocated cheque
The announcement names MN, PGGM, KfW Capital, the Kauffman Foundation and Eli Lilly and Company, alongside existing and new investors. That list is commercially relevant, but it does not tell the reader which vehicle each institution subscribed to, how much it committed or whether an institution invested in both strategies.
The SEC notices do not fill that gap. They identify each issuer, the offering category, the first-sale date, the amount sold and the investor count. They do not provide an LP-by-LP schedule. The independent AltStreet presentation of the Growth IV filing is useful as a cross-check for the $605.8 million notice, but it likewise does not turn the public record into a complete investor allocation.
This matters for the commercial reading of the close. A pension investor, corporate strategic or public-backed institution may have a different mandate for a later-stage growth fund than for an early venture strategy. If the same institution appears in both pools, its risk, reserve and liquidity profile can still differ by vehicle. If it appears in only one, the headline gives no way to infer that from the named-LP list alone.
For founders, the two-fund split also carries a practical signal. A company seeking a later-stage biopharma cheque is not approaching the same decision process as a new therapeutics venture. The strategy labels indicate different company stages and financing needs, while the Form D amounts show that the visible US offering is weighted toward Growth IV. That is a useful directional fact, not proof of the eventual portfolio mix or cheque sizes.
The structure is consistent with ordinary cross-border fund formation. Dutch cooperatives can serve as investment vehicles while a manager operates from another entity and regulatory records show the funds to professional clients in different jurisdictions. The public records do not indicate a dispute, a hidden owner or a failure to raise the announced amount. They show that the fundraise has more than one legal and reporting layer.
The next document that would change the story
The current evidence supports a narrow conclusion: Forbion's €2.3 billion announcement covers two distinct funds, and the paired SEC notices report $1.014 billion sold across 37 investors, with a 59.7% growth and 40.3% venture split within those notices. It does not support an LP-by-LP allocation, a global commitment total reconstructed from SEC data, or a claim that the remaining headline balance represents a shortfall.
The next decision-changing evidence would be an audited fund account, an offering memorandum, a regulator filing that states commitments by vehicle, or an official disclosure that maps named institutions to Growth IV and Ventures VIII. A later amended Form D could also update the reported proceeds or investor counts. Until one of those documents is public, the cleanest retelling is that the headline close is global and combined, while the visible US reporting is already separated by strategy.
That distinction is the same reason a fund wrapper should be read alongside its manager and investor evidence. White Star Capital Fund IV shows how one branded close can span parallel legal pools with institutional investors visible in different disclosures. Headline EU VIII shows a related manager-map problem: a fund can be real and regulated while the public record leaves operating responsibility and LP economics partly unresolved. Forbion's paired Form D filings add a more quantitative version of that lesson.
The evidence boundary remains firm. The two SEC notices are reportable slices, not a substitute for the global close. The named LPs are participants in the announcement, not allocated owners of a specific vehicle. The amounts are sold under the filings, not an assertion about final fund size, called capital or future portfolio deployment.
Continue reading
Related Research
The Public Investors Behind White Star Capital Fund IV
White Star Capital's $250 million Fund IV spans France, Quebec and Guernsey, with Aéroports de Paris and La Caisse named as investors in public filings.
Headline's $400m Fund Is Real. Its Manager Map Is Not Yet Singular
Headline's $400m EU VIII is an active Luxembourg AIF, but CSSF and CNMV records map it to two AIFM relationships while LP economics remain undisclosed.
Titanbay's Luxembourg platform predates LFDE's €1,000 ELTIF launch
Titanbay's Luxembourg SICAV was formed months before LFDE's €1,000 ELTIF launch, putting a legal platform behind the public private-markets partnership.
Mustard Seed's €150m First Close Is Already a Deployment Vehicle
Mustard Seed + Partners says nearly €150m is closed and €55m is deployed, but public records still leave LP commitments and fund control unallocated.