
Dougs' €50m Round Hid a €185m Holdco Reorganization
Dougs' €50m AI round also rolled €185m of existing shares into a new Holdco, issued a redacted preference class and funded employee liquidity.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
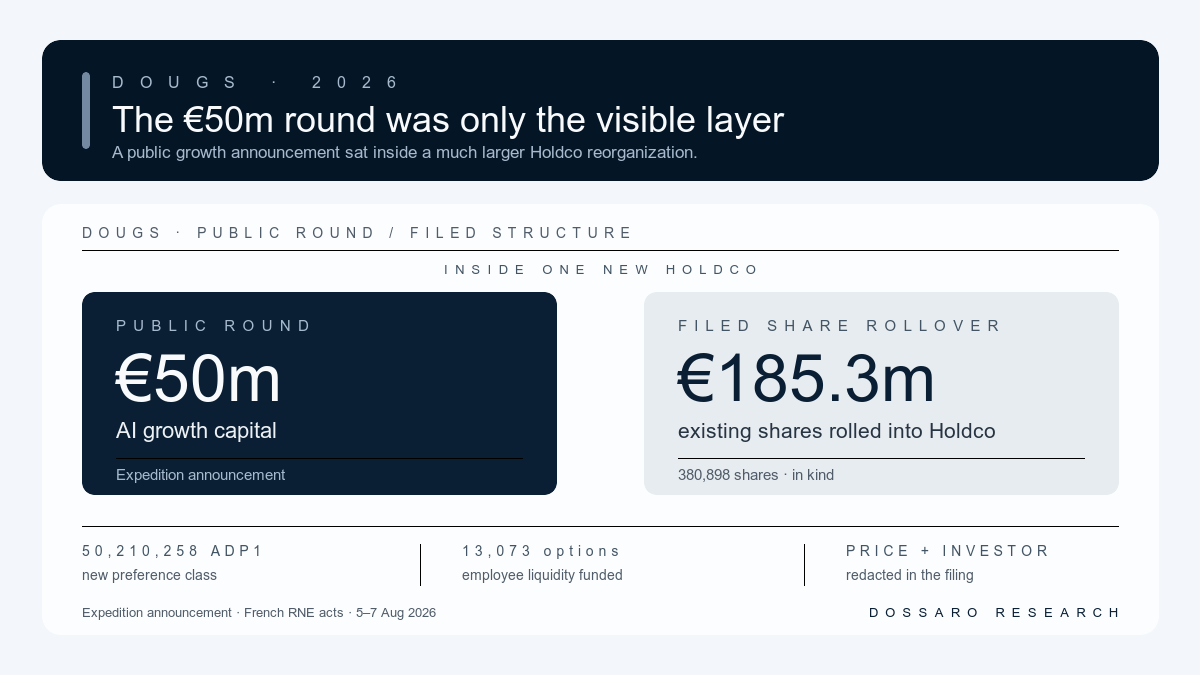
Dougs' €50 million AI investment was announced as growth capital. The filings show a larger legal event around it: founders, management vehicles and Expedition funds moved 380,898 existing Dougs Group shares into a new Holdco, valued at €185.291 million, while a separate issue created 50,210,258 ADP 1 preference shares for a cash subscriber whose identity and price are redacted.
That structure changes the commercial reading. The round was not simply a clean primary financing into an operating company. It was a rollover and liquidity architecture that put the existing shareholder base under one new holding company, created a new preference class and helped employees exercise options through an advance against their sale price. The legal documents support that sequence. They do not disclose the cash investor's exact cheque, the final voting waterfall or the allocation of any sale proceeds.
Expedition Capital described the public event as a €50 million investment to accelerate Dougs' full-stack, AI-powered accounting platform. Its announcement cites more than 50,000 clients, more than €50 million in annual recurring revenue and a plan to let AI agents take on work traditionally performed by accountants. Vestbee's independent account and Tech Funding News' report repeat the €50 million headline and the AI expansion story.
The filed structure adds the missing money-flow question: how much of the transaction was new cash, how much was existing equity rolled into a new vehicle and which rights attach to each class?
The new Holdco is doing more than holding shares
DOUGS HOLDCO was incorporated in Bron on 12 May 2026 with SIREN 104996673. Its stated purpose is to acquire and manage securities, implement group policy and provide financial and administrative support to controlled companies. Patrick Gaston Emile Maurice initially subscribed 100 shares at nominal value. The later filings name FG Consulting and Solugic as managing directors alongside Maurice as president, and they provide for a strategic committee.
That is a meaningful change in the legal centre of gravity. The operating businesses remain where clients and employees encounter Dougs, but the shareholder and financing decisions now have a new group-level home. The Holdco's updated articles also set out four classes: ordinary shares, ADP 1, ADP 2 and ADP 3. The special classes are a financing tool, not a public disclosure of who ultimately controls every vote or who receives what in an exit.
| Move | What the filed record shows | Commercial consequence |
|---|---|---|
| In-kind rollover | 380,898 Dougs Group shares valued at €185.291m were contributed to Holdco | Existing founder, management and Expedition positions were consolidated without a cash sale being shown |
| Cash preference issue | 50,210,258 ADP 1 shares were issued for cash; subscriber and issue price are redacted | A separate cash investor received a new preference class, but the public record does not show the €50m calculation or its rights |
| Employee liquidity | 10,413 BSPCE2023 and 2,660 BSA2023 were exercised; Holdco advanced the subscription price against holders' sale price | Employee participation was funded through the same transaction's liquidity mechanics |
€185m of existing equity moved before the AI expansion
The July 2026 report by MR Capital, the commissaire aux apports, is unusually clear about the in-kind leg. Six apporteurs transferred a total of 380,898 Dougs Group shares to Holdco. Easy Compta Maurice contributed 73,968 ordinary shares, FG Consulting 41,659 and Solugic 17,563. Expedition Growth Capital Alpha Limited contributed 118,924 Series A shares. Expedition Balance Co-Invest L.P. contributed 79,283 Series A and 16,501 Series B shares, while Expedition Growth Capital Beta Limited contributed 33,000 Series B shares.
The report values those shares at €185,291,453.50. It also says the value was agreed in the apport treaty and that the transaction was tested for whether the contribution was overvalued. That is an accounting and legal valuation for the share contribution. It is not a disclosed purchase price for Dougs, a cash exit for Expedition or a public valuation of the whole group.
Holdco's 5 August decision and 7 August president's report show the consideration: 108,908,404 new ordinary shares, 71,145,217 ADP 2 shares and 5,237,830 ADP 3 shares, for 185,291,451 new shares in total. The nominal share count makes the raw rollover block about 78.68% of the 235,501,809 shares shown after the separate cash issue. That percentage is only a share-count calculation. ADP rights, voting rules, liquidation preferences and any shareholders' agreement can make economic and control outcomes differ from the raw count.
This is why the word “investment” needs a qualifier. The public announcement describes new capital for AI expansion, while the legal record shows a much larger existing-equity reorganization happening at the same time. The two can be commercially linked without being the same cash flow.
The €50m cash issue is visible, but its price is not
The second leg is a cash capital increase at Holdco. The 5 August decision and 7 August president's report describe the issue of 50,210,258 new ADP 1 shares with a nominal value of €0.01 each. The documents state that the shares were to be issued at a price including a premium and that the total subscription was paid in cash, including potentially by set-off against liquid and due claims.
The public versions mask the per-share price, the total subscription amount and the subscriber's identity. The updated articles nevertheless show the resulting capital structure: 108,908,504 ordinary shares, 50,210,258 ADP 1 shares, 71,145,217 ADP 2 shares and 5,237,830 ADP 3 shares, 235,501,809 shares in all.
That makes it possible to identify a separate preference class, but not to prove that the ADP 1 issue itself was exactly €50 million. The public €50 million headline may include transaction components, and the filing's redactions prevent a price-per-share calculation. Nor does the issue count establish the cash investor's voting or liquidation share. Calling the subscriber an Expedition buyer, a majority owner or a particular fund would go beyond the evidence.
The most defensible interpretation is narrower: a cash subscriber entered the new Holdco through ADP 1 while existing Dougs and Expedition holders received ordinary, ADP 2 and ADP 3 shares for their in-kind rollover. The preference stack separates the claims even though the public announcement presents one round.
Shareholder liquidity is not a footnote
The transaction also explains why the announcement mentions shareholder liquidity. On 13 August 2026, Dougs Group recorded the exercise of 10,413 BSPCE2023 and 2,660 BSA2023, creating 13,073 new ordinary shares. The president's extract says Holdco paid the exercise price on behalf of each holder by an advance against that holder's sale price under the contract.
This is not the same as saying employees sold their shares or received a guaranteed payout. It does show the financing was designed to carry option exercise through a sale process, so employees did not have to fund the exercise entirely from cash on hand. The arrangement links compensation, cap-table expansion and liquidity at the group level.
The January 2024 option document supplies the background. It awarded BSPCE2023 and BSA2023 to employees and service providers and allowed early exercise if at least 95% of the company's shares were transferred before the normal exercise dates. The 2026 exercise therefore sits inside a pre-existing transaction trigger rather than being an isolated administrative filing.
That mechanism gives the public €50 million story a human consequence. The new capital structure was not only about institutional investors. It also created a path for employee optionholders to participate in the transaction's liquidity mechanics, while the precise cash outcome remains undisclosed.
The commercial logic is a rollover, not a clean primary round
The filings support a common private-market structure: a newly formed Holdco consolidates founder, management and existing financial-investor positions, then issues a separate preference class to a cash subscriber while the transaction funds option exercise. This can make governance, future fundraising and exit accounting easier to manage. It can also shift the most important diligence questions away from the operating company and toward the Holdco's articles and side agreements.
The structure does not prove a sale of Dougs, a change of ultimate control or a problem with the public announcement. It does show that the headline amount is not a complete map of the transaction. The Matter Machine financing analysis makes a related distinction between a financing headline and the control rights that sit beneath it; Dougs adds the separate question of how old equity and new cash were assembled in one Holdco.
For investors and employees, the next diligence step is therefore not to repeat the €50 million figure. It is to obtain the Holdco's full articles and any shareholders' agreement, identify the ADP 1 subscriber and issue price, and trace how the apport shares and employee advances are treated in a sale or liquidation waterfall. Those documents would determine whether the new preference class is mainly a financing convenience, a negotiated protection or the central control instrument of the reorganization.
Dougs' public story remains true at the level of strategy: Expedition announced €50 million for AI-led expansion. But the legal architecture says the money arrived alongside a €185.291 million rollover of existing shares and an employee-liquidity process. The changed interpretation is simple: this was a growth financing wrapped around a shareholder reorganization, not a standalone cash round that can be understood from the headline alone.
Continue reading
Related Research
Matter Machine's £4m Round Changed Founder Control At Launch
Matter Machine's £4m pre-Series A took a one-share founder company to 808,300 shares, cut the founder's PSC band and installed institutional governance.
Duralex's Rescue Also Ends Its Employee-Controlled SCOP
Duralex's €16m rescue keeps 155 jobs but replaces a worker-controlled SCOP, shifting control to Tomé and public-backed private capital in a court-selected rescue.
Foundever's Debt Rescue Gave Participating Lenders 40% of Equity
Foundever cut nearly $900m of debt, while S&P says participating lenders received 40% of equity and existing owners invested $225m as maturities moved to 2030 and 2031.
LO:TECH’s $12m Series A Sits on a Founder-Holding Company Reset
LO:TECH’s $12m Series A follows a holding-company reorganization, preferred seed classes and a Companies House control record that went blank.