
DIG's $120m Fund III Was Built Beside a New UK Investment Vehicle
DIG's $120m Fund III launched beside a new UK company whose sole shareholder is the Guernsey fund LP, while its older adviser reported £988,744 due after one year.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
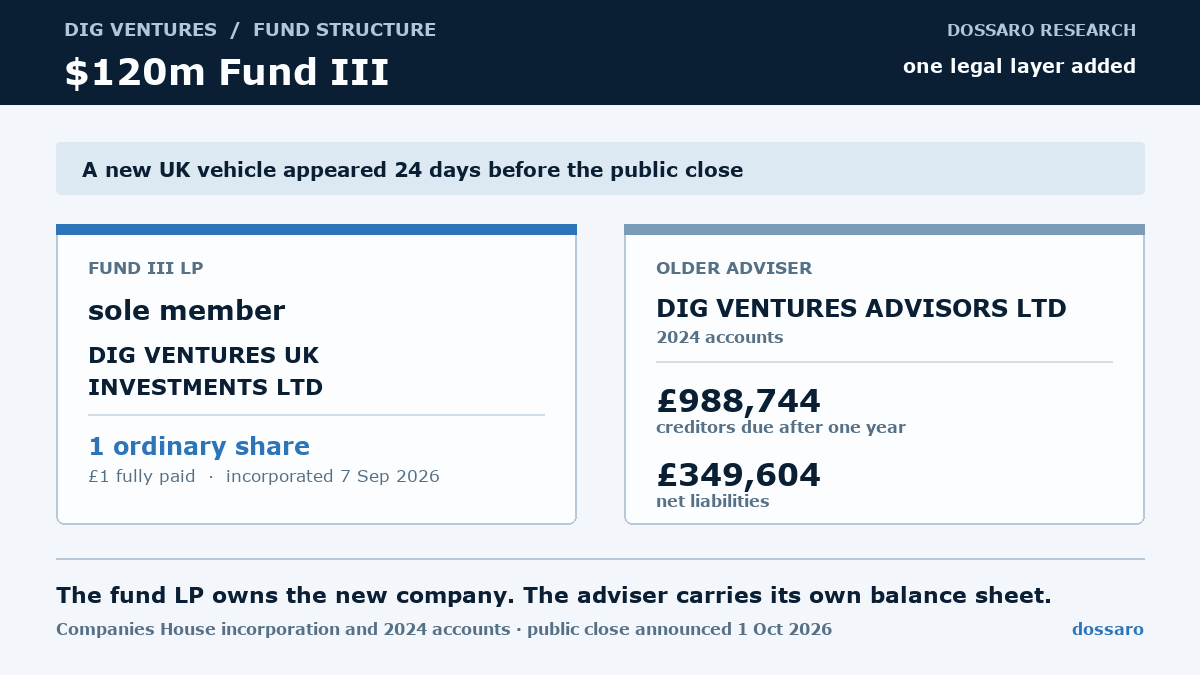
DIG Ventures announced a $120m third fund on 1 October to back about 30 European pre-seed and seed companies building AI-native enterprise and cloud infrastructure. Twenty-four days earlier, Companies House recorded a new UK company whose only subscriber was DIG Ventures Fund III LP, the Guernsey vehicle named in the fund’s public filing.
That timing makes the legal structure part of the financing story. DIG Ventures UK Investments Ltd began with one fully paid £1 ordinary share held by the fund LP. The older DIG Ventures Advisors Limited sits beside it with a different balance-sheet profile: its latest accounts report £988,744 of creditors due after more than one year and net liabilities of £349,604. A 2025 filing also registers a fixed charge over the adviser’s bank accounts in favour of HSBC Innovation Banking.
The record does not establish that the new company has already acquired Fund III assets or that the adviser manages the fund. It does establish a separation visible at launch: the fund LP is the member of a new UK investment vehicle, while the established adviser carries its own accounts, creditors and security package.
A $120m close arrived with a £1 shareholder
Tech.eu’s report says DIG closed Fund III at $120m, plans to back roughly 30 companies and has already begun deploying capital. It names limited partners including Horsley Bridge, Sofina, Granite and a US university endowment, alongside founders of Slack, Datadog, Nord Security, Cast AI, Supercell and Dash0. DIG’s own investment description places the firm at pre-seed and seed stage in business-to-business software, artificial intelligence and cloud infrastructure.
The US Form D record for DIG Ventures Fund III LP identifies the issuer as a Guernsey limited partnership. It names DIG Ventures Fund III GP Limited as the general partner and Dig Ventures Management Limited as the manager, all at the same St Peter Port address. Those roles sit at the fund level. They are not the same as the UK company that appeared on 7 September.
The public financing account is therefore larger than a single legal-entity event. The fund announcement describes commitments and strategy. The UK incorporation shows a company created alongside that close. The two records answer different questions, and combining them would make the structure look simpler than it is.
Companies House names the fund as the new vehicle’s only member
The Companies House profile for DIG Ventures UK Investments Ltd records incorporation on 7 September 2026. Its incorporation document gives the company one ordinary share with a nominal value of £1, fully paid. The subscriber and initial member is DIG Ventures Fund III LP, with the Guernsey address used in the Form D filing.
Melissa Jade Klinger and Rytis Vitkauskas are named as directors. The company’s registered office is 727-729 High Road, London, the same address used by DIG Ventures Advisors Limited. The filing states that no registerable person with significant control or relevant legal entity is recorded at incorporation. Its SIC code is 64303, a category covering trust, funds and similar financial entities.
| New UK vehicle | Filing fact | Commercial meaning |
|---|---|---|
| DIG Ventures UK Investments Ltd | Incorporated 7 September 2026 | A new company was in place 24 days before the public close |
| Share capital at incorporation | One ordinary share, £1, fully paid | The fund LP is the legal member, not a named operating-company investor |
| Initial subscriber | DIG Ventures Fund III LP, Guernsey | The vehicle is linked directly to the Fund III issuer |
| Directors | Melissa Jade Klinger and Rytis Vitkauskas | The fund’s operating leadership appears on the new UK company |
The one-share starting point is not a valuation. It says nothing about how much capital will later be invested, which portfolio companies will sit below the vehicle or whether the company will be used for every Fund III transaction. It does make the first legal link explicit. The Fund III LP did not merely announce a strategy; it subscribed for the new company’s only share.
That is the same kind of separation investors need to track in fund structures. Project Ventures’ GP and carry architecture shows why the manager, general partner and investment vehicle should not be treated as interchangeable. Here, the subscriber record adds a UK company to the chain without proving where the fund’s first assets have landed.
The older adviser carries a different balance sheet
The 2024 accounts for DIG Ventures Advisors Limited show a small UK company with a materially different financial position from the $120m fund headline. At 31 December 2024, the adviser reported £885,316 of current assets, including £562,452 of cash, against £276,308 due within one year. Creditors due after more than one year stood at £988,744, leaving net liabilities of £349,604.
The same accounts restate 2023 net liabilities at £296,565 and long-term creditors at £801,424. They report an average of four employees in 2024 and say RMAH GP Limited controls the company by owning its entire issued share capital. The accounts are the adviser’s balance sheet, not a statement of the assets or commitments of Fund III.
| DIG Ventures Advisors Limited | 2023 restated | 2024 |
|---|---|---|
| Net liabilities | £296,565 | £349,604 |
| Creditors due after one year | £801,424 | £988,744 |
| Cash at bank | £351,804 | £562,452 |
| Average employees | 3 | 4 |
The distinction matters because the adviser’s accounts could otherwise be read as a proxy for the fund’s financial capacity. They are not. The legal member of the new UK vehicle is the Guernsey Fund III LP, while the adviser’s own accounts show long-term creditors, cash and a shareholder deficit.
A separate charge registration dated 1 September 2025 names HSBC Innovation Banking as the person entitled. The filing says the charge contains fixed charges and a negative pledge over bank accounts. The underlying deed describes continuing security for present and future obligations to the bank. It does not disclose a Fund III commitment or prove that the charge relates to the new investment vehicle.
What this changes for fund diligence
For a limited partner or a co-investor, the incorporation changes the first diligence question. The relevant path is not simply “DIG Ventures owns a fund.” It is: which entity receives money, signs portfolio-company instruments and bears liabilities at each stage of deployment?
The public record gives a firm starting point. At fund level, the Form D names a Guernsey limited partnership, a general partner and a manager. At UK company level, the Fund III LP owns one fully paid share in a new investment company. At adviser level, the 2024 accounts show a separate company with £988,744 of long-term creditors and a £349,604 deficit.
That structure could have ordinary commercial explanations. A fund may use a UK subsidiary for investment administration, co-investments, tax or portfolio contracting while keeping commitments in the Guernsey partnership. An adviser may carry legacy costs, working capital or bank facilities that are unrelated to the fund. The filings make those explanations possible, but they do not choose among them.
The useful conclusion is narrower: the adviser should not be used as a balance-sheet shortcut for $120m of LP commitments, and the new company should not be treated as an operating investment platform until a filing shows assets, transactions or financing moving through it. The Restate parent and operating-company cap table illustrates the same diligence problem from a company side: a headline financing can sit across several legal entities with different obligations.
The next filing that matters
The public sources explain Fund III’s size, strategy and named backers. Companies House explains who subscribed for the new UK company and what sits on the adviser’s balance sheet. The missing bridge is operational: a later filing, charge, account or transaction record that shows what the new vehicle actually bought, financed or held.
Until that bridge appears, the safest reading is structural rather than speculative. DIG launched a $120m fund through a Guernsey limited partnership, and a new UK company was incorporated with that LP as its only member. The older adviser remains a separate company with its own creditors and bank security. The business question is no longer whether DIG has a large fund headline. It is where that capital becomes deployable assets, and which entity carries the resulting rights and liabilities.
Sources
Continue reading
Related Research
Project Ventures’ £5m Fund Splits General-Partner Vote From Carry
Project Ventures’ £5m fund gives Infra One 75%+ voting rights in the general partner while Project Ventures Consulting holds 75%+ of surplus assets.
Restate’s $20m Series A Meets a 79.552% Delaware Parent Stake
Restate's $20m Series A follows a German register snapshot where Delaware parent Restate Software held 79.552%, leaving the round's operating-company cap table unproven.
Reactive Technologies’ €19m EIB Debt Meets a £25m Preference Stack
Reactive Technologies’ €19m EIB debt is non-dilutive, but filings show £25m of Series D preference rights and an HSBC charge over IP and assets.
Auxxo's €33.3m Fund Close Shows Why LP Count Is Not Capital Control
Auxxo's €33.3m Female Catalyst Fund II closed after staged LP entries, but Berlin filings show nominal Haftsumme is not a map of capital or control.