
CarbonFarm's €7m Series A Left a Two-Tranche Equity Trail
CarbonFarm's €7m Series A left two 2026 equity tranches and €3,904.96 of capital, but public acts do not map named investors to legal positions.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
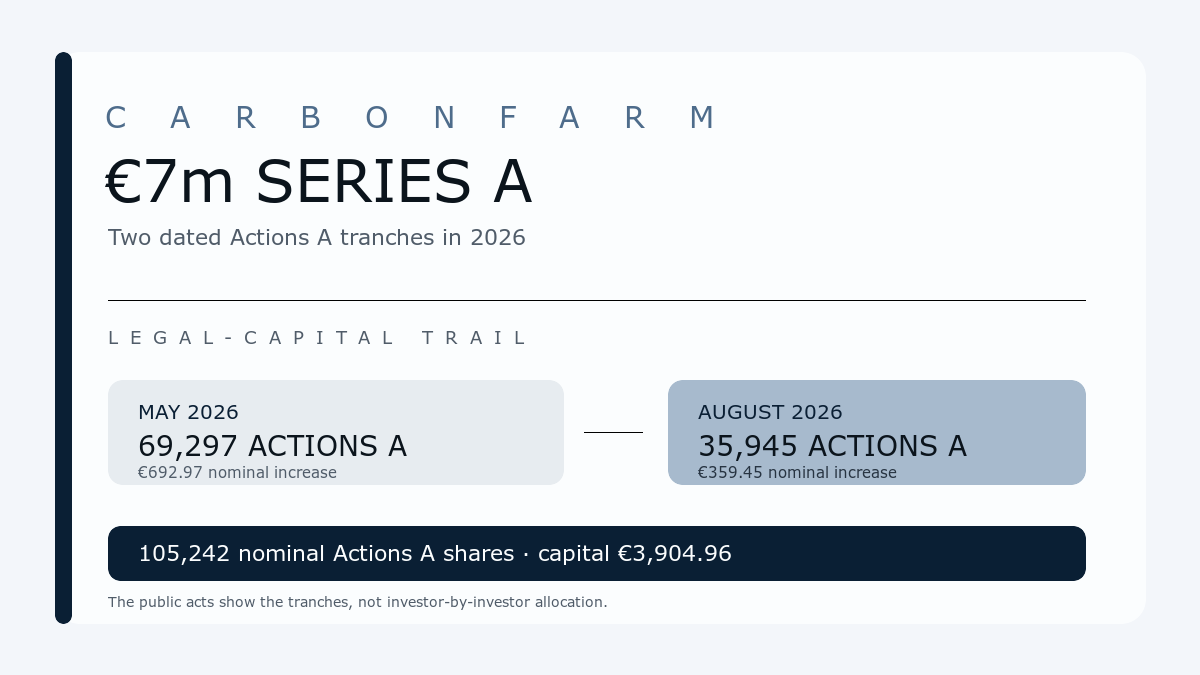
CarbonFarm announced a €7 million Series A on 13 October, led by Colam Impact with Proparco and other investors. Its French corporate filings now show what that announcement left behind in the issuer's legal capital: two 2026 Actions A tranches totalling 105,242 nominal shares and capital of €3,904.96. The filings prove that the equity trail is real. They do not show which named investor received which shares.
That distinction is the useful finding. A financing announcement identifies the commercial round and its backers. A capital act identifies an issuer, a dated increase and the legal amount added to the company's capital. CarbonFarm's public acts connect the first half of that story to the second, but not to investor-level allocations. The result is a traceable two-tranche Series A trail with an unresolved cap-table map.
The financing headline and the register trail answer different questions
Proparco's official announcement places its investment in CarbonFarm's methane-reduction work in rice farming. Sesamers' independent funding report names Colam Impact as lead and lists Proparco, Suma Capital, elea, Working Capital Fund, Albo, Bpifrance, Serena and makesense among the participants. CarbonFarm's public legal page supplies the company's own legal-structure context.
Those sources establish the announced amount, the round label and the public investor roll-call. They do not state how much equity each investor subscribed for, whether every participant subscribed at the French issuer, or whether part of the round used a separate instrument or entity. The latest RNE material answers a narrower question: what increases in CarbonFarm Technology's issued capital became definitive in 2026?
The company is CARBONFARM TECHNOLOGY, SIREN 912160389, a French société par actions simplifiée incorporated on 1 March 2022. The public profile identifies Vassily Carantino as président and James Hastwell as directeur général. Its registered capital is not the same thing as the €7 million headline. It is the nominal capital amount recorded in the issuer's statutes and capital decisions.
June added 69,297 Actions A shares
The 4 June 2026 president's decision, filed in the RNE on 9 June, records a €692.97 increase. The increase became definitive on 25 May and issued 69,297 ordinary shares labelled “Actions A” for identification, each with €0.01 nominal value. Capital moved from €2,852.54 to €3,545.51.
The act says the preference right was removed in favour of named persons and that the president reviewed subscription forms and a Société Générale deposit certificate. That language confirms a completed subscription and a bank-backed payment process. It still does not identify the subscribers or their individual allocations in the text returned by the public document parser. A named-person reservation is not the same evidence as a public allocation schedule.
The June document also carries the company's post-increase class totals: 20,000 Pre-Seed shares, 60,120 Seed shares and 69,297 Actions A shares, for 354,551 shares in total. The separate BSPCE exercise decision records a different June step: Jack Davison exercised 134 BSPCE on 24 March, adding 134 ordinary shares and €1.34 of capital. That moved capital from €2,851.20 to €2,852.54 before the Actions A tranche.
August closed a second Actions A tranche
The 2 September 2026 president's decision records the second tranche. It says the president had authorised 35,945 Actions A shares, received the subscription forms, and reviewed the depositary bank certificate. The subscription became definitive on 6 August 2026, adding €359.45 of nominal capital and taking the issuer from €3,545.51 to €3,904.96.
The two decisions therefore reconcile arithmetically:
| 2026 filing event | New shares | Nominal capital added | Capital after event |
|---|---|---|---|
| BSPCE exercise, completed 24 March | 134 ordinary shares | €1.34 | €2,852.54 |
| Actions A tranche, completed 25 May | 69,297 | €692.97 | €3,545.51 |
| Actions A tranche, completed 6 August | 35,945 | €359.45 | €3,904.96 |
| Actions A tranches combined | 105,242 | €1,052.42 | not additive |
The updated September statutes confirm €3,904.96 of capital and 390,496 ordinary shares. They also list 20,000 Pre-Seed, 60,120 Seed and 112,374 Actions A shares. The class figures add to the stated total, but the public text returned for that document is partial and does not expose the full supporting material. The acts are therefore strong evidence of the dated increases, not a complete investor register.
The legal trail is real, but the allocation remains unlinked
The key gap is not whether shares were issued. It is who received them. Both Actions A decisions refer to “persons dénommées”, subscription forms and a deposit certificate. The public text exposes the number of shares and the nominal increase, but not a subscriber-by-subscriber schedule. The investor list in the funding coverage cannot safely be mapped onto those legal positions.
That prevents several tempting calculations. The 105,242 nominal Actions A shares are not a public ownership percentage for Colam Impact, Proparco or any other participant. Nor can the €7 million announcement be divided across those shares to infer a price without knowing the issue premium, instrument terms and allocation. Nominal capital is an accounting and legal measure, not the cash proceeds of the round.
There is a second reason to avoid a neat cap-table conclusion. The September statutes' class count is internally difficult to reconcile with the June class state, while the parser returned only a 20,000-character window from a 56,759-character document. The visible text is enough to confirm the September capital amount and total shares. It is not enough to treat the returned window as a complete shareholder or preference-rights schedule.
This is the same analytical separation that matters in other private-company financings. 1KOMMA5°'s financing record separates a public funding headline from a principal-company shareholder transfer. CMR Surgical's Stryker deal shows why the instrument and preference class can matter more than an announced cheque. CarbonFarm's case adds a French issuer with visible capital increases but no public allocation bridge to the named investors.
Why the €7 million round can still be accurate
The filings do not contradict the announcement. They show the legal-capital component visible at CarbonFarm Technology, while the announcement describes the commercial financing package. The package could include issue premiums, instruments whose conversion is later, proceeds booked at a related vehicle, or non-dilutive funding alongside the equity. Sesamers' account reports that €7 million was raised and describes the operating expansion, but it does not supply the missing allocation schedule.
The safer conclusion is therefore layered. The public announcement supports a €7 million Series A and names participating investors. The RNE acts support two completed Actions A increases in 2026, totalling 105,242 nominal shares and €1,052.42 of nominal capital, plus a separate 134-share BSPCE exercise. No public act reviewed here connects a named investor to a specific share count.
For counterparties and investors, that boundary matters. The issuer has a dated capital trail that can be checked line by line, but the economic ranking of the new money remains unknown. The public record does not establish dilution by investor, preference rights, conversion terms or the cash price paid for the Actions A shares.
The next document should connect money to positions
The next useful evidence would be the complete subscription allocation, an annex to the capital decisions, a subsequent shareholder or beneficial-owner record, or a related-entity filing that identifies where the round was booked. A fuller parse of the September statutes could also resolve whether the class-count discrepancy is a presentation issue or a material change in the rights attached to Actions A.
Until that record appears, CarbonFarm's strongest public fact is affirmative: its €7 million Series A left two 2026 equity tranches in the French issuer. The unresolved question is not whether the legal trail exists. It is which investor sits behind each part of it.
Continue reading
Related Research
1KOMMA5°'s €70m Round Arrived With a Founder-to-G2VP Share Transfer
1KOMMA5° announced €70m at a $1.35bn valuation, but its latest Hamburg shareholder list still shows €74,911 capital and a 300-share founder transfer.
Stryker's CMR Surgical Bet Arrived Before Its Preferred Stack Moved
Stryker announced a $400m preferred investment in CMR Surgical, but the same-day filing recorded only 268 ordinary shares and unchanged preferred ranking.
Reverion's $175m Round Rebuilt the Ownership Map Before the Factory
Reverion's $175m Series B added 20,597 nominal shares, introduced new investment vehicles and diluted founder holdings to roughly 8-10% each.
WhiteLab's $26m Series B Followed a Parent-Debt Share Conversion
WhiteLab's French SAS was still wholly controlled by its Delaware parent after a 28,669-share debt conversion when the $26m Series B was announced.