
1KOMMA5°'s €70m Round Arrived With a Founder-to-G2VP Share Transfer
1KOMMA5° announced €70m at a $1.35bn valuation, but its latest Hamburg shareholder list still shows €74,911 capital and a 300-share founder transfer.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
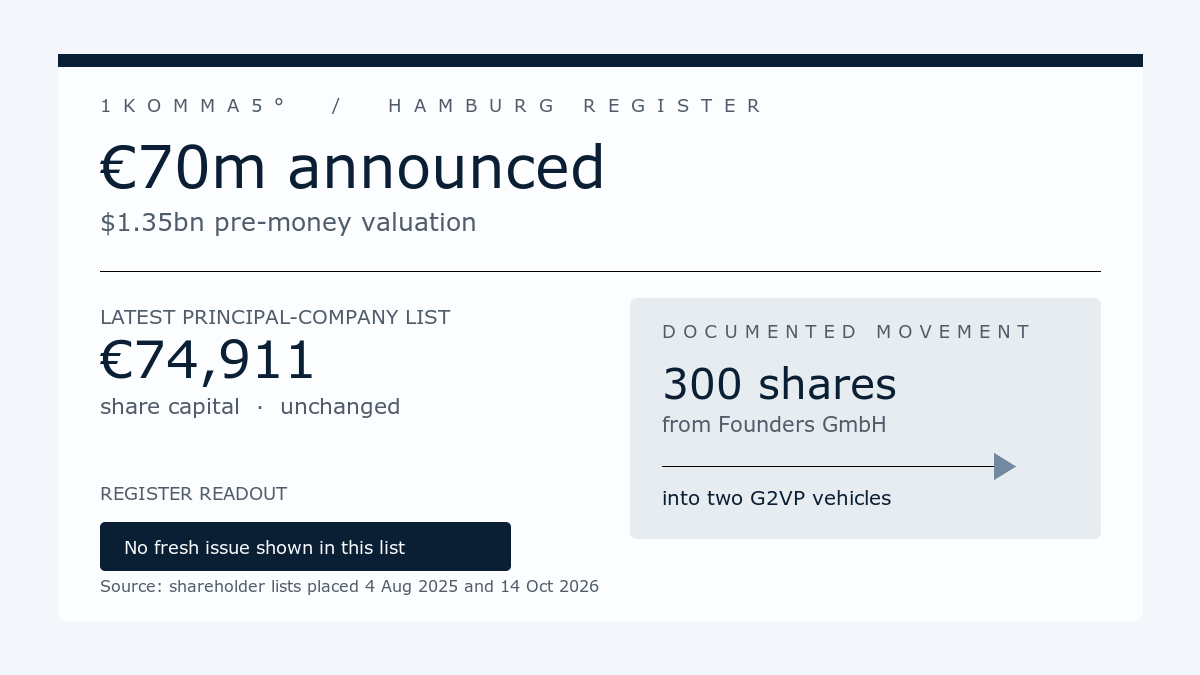
1KOMMA5° announced approximately €70 million of new financing at a $1.35 billion pre-money valuation on 13 October, alongside a plan to invest more than €100 million in its energy-intelligence product Heartbeat AI in 2027. The latest shareholder list for its principal Hamburg company tells a narrower story: legal capital remains €74,911, while 300 shares moved from Founders GmbH into two G2VP vehicles.
That is not evidence that the financing did not happen. It is evidence that the public round headline has not yet translated into a fresh issue in the principal company's visible shareholder list. For investors and counterparties, the immediate register fact is a transfer and a changed founder/G2VP position. The instrument, closing entity and dilution mechanics behind the €70 million remain open.
The announcement is larger than the legal-capital movement
1KOMMA5°'s press release says the new financing values the company at $1.35 billion before the new money, a 35% increase from its July 2025 round. It also says the company will invest more than €100 million in Heartbeat AI in 2027. Startup City Hamburg's independent account describes the €70 million round and adds that a further €35 million for the 2027 plan will come from the company's own resources. Startup.eu reports the same financing and the arrival of Japanese cleantech investor Marunouchi Innovation Partners.
The announcement answers the public questions about size, valuation and the business use of the capital. It does not, by itself, show whether the money entered 1KOMMA5° GmbH as new equity, a convertible instrument, a secondary purchase or capital at a related group entity. That distinction matters because a headline financing amount and a principal company's issued capital are different evidence layers.
The Hamburg company is the platform named in the commercial-register record. Its stated purpose covers holding and operating activities for renewable-energy and alternative-mobility subsidiaries and affiliates. The group structure therefore makes it plausible that a financing instrument could sit outside the exact entity whose shareholder list is public. Plausible is not proven, but it is the reason to keep the register finding precise.
The latest list repeats €74,911 of capital
A shareholder list placed in the register folder on 14 October, after the announcement, repeats the holder state shown in the 14 September list. The document records €74,911 of share capital. It lists Founders GmbH with 24,700 shares, or 32.9725%; G2VP II LLC with 3,666 shares, or 4.8938%; G2VP Opportunity Fund LP with 568 shares, or 0.7582%; and G2VP Opportunity Fund I Co-Invest LP with 4,826 shares, or 6.4423%.
The same list names Haniel Beteiligungs-GmbH with 8,131 shares, Porsche Investments Management SA with 4,164 shares and Eurazeo Smart City Fund II FPCI with 3,464 shares. Those positions help locate the change in the wider holder map, but they do not identify the subscriber or instrument behind the announced €70 million.
The pre-round comparison is unusually clear:
| Holder or measure | 4 August 2025 | October 2026 list | Change |
|---|---|---|---|
| Founders GmbH | 25,000 shares (33.3729%) | 24,700 (32.9725%) | -300 |
| G2VP II LLC | 3,408 (4.5494%) | 3,666 (4.8938%) | +258 |
| G2VP Opportunity Fund LP | 526 (0.7022%) | 568 (0.7582%) | +42 |
| G2VP Opportunity Fund I Co-Invest LP | 4,826 (6.4423%) | 4,826 (6.4423%) | 0 |
| Share capital | €74,911 | €74,911 | €0 |
The latest list attributes the change to notarial deed 6 August 2026, UVZ 1036/2026 B. The dates put the holder movement before the financing announcement, while the register placement came after it. Neither date turns the 300 shares into the €70 million round. They simply establish the legal sequence that is currently visible.
The 300-share delta is a transfer, not a fresh issue
The arithmetic reconciles exactly. Founders GmbH lost 300 shares. G2VP II gained 258 and G2VP Opportunity Fund LP gained 42. Together, the two G2VP vehicles gained 300 shares. Total legal capital did not move.
The list labels the shares as transferred by legal transaction. That makes the movement secondary-looking in the narrow legal sense: an existing block moved between holders rather than a new block being issued by the company. It does not establish whether consideration was paid, who negotiated it or whether the transfer was connected to the financing announcement. A transfer can be economically important without being the primary financing itself.
This is where the distinction between a valuation headline and a cap-table movement becomes useful. A new issue would normally be expected to increase the issued capital or add a documented class, although the exact mechanics depend on the instrument and jurisdiction. The list shows neither in this principal company. It shows a changed balance between Founders GmbH and G2VP vehicles, with no corresponding increase in the euro amount of capital.
Why the round can still be real
The register gap has several commercially ordinary explanations. The financing could close through a later issue that has not yet appeared in a subsequent list. It could be a convertible or another instrument whose equity conversion is deferred. It could include a secondary component that changes holder positions without increasing capital. Or it could be booked at a related entity while 1KOMMA5° GmbH remains the operating platform described in the register purpose.
The company also says that its 2027 Heartbeat AI investment will combine the round with €35 million from its own resources, according to Startup City Hamburg. That statement is compatible with a group-level funding plan, but it does not identify which legal entity receives the external money or how the money ranks against existing shareholders.
The gap therefore sets a document question, not a credibility verdict. The next filing may show a new class, a conversion, a capital increase or a new holder. A related-entity record may show that the financing was never intended to appear in the principal GmbH list. Until that evidence arrives, the safe conclusion is that the announcement and the shareholder list describe different layers of the transaction.
Investor economics remain unresolved
For Founders GmbH, the documented movement reduces its position by 300 shares and lowers its listed percentage from 33.3729% to 32.9725%. The record does not say whether that change is a sale, a reorganisation, a settlement or part of another arrangement. For G2VP, the two vehicles receive the corresponding 300 shares, with G2VP II taking the larger portion. That is a real ownership change in the list, even though it is not a €70 million issue.
For Marunouchi Innovation Partners, Haniel, Porsche Investments, Eurazeo and other holders, the central question is where the new money sits in relation to their existing positions. A pre-money valuation supplies a benchmark for a financing negotiation, but it does not reveal a holder's downside protection, conversion terms or preference position. Universal Quantum's preference-stack analysis shows why the class and instrument can matter as much as the headline amount. Reverion's equity map likewise separates the economic story from the legal entity that carries it.
The article's finding is consequently narrow but material: 1KOMMA5° has public financing momentum and a documented founder-to-G2VP transfer, while its principal-company shareholder list has not yet shown the fresh capital mechanics behind the new valuation. That leaves dilution, instrument seniority and the identity of the economic recipient unresolved.
The next document should connect financing to capital
The next useful record is a shareholder list, capital-increase filing, subscription document, conversion notice or related-entity filing that connects the announced €70 million to issued shares, a class of preferred rights, a debt instrument or a vehicle holding the round. Until then, the clearest public record is the one that can be reconciled line by line: unchanged €74,911 capital and 300 shares moving from Founders GmbH into two G2VP vehicles.
Continue reading
Related Research
Universal Quantum's $100m Round Entered a Negotiated Preference Stack
Universal Quantum's $100m Series A met existing preference, anti-dilution and participation rights, while post-round ownership remains undisclosed.
Reverion's $175m Round Rebuilt the Ownership Map Before the Factory
Reverion's $175m Series B added 20,597 nominal shares, introduced new investment vehicles and diluted founder holdings to roughly 8-10% each.
Circula Reached Personio After a Six-Year Capital Ladder, but Sale Economics Stay Hidden
Circula reached Personio after six years of filed capital increases, but the public register still does not show who held or monetized the sale.
CarbonFarm's €7m Series A Left a Two-Tranche Equity Trail
CarbonFarm's €7m Series A left two 2026 equity tranches and €3,904.96 of capital, but public acts do not map named investors to legal positions.