
BIOWEG's €30m Series A Mixes Rabo Equity With a €10.3m Grant
BIOWEG’s €30m Series A combines Rabo equity with €10.3m of NRW-linked grant funding, while its register shows Rabo Ventures B.V. at 5.16% in new shares.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
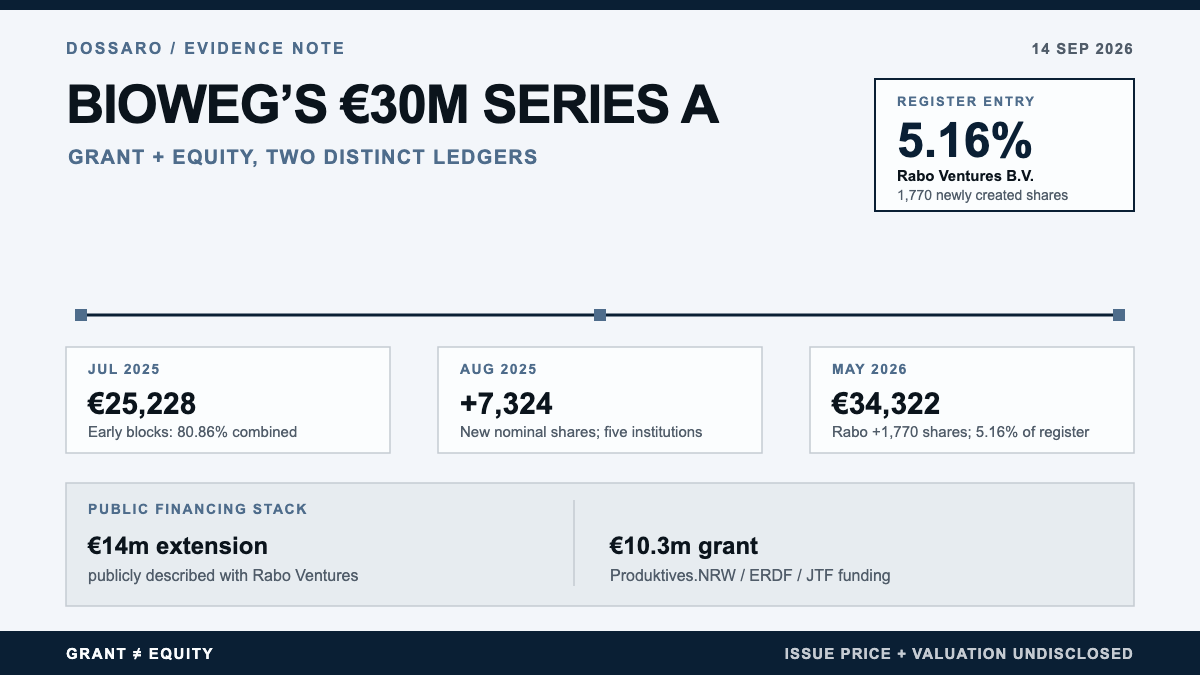
BIOWEG’s €30 million Series A is a blended financing story, not a single equity cheque. Public transaction materials describe a €14 million extension alongside €10.3 million of Produktives.NRW funding backed by the European Union. The latest shareholder list for BIOWEG GmbH, filed in May 2026, shows a separate legal equity step: Rabo Ventures B.V. entered with 1,770 newly created shares, equal to 5.16% of the register-visible capital.
That split changes the commercial reading of the round. The grant can support a capital-intensive bacterial-cellulose plant without creating another shareholder, while the Rabo issue adds a new private-equity block. The register also shows that the two largest early blocks, Srinivas Prabhakar Karuturi and Xpigmento UG, now hold 59.44% together, down from 80.86% before the 2025 institutional issuance. The records do not disclose issue prices, valuation, grant drawdown conditions or any special rights.
The €30m announcement is a mixed stack
In its transaction report, counsel Heuking says BIOWEG secured a €14 million extension of its Series A financing from Rabobank Ventures and €10.3 million in EU funding under Produktives.NRW, the North Rhine-Westphalia programme backed by the European Regional Development Fund and the Just Transition Fund. The report puts total Series A financing at €30 million and says BIOWEG plans Europe’s largest bacterial-cellulose plant, with construction scheduled for the fourth quarter of 2026 and first commercial volumes expected in 2028.
Startup.eu’s round summary repeats the €30 million total, the €14 million extension, the €10.3 million public-funding figure and the plant timetable. Both public sources put the extension and the grant side by side without publishing a legal instrument schedule. It is safer to call the headline a financing stack than to treat every euro as paid-in equity.
The legal record answers a different question. It does not show a €14 million subscription price or a €30 million capital increase. It shows nominal share capital and the holders of the shares that were filed. Connecting the public amount to the legal issue price would require the subscription deed or shareholder agreement, neither of which is in the evidence used here.
BIOWEG’s early register starts with three equal blocks
The register folder for Osnabrück HRB 215534 begins with a 12 November 2020 shareholder list for Cellulosic Technologies UG, the entity name printed in that historical record. The list records €300 of capital and three 100-share blocks for Karuturi, Dr Yogesh Sonavane and Xpigmento UG. Each block is roughly one third of the capital. Dr Frank Jenner and Markus Baum appear in the next December list, when capital is shown at €371 and the printed percentages are about 27%, 27%, 27%, 17.8% and 1.2% respectively.
The 2 May 2022 list still shows 371 shares. Karuturi and Xpigmento each have 150 shares, printed at 40.43%, while Jenner has 66 and Baum has five. The Karuturi and Xpigmento rows carry Abtretung transfer marks, and Sonavane is no longer listed. The available list does not identify the transferor, consideration or deed terms. It supports a change in the legal holder set, not a claim about why the change occurred or what anyone was paid.
The 2025 issue built an institutional layer
By 29 July 2025, the list is headed BIOWEG UG and shows €25,228 of capital. Karuturi and Xpigmento each hold 10,200 shares, or 40.4313%. Jenner holds 4,488 shares, or 17.7897%, and Baum holds 340, or 1.3477%. The two large blocks therefore total 20,400 shares, or 80.86% of the register-visible capital.
The 7 August 2025 list raises capital to €32,552 and labels the new investor rows as created through a capital increase. The arithmetic is clear even though the subscription terms are not: 32,552 minus 25,228 equals 7,324 additional nominal shares. Ginkgo Bioworks, AXELEO GREEN TECH INDUSTRY 1, BonVenture IV, EIC Fund and NBank Capital together hold 7,302 of those shares. Their combined position is 22.43% of the August list. Jenner’s line also includes 22 newly created shares, accounting for the small remainder.
| Checkpoint | Register-visible change |
|---|---|
| July 2025 | €25,228 capital; Karuturi and Xpigmento 80.86% combined |
| August 2025 | €32,552; 7,324 nominal shares added; five institutions entered |
| May 2026 | €34,322; Rabo Ventures B.V. added 1,770 shares (5.16%) |
The labels establish primary capital increases, but they do not establish how much cash was paid above the €1 nominal value. Nominal capital is a legal denominator, not a funding total.
Rabo’s 1,770 shares are a legal entry, not a €14m price
The 26 May 2026 shareholder list is the clearest bridge between the public Rabo story and the company’s legal structure. It records Rabo Ventures B.V., based in Utrecht and identified with Dutch Chamber of Commerce number 34285559, at 1,770 shares. The list says those shares were newly created through a management decision dated 15 May 2026. Total capital is €34,322, so 1,770 divided by 34,322 equals 5.157%, or 5.16% rounded.
Existing shares before this issue total 32,552, which is 94.84% of the May denominator. The list does not name a seller, and no Rabo position is shown in the August 2025 list. That is consistent with a primary issue into the company rather than a disclosed secondary transfer. It still does not prove the price paid, whether the shares are preferred, or whether Rabo has board or veto rights.
The legal holder name is more precise than the public brand label. Heuking and BIOWEG use “Rabobank Ventures”, while the list names Rabo Ventures B.V. The names are economically consistent, but this record alone does not prove the corporate relationship beyond the registered holder shown in the list.
The early blocks remain a majority, but much thinner
Karuturi and Xpigmento each remain at 10,200 shares in the July 2025, August 2025 and May 2026 lists. Their percentages fall because the denominator grows. Together they move from 20,400 of 25,228 shares, or 80.86%, to 20,400 of 32,552, or 62.67%, and then to 20,400 of 34,322, or 59.44% after the Rabo issue.
That is a dilution observation, not a control conclusion. A majority share-count block can coexist with special voting rights, shareholder agreements or board arrangements that are not printed in a shareholder list. Conversely, the list gives no evidence that either early holder sold shares during the 2025 or 2026 capital increases. The visible changes are new nominal shares and, in 2022, historical transfer marks with unknown terms.
A grant-supported plant carries a different risk map
BIOWEG says it is developing biobased organic acids, polymers and formulations and plans a bacterial-cellulose plant in North Rhine-Westphalia. The announced timetable places construction in Q4 2026 and first commercial volumes in 2028. For a project with industrial build-out risk, a public grant and private equity do different jobs. The grant can reduce the private capital required for construction, while the Rabo issue brings a new investor into the legal equity base.
The mixed stack also limits what a headline comparison can show. A €10.3 million grant is not a shareholder return and should not be added to an investor’s ownership stake. The 5.16% Rabo position is a register percentage and should not be multiplied by €30 million to estimate a valuation. The register does not publish the grant award, payment milestones, issue price, liquidation preference, board rights or any instrument outside the ordinary share list.
This distinction is central to Ethris’s financing stack, where public and private capital also answer different risk questions. Allogenetics’s NBank analysis shows why a named public investor becomes more informative when its legal share block is visible. In BIOWEG’s case, the register makes the Rabo entry visible, but it leaves the economic terms open.
The next filing should connect the two ledgers
BIOWEG’s €30 million Series A is supported as a public financing event by the Heuking report and Startup.eu. The May 2026 German shareholder list adds a new fact: Rabo Ventures B.V. appears with 1,770 newly created shares, equal to 5.16% of the nominal capital. Earlier lists show how the institutional layer arrived in 2025 and how the two largest early blocks fell below 60% after successive issues.
The strongest conclusion is narrow. BIOWEG is financing an industrial scale-up with a blended public/private stack, and the legal register shows a discrete Rabo equity entry rather than a €14 million price tag. The documents do not establish valuation, cash proceeds, grant disbursement, governance rights or the percentage of the €30 million headline represented by ordinary equity.
The next document to watch is the subscription or capital-increase deed behind the 15 May 2026 management decision, together with any grant award and later shareholder list. Those records could disclose issue price, share class, payment conditions or post-round changes. Until then, the defensible map is €30 million of announced Series A financing above a €34,322 nominal register, with Rabo at 5.16% and the two early blocks at 59.44% combined.
Continue reading
Related Research
Adaptyv's $40m Series A Sits Above a Parent-Owned Swiss Lab
Adaptyv announced a $40m Series A, while its Swiss Sàrl record shows a US-parent-owned launch and no public post-round investor split or dilution map.
Ethris's €30m EIB Debt Followed a 2.7% Gates Equity Step
Ethris secured €30m of EIB venture debt after a 2,723-share Gates Foundation capital increase diluted existing holders by about 2.7% in the latest July list.
Fundcraft's €12m Growth Financing Sat Beside a €1.24m Internal Capital Conversion
Fundcraft announced €12m of group growth financing while its French AIFM converted €1.24m of shareholder debt into capital without a cash remittance.
Allogenetics’ €3.8m Round Sits Beside NBank’s 5.78% to 17.32% Shift
Allogenetics’ €3.8m Pre-Series A coincided with NBank Capital rising from 5.78% to 17.32% and the founder falling to 23.05%. The register shows dilution, not price.