
Ontinue Sale Follows Quorum's £93.8m Topco Equity and £27m Debt
EQT is selling Ontinue to Quorum, while filings show a 2024 sponsor control transfer, £93.8m of topco equity and £27m of secured debt behind the platform.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
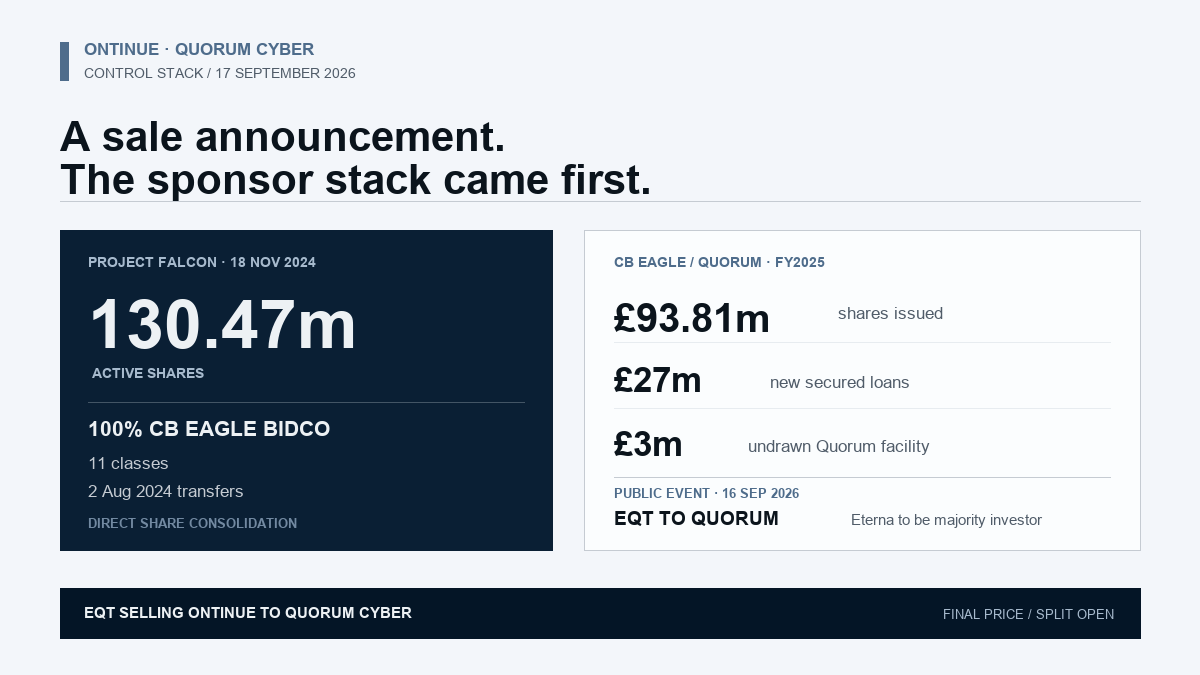
EQT's 16 September 2026 announcement that it will sell Ontinue to Quorum Cyber looks like a fresh cybersecurity combination. The filings show it is also the next step on top of a sponsor-backed control and financing stack assembled earlier.
The public releases do not disclose a price or a final ownership split. They do say that Eterna Growth Partners, Quorum's current majority investor, is expected to be the majority investor in the combined company after customary closing conditions. Behind that statement, Project Falcon Topco's November 2024 confirmation statement records 130,469,711 active shares across 11 classes, all held by CB Eagle Bidco. CB Eagle Topco's FY2025 accounts then show £93.81 million of shares issued and £27 million of secured loans.
Those figures do not add up to a sale price. They map how a sponsor-backed platform was capitalised before the Ontinue transaction. The economic question is therefore not simply what EQT is selling. It is how much of the existing control, equity and debt architecture carries into the proposed combination, and which parts remain undisclosed.
| Date | Public or filed event | What it establishes |
|---|---|---|
| 3 June 2024 | CB Eagle subsidiaries complete the Project Falcon transaction | Charlesbank-backed sponsor structure acquires 100% of Project Falcon Topco's Quorum platform |
| 2 August 2024 | Project Falcon holder transfers | Former financial and management holders transfer their direct shares to CB Eagle Bidco |
| 18 November 2024 | Project Falcon confirmation statement | 130,469,711 active shares across 11 classes are held by CB Eagle Bidco |
| FY2025 accounts | CB Eagle Topco capital and debt lines | £93.81m shares issued and £27m secured loans are visible at the holding company |
| 16 September 2026 | EQT sale announcement | Ontinue is to be sold to Quorum; Eterna is named as majority investor of the combined company |
The public deal is a sponsor handover, not a disclosed exit value
EQT's announcement describes Ontinue as an AI-powered managed extended detection and response provider focused on the Microsoft ecosystem. It says the business was carved out of Open Systems in 2023, consolidated three technology platforms, strengthened its leadership and made three add-on acquisitions. Ontinue serves more than 250 customers across Europe and the United States, according to the release.
Ontinue and Quorum's joint announcement gives the transaction its legal and ownership boundaries. The businesses will continue to operate independently until closing. The combination remains subject to customary closing conditions and any required approvals. Eterna Growth Partners is described as Quorum's current majority investor and the majority investor of the combined company. Financial terms were not disclosed.
That language describes a signed agreement and an intended post-closing investor position, not a completed merger or an exact percentage. It leaves open whether Quorum investors roll into the new structure, whether Ontinue investors receive cash or equity, and how the combined board will be constituted.
The strategic logic is clear even without a price. Quorum brings a Microsoft-centric platform with North American expansion experience; Ontinue brings an AI-native managed detection and response platform built as a standalone organisation after its carve-out. The combination would join those capabilities while moving the sponsor centre of gravity from EQT's Ontinue ownership toward Eterna's Quorum platform.
Project Falcon shows where Quorum's direct control moved in 2024
The exact legal entity behind the share-consolidation evidence is Project Falcon Topco Limited, Companies House number 13754832. Its 18 November 2024 confirmation statement lists 11 share classes. The active blocks are:
| Share class | Active shares at 18 Nov 2024 |
|---|---|
| A ordinary | 51,935,700 |
| A1 ordinary | 8,888,891 |
| A2 ordinary | 3,187,500 |
| A3 ordinary | 1,180,300 |
| B ordinary | 4,439,600 |
| B preferred ordinary | 1,000,000 |
| C ordinary | 20,841,200 |
| D ordinary | 3,194,700 |
| E ordinary | 8,352,800 |
| F ordinary | 4,471,520 |
| Ordinary preferred | 22,977,500 |
| Total | 130,469,711 |
The total is a count of issued shares, not a valuation. The filing shows CB Eagle Bidco Limited as the active holder of every block. It also marks the former Golding, Livingbridge, Maven, Scottish Enterprise, founder and management entries as transferred on 2 August 2024 to zero.
That is strong evidence of direct-share consolidation, not proof that every former holder lost economic exposure at a higher holding company. A rollover, parent-level instrument or separate contractual claim could sit above the company named in the statement, and the public record does not disclose those arrangements.
The Livingbridge account of its partial realisation and a 2025 CRN interview provide independent context for the filing. CRN reports that Charlesbank became Quorum's majority investor in 2024 while Livingbridge became a minority shareholder, then describes the Difenda and Kivu acquisitions that followed. The register adds the legal holder map that the interview does not show.
CB Eagle's £93.81m equity line is not the purchase price
The exact holding company is CB Eagle Topco Limited, Companies House number 15576886. Its accounts for the period ended 31 May 2025 report £93,810,998 of shares issued and £93,810,994 of share premium. The same accounts show £27 million of secured loans.
| CB Eagle Topco FY2025 line | Reported amount | How to read it |
|---|---|---|
| Shares issued | £93,810,998 | Equity-accounting line at the holding company |
| Share premium | £93,810,994 | Premium recorded above nominal share capital |
| Secured loans | £27,000,000 | Debt secured against the sponsor-backed structure |
The shares-issued and share-premium lines together total £187,621,992 of equity-accounting entries. That arithmetic does not mean the company received that amount in cash in the 2024 transaction, and it does not identify what any seller received. Likewise, adding the £27 million loans to the £93.81 million shares-issued line produces £120.81 million only as a cross-line comparison. It is not a disclosed enterprise value, financing total or sale consideration.
The accounting lines still change the commercial reading of the announcement. A buyer taking Quorum into a new combination is working with an equity-funded holding structure and a secured debt layer, rather than an unlevered operating company. The debt may support acquisitions and growth, while the equity line records capitalisation at a sponsor vehicle. Neither line reveals the price EQT agreed with Quorum for Ontinue.
The operating company carries acquisition and refinancing exposure
Quorum Cyber Security Limited, the Scottish operating company behind the platform, reported group revenue of £31.837 million and a loss after tax of £15.459 million in its FY2025 accounts. Net assets were £9.843 million and cash was £9.168 million. The accounts also describe a £3 million undrawn facility, 340 staff, the Difenda and Kivu acquisitions, and a CIBC facility that replaced convertible notes.
Those numbers should not be turned into a distress narrative. CRN's independent reporting says Charlesbank invested to give Quorum more firepower for North American expansion and that the two acquisitions followed quickly. The filings show the cost of that strategy in the operating perimeter: revenue scale increased, but the group also carried losses, acquisition integration work and external debt.
The proposed combination therefore creates a test for the new majority investor. Quorum and Ontinue can offer customers a wider Microsoft security footprint and more AI-enabled delivery capacity, but the combined company must integrate two operating models while retaining specialist staff and servicing the debt layer. The announcement does not disclose integration capital or loan covenants.
Ontinue's own accounts show a carved-out parent chain
The UK legal entity Ontinue UK Ltd, Companies House number 11713129, provides the target-side balance-sheet context. Its 2024 accounts identify Ontinue AG as the immediate parent and EQT Mid Market Europe as the ultimate parent. They report fixed-asset investments of £12,676,692, a capital-contribution reserve of £11,404,649 and net assets of £12,871,997.
Those are markers of the carve-out structure, not a valuation. Neither line answers how the 2026 sale will allocate proceeds between EQT, management and any rollover investors.
Eterna's majority position remains the unresolved control event
The filings establish the historical stack. Project Falcon's direct shares were consolidated under CB Eagle Bidco in August 2024. CB Eagle Topco carried a large equity-accounting base and secured loans in FY2025. Quorum's operating company carried acquisition exposure and an external refinancing. Ontinue remained in an EQT parent chain.
The public deal announcement establishes the intended next step. Eterna is expected to be the majority investor in the combined company, but neither the buyer nor the seller publishes a final percentage, issue price, rollover ratio or consideration split. The combination could preserve more of the Quorum sponsor group above the operating companies than the Project Falcon direct-share record suggests. It could also give Ontinue stakeholders equity in a new parent rather than a cash exit. The public evidence cannot distinguish those outcomes.
That is the practical diligence question for customers, lenders and former shareholders. Customers need to know whether service continuity and investment capacity survive integration. Lenders need to understand whether the combined perimeter changes collateral, guarantees or leverage. Former holders need a completion filing or transaction disclosure before anyone can calculate recovery.
The structure resembles the layered capital questions in Open Cosmos' preferred financing and the sponsor-led sequencing in Beckett's buy-and-build: the public headline identifies the event, while the legal entities and capital lines show who bears risk at each layer. In Ontinue and Quorum's case, the headline is a sale. The evidence underneath is a sponsor transition built on a documented share consolidation, equity stack and debt package.
Evidence boundary and next-document watchpoint
The high-confidence findings are the 16 September agreement, the no-terms-disclosed qualifier, Eterna's stated majority-investor role, Project Falcon's 130,469,711 active shares across 11 classes, CB Eagle Bidco's direct holding, CB Eagle Topco's £93.81 million shares-issued line and £27 million secured loans, and Quorum's FY2025 operating figures.
The evidence does not establish a sale price, valuation, final ownership percentage, founder or management recovery, individual investor proceeds, current beneficial ownership, debt distress or a completed merger. It also does not prove that every former Project Falcon holder fully exited the higher-level sponsor structure.
The next decision-changing documents are a completion announcement, updated shareholder or PSC filings for Quorum and the CB Eagle / Project Falcon chain, and any transaction document that identifies consideration or rollover. Until those records appear, the defensible conclusion is narrow: EQT's sale announcement sits on a Quorum platform whose 2024 control transfer and 2025 capital stack are visible, while the economic terms of the new sponsor handover remain open.
Continue reading
Related Research
Open Cosmos' Founder Held About 41% Before Its €300m Round
Open Cosmos' €300m round sits above a register where founder Rafael Jorda held about 41% of stated capital and preferred shares ranked ahead of ordinary.
WestBridge Is Buying Beckett After Pre-Tax Profit Roughly Doubled
WestBridge is buying Beckett after filings showed £13.1m of turnover and pre-tax profit roughly doubled across Foresight's acquisition-led build-up.
Foundever's Debt Rescue Gave Participating Lenders 40% of Equity
Foundever cut nearly $900m of debt, while S&P says participating lenders received 40% of equity and existing owners invested $225m as maturities moved to 2030 and 2031.
Hackuity's $19m Round Carries a 243,860-Share Ratchet
Hackuity's $19m round includes a €7m cash tranche, a bond conversion and a ratchet ceiling that could add 243,860 shares to the capital structure.