
Hadrian's $40m Round Leaves a 399,057-Option Question at the Dutch Parent
Hadrian's $40m round sits at a Dutch parent while UK accounts show 399,057 outstanding employee options, exposing a future-value claim absent from the announcement.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
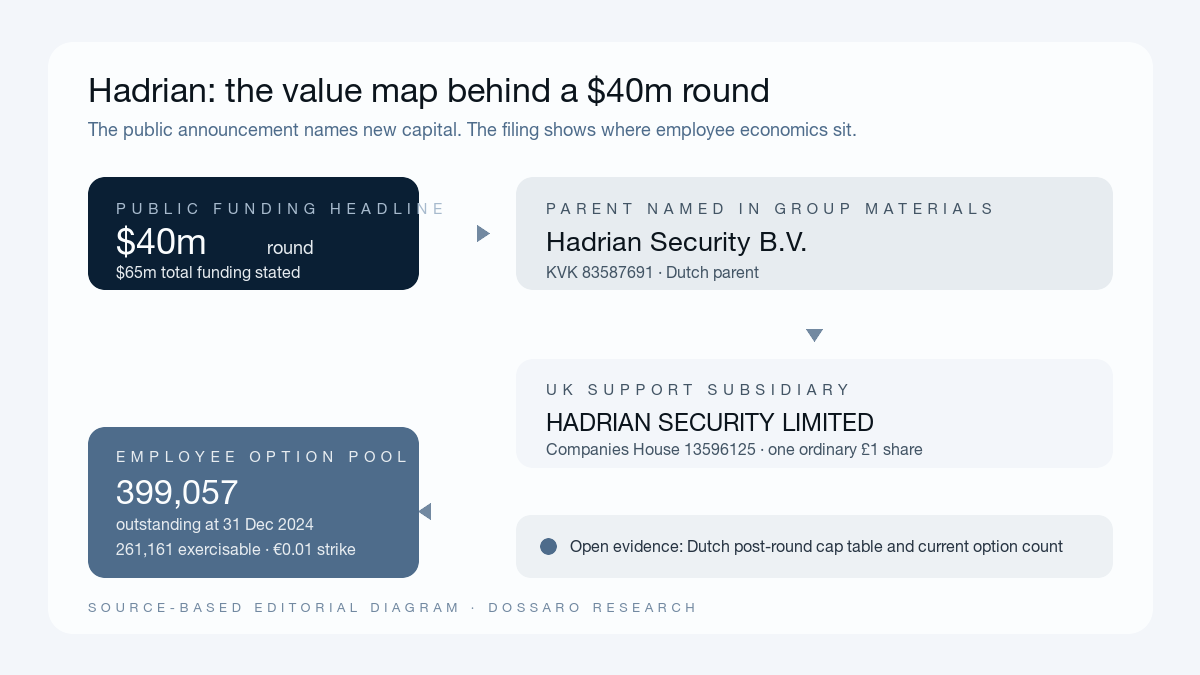
Hadrian's $40 million funding announcement identifies the investors and the market urgency. Its latest UK accounts identify a different part of the economic story: 399,057 employee options were outstanding at the Dutch parent at the end of 2024, and 261,161 were already exercisable. The filing does not connect those options to the October round, but it shows that a sizeable potential claim on future value sits below the headline financing.
Hadrian said on 6 October 2026 that Forgepoint Capital International and SmartFin co-led the round, taking total funding to $65 million. HV Capital, Motive Partners, Picus Capital and Oetker Ventures also participated. The company plans to expand across Europe and the United States and to invest more in its engineering and research teams. Sifted's independent account describes the same round and the company's agentic offensive-security platform.
The public story is therefore straightforward: new capital is backing a cybersecurity company as AI makes automated attacks more capable. The filed story is more specific. Hadrian Security B.V. is the Dutch parent named in the group's legal materials, while HADRIAN SECURITY LIMITED in the UK is a wholly owned, one-share business-support subsidiary. The UK company reports the parent-level option plan and the intercompany balance, not a separate UK equity raise.
The round announcement and the legal group are not the same map
Hadrian's official announcement says the $40 million round brings cumulative funding to $65 million. It names Forgepoint, SmartFin and four existing investors, but it does not specify the issuer, securities, issue price, share classes or investor percentages. SmartFin's release repeats the amount and the expansion plan.
Hadrian's terms identify Hadrian Security B.V. as the contracting company and refer to its affiliates. Its privacy notice identifies the Dutch entity with KVK number 83587691. Those public pages establish the parent context, but they do not publish a cap table for the Dutch company.
The UK register supplies the other side of the boundary. The Companies House record records HADRIAN SECURITY LIMITED, company number 13596125, as active and incorporated on 1 September 2021. Its filing history includes the 2024 accounts, which describe it as a business-support subsidiary wholly owned by Hadrian Security B.V. The company has one ordinary share with a nominal value of £1. That is a legal ownership fact about the support company, not a measure of the group valuation or the round proceeds.
| Filed group fact | What it establishes | What it does not establish |
|---|---|---|
| Hadrian Security B.V. is the ultimate parent named in the UK accounts | The financing question belongs at parent level unless another issuer is disclosed | The Dutch parent’s post-round share count or investor percentages |
| HADRIAN SECURITY LIMITED has one ordinary £1 share | The UK company is a wholly owned support subsidiary | That the $40m was invested into the UK company |
| UK directors are Maurice Clin and Rogier Fischer | The operating support company has a documented management link to Hadrian’s founders | A current group-wide board or voting agreement |
| UK accounts show group support for going concern | The subsidiary relies on the wider group’s financial backing | A conclusion about distress, solvency or the round’s use of proceeds |
That separation matters because a reader can otherwise treat the visible UK filing as if it were the financing company. It is not. The public round is announced by Hadrian as a group, while the UK filing documents the support entity and reports an option plan granted by the Dutch parent.
399,057 options make employee economics visible
The option schedule is the most concrete new evidence in the filing. Hadrian Security B.V. granted the options, and the UK accounts disclose the group exposure as part of the employee share-based-payment note.
| Option schedule | Shares |
|---|---|
| Outstanding at the start of 2024 | 261,237 |
| Granted during 2024 | 161,436 |
| Forfeited during 2024 | (23,616) |
| Exercised during 2024 | 0 |
| Outstanding at 31 December 2024 | 399,057 |
| Of which exercisable | 261,161 |
The arithmetic is disclosed in the accounts: 261,237 plus 161,436 minus 23,616 leaves 399,057. More than 65% of the outstanding pool was exercisable by year-end 2024. The stated strike price was €0.01. The accounts also give valuation points of €0.80 on 1 October 2022 and €1.96 on 5 December 2023, and record a 2024 option expense of £126,716.
Those values are useful context, not a current mark-to-market calculation. They are historical valuation points, and the accounts do not disclose the current fair value, individual grants, vesting schedules or the post-2024 status of the plan. They also do not say that the 2024 grants were part of the 2026 financing.
The human consequence is nevertheless clear. Employees are not just a headcount line in this financing story. A pool of 399,057 options creates potential future participation in parent-company value, subject to vesting, exercise, leaver rules, tax and the terms of the underlying shares. The filing does not identify which employees hold the options or what percentage of the Dutch parent they represent on a fully diluted basis. It is therefore not safe to translate the count into a dilution percentage.
The subsidiary’s balance sheet shows where support is flowing
The UK accounts also show the group relationship in cash terms. At 31 December 2024, Hadrian Security B.V. owed the UK subsidiary £158,150. A year earlier, associates owed £24,799. The UK company held £159,611 of cash and reported that the group would continue to support it so that it could meet liabilities as they fell due.
This is not evidence that the subsidiary received the $40 million. It is evidence that the UK company was funded and supported within a group whose parent sits in the Netherlands. The intercompany balance could reflect ordinary cost sharing, payroll or service arrangements. Without the Dutch parent accounts or the financing documents, the direction and purpose of every cash movement cannot be reconstructed.
The distinction is similar to the one in Restate's Series A structure: a financing headline can be economically important while the legal entity visible in a local register remains an operating company whose cap table does not change. North Data's 80% sale shows the opposite pattern, where a dated shareholder list exposes a direct control transfer. Hadrian's current evidence sits between those cases. The group perimeter is clear, but the parent transaction is not filed in an accessible Dutch cap table.
What the filing says about the $40m, and what it does not
The option schedule should not be used to claim that employees were diluted by the October round. The grants disclosed in the 2024 accounts predate the announcement, and the documents do not link them. Nor should the 399,057 count be added to the $65 million total funding figure. Options are a potential equity instrument, not cash raised.
The evidence supports four narrower findings:
- The public financing is a $40 million round co-led by Forgepoint Capital International and SmartFin, taking stated total funding to $65 million.
- The group’s legal materials identify Hadrian Security B.V. as the Dutch parent, while the UK company is a wholly owned one-share support subsidiary.
- The UK accounts report 399,057 outstanding parent-granted options at 31 December 2024, including 261,161 exercisable options at a stated €0.01 strike price.
- The available evidence does not disclose the Dutch parent’s post-round cap table, issue price, share classes, investor percentages or the current option count.
This is why the option count matters even without a dilution calculation. It identifies a claimant class whose economics can sit alongside the venture investors and founders, while the public announcement focuses on capital and growth. The option holders’ upside depends on the value and terms of the parent securities, not on the nominal £1 share in the UK support company.
The next document that could change the reading
The decision-changing watchpoint is a Dutch parent filing or financing document that discloses the October 2026 issuance. A Dutch annual account, shareholder register, option-plan update or investor agreement could show whether the round was primary equity, a convertible instrument or another security; whether the option pool was refreshed; and how the investor and employee claims rank.
Until that evidence appears, the defensible reading is deliberately bounded. Hadrian has raised $40 million for an agentic cybersecurity platform, but the legal issuer and new investor economics are not public in the available register path. The UK filing does show a wholly owned support company, a parent-level option plan and 399,057 outstanding options. That is enough to change the question from “who led Hadrian’s round?” to “which parent-level claims now sit ahead of the value employees and investors hope to share?”
Continue reading
Related Research
Wiener Börse's 80% North Data Deal Was an Existing-Share Transfer
North Data's latest shareholder list shows Wiener Börse took 80% through existing shares, while founder Frank Debatin kept 20% and two 30% blocks exited.
Wiremind's €35m Round Meets a Filed Founder-Control Architecture
Wiremind's €35m first financing says founders keep control. June statutes show how voting seats and quorum rules make that claim legally meaningful.
Restate’s $20m Series A Meets a 79.552% Delaware Parent Stake
Restate's $20m Series A follows a German register snapshot where Delaware parent Restate Software held 79.552%, leaving the round's operating-company cap table unproven.
Inbolt's €11m Round Put Voting Control on a Separate Track
Inbolt's €11m round came with only 1,700 net new shares, 65,495 non-voting shares and a BNP-specific 4.99% voting threshold in its statutes.