
Kuro's €10m Round Has A Visible Shareholder Map
Kuro announced a €10m UVC-led round, while its May register filing maps UVC, Foundamental, Realyze and helloworld holdings without revealing cash terms.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
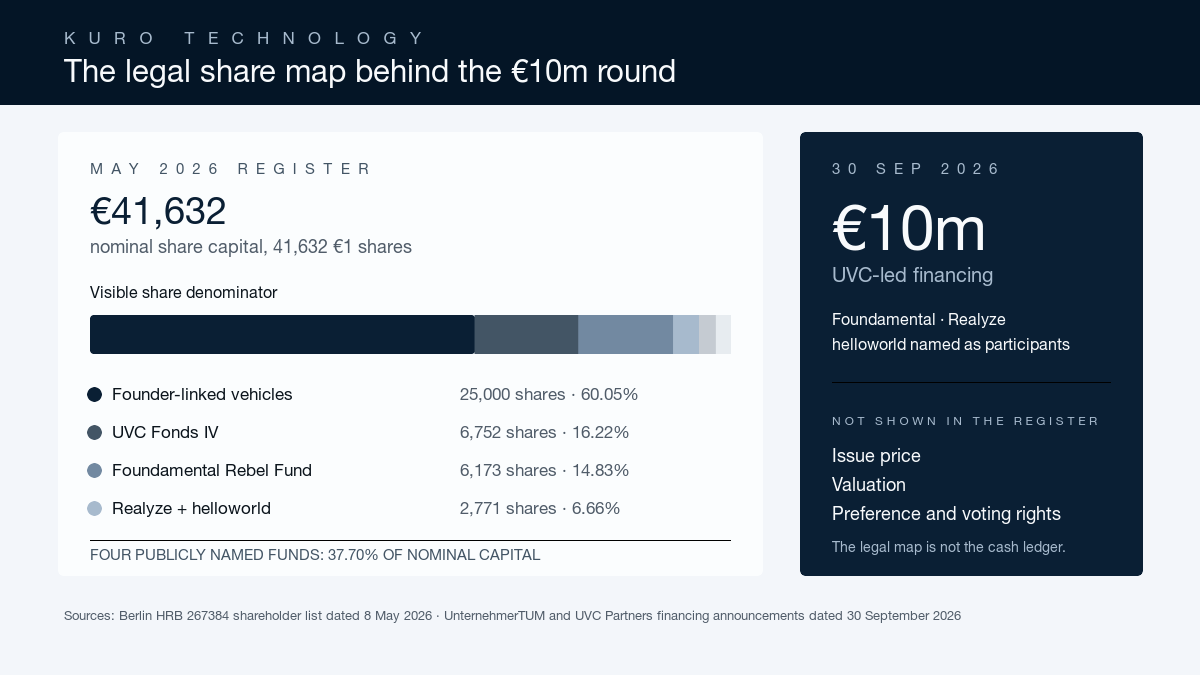
Kuro's €10 million financing headline now has a visible legal share map. A German shareholder list recorded in May gives UVC Fonds IV 16.2183% of the company's nominal share capital, Foundamental Rebel Fund 14.8275%, Realyze Ventures 4.0546% and HelloWorld Venture Capital Fund I 2.6014%. Two founder-linked vehicles still hold 60.05% together.
The map is unusually concrete for a financing announced only on 30 September. It is also easy to misread. Kuro Technology GmbH's register shows €41,632 of nominal capital, represented by €1 shares. That is the legal denominator after a capital increase, not the €10 million of cash announced by the company and its lead investor. The public record shows who holds the listed shares, but not the price paid above nominal value, the valuation or the rights attached to them.
That distinction is the useful finding. Kuro's announcement answers how much capital the company says it raised and which funds took part. The shareholder list answers which legal holders occupy the share register after a May capital increase. The names line up, but the public sources do not disclose the contractual bridge between the two.
The announcement supplies the financing headline
UnternehmerTUM's press release says Kuro received €10 million under the leadership of UVC Partners, with Foundamental, Realyze Ventures and helloworld participating. The 30 September announcement describes Kuro's software for general contractors, its twelve existing customers and the six customers it says rank among the 20 largest contractors in the German-speaking region.
UVC Partners' own account repeats the amount and investor group. It says Kuro plans to extend its platform from estimating into procurement, accounting and compliance. NEON's legal-adviser note independently calls the transaction a €10 million Series Seed and confirms UVC Partners as the lead investor, with Foundamental, Realyze Ventures and helloworld participating.
Those sources establish the financing event. None discloses a valuation, subscription price, preference structure, board rights or the cash allocation among the four named funds. They also do not say whether every legal share position visible in the May list was subscribed in one closing.
The register turns four names into exact stakes
Kuro Technology GmbH is registered with the Amtsgericht Berlin (Charlottenburg) under HRB 267384 B. Its company impressum names Lea Scherer and Jonas Philipp Minkler as directors. OpenRegister's chronology records the company's conversion to a GmbH in November 2024, the €41,632 capital figure effective on 5 May 2026 and the shareholder-list publication on 8 May.
The 8 May shareholder list gives the latest selected legal snapshot. It records 41,632 €1 shares and marks the newly created blocks as arising from a capital increase. The largest positions are:
| Holder or group | Nominal shares | Share of €41,632 capital | What the list shows |
|---|---|---|---|
| ELIL Ventures UG | 12,500 | 30.0250% | Founder-linked vehicle position |
| L. Scherer Ventures UG | 12,500 | 30.0250% | Founder-linked vehicle position |
| UVC Fonds IV GmbH & Co. KG | 6,752 | 16.2183% | New block marked as capital increase |
| Foundamental Rebel Fund GmbH & Co. KG | 6,173 | 14.8275% | New block marked as capital increase |
| Realyze Ventures GmbH & Co. KG | 1,688 | 4.0546% | New block marked as capital increase |
| HelloWorld Venture Capital Fund I SCSp | 1,083 | 2.6014% | New block marked as capital increase |
| Other named holders, calculated residual | 936 | 2.2483% | Fourteen smaller vehicles or individuals, not one holder |
The four funds highlighted in the financing announcements hold 15,696 nominal shares together, or 37.7018% of the registered capital. The two founder-linked vehicles hold 25,000 shares, or 60.0519%. The remaining 936 shares are spread across smaller positions, including Schaal Technology Ventures, Center Ventures, Scout Fund VII and several small founder or investor vehicles.
The list therefore does more than repeat the investor names. It gives the market a dated legal footprint. UVC is not just described as the lead in a press release; UVC Fonds IV appears with 6,752 shares. Foundamental, Realyze and helloworld likewise appear through specific legal vehicles with specific nominal positions.
€41,632 is not the €10m cheque
The apparent mismatch between €41,632 and €10 million is not a contradiction. German limited liability company records state nominal share capital, while a venture round can price those shares at a substantial premium and can attach rights that do not appear in a simple share count.
The list records each share at a €1 nominal amount. That makes the legal arithmetic transparent, but it does not say that UVC paid €6,752, that Foundamental paid €6,173 or that the four investors paid €15,696 in total. Those are nominal values. The cash amount, if any, would also include the negotiated issue price above nominal value and could be accompanied by preference, voting or liquidation terms in other documents.
The timing is informative but not conclusive. The capital increase became effective on 5 May, and the list was placed in the register folder on 8 May. The €10 million announcement came on 30 September, almost five months later. The investor names match across the two evidence tracks, which makes the list a strong candidate for the legal footprint of the financing process. It does not prove that the May deed and the September announcement are the same contractual closing, or that no other instrument sat alongside the capital increase.
This is the same analytical separation that matters in SPREAD's founder secondary. There, a later shareholder list showed Salesforce receiving existing founder-vehicle shares while registered capital stayed unchanged. Kuro presents the opposite legal mechanism in the visible changes column: the main investor blocks were newly created through a capital increase. In both cases, the register answers the ownership question without disclosing the full cash economics.
Founders still hold most of the visible denominator
ELIL Ventures UG and L. Scherer Ventures UG each hold 12,500 shares. Together they account for 60.05% of Kuro's nominal share capital. The list itself does not say who ultimately controls either vehicle, and the company names alone are not proof of personal ownership. Kuro's impressum identifies Scherer and Minkler as directors, but director status is not the same as a beneficial-ownership filing.
The safe conclusion is therefore narrower than “the founders control Kuro.” The latest public list leaves two founder-linked vehicles with a majority of the ordinary nominal share denominator. Any voting pool, preferred class, veto right, board arrangement or shareholder agreement would have to be established from a different document.
The same point applies to the investor side. UVC's 16.2183% is the largest fund position in the list, followed by Foundamental at 14.8275%. Realyze and helloworld are smaller visible blocks. Their percentages are precise because the register prints them, not because the public sources disclose how much each fund invested. A fund can have a larger economic claim than its nominal percentage if the share terms include preferences, or a different influence profile if governance rights are negotiated separately.
Why this map matters to private-market readers
For founders, the map signals that Kuro has added a broad investor group while retaining a large founder-linked base. For competing investors, it identifies the legal entities that now sit in the shareholder structure. For acquirers and lenders, it provides a starting denominator for diligence, but not a substitute for the financing documents.
That is why the €10 million headline and the €41,632 capital figure should be read together rather than compared as if one were an error. The headline describes funding capacity for a Berlin construction-AI company. The register records the legal share issuance that underpins part of the ownership map. The premium, preference and control layers remain outside the public snapshot.
Other recent private-market records show the same boundary in different forms. StandardX's preferred-capital stack separates a financing announcement from the rights attached to preferred shares. Reactive Technologies' debt and preference stack shows why debt and equity headlines can coexist without sharing the same risk or payout route. Kuro's register adds a clean percentage map, but it does not eliminate those instrument questions.
What the public record still cannot answer
| Publicly visible fact | Still undisclosed economic question |
|---|---|
| Four named funds hold 37.70% of nominal capital together | What cash did each fund subscribe, and at what price? |
| Founder-linked vehicles hold 60.05% of the listed shares | Do they have aligned voting rights or separate governance arrangements? |
| The changes column marks the main investor blocks as capital increases | Were all blocks part of one financing, or several commitments? |
| The round is described as €10m Series Seed by NEON | What valuation, preference, liquidation and board terms accompany it? |
| Capital became effective on 5 May and was announced publicly on 30 September | What happened between the legal issuance and the public closing statement? |
The missing information is commercially material. A €10 million round can be primary equity, secondary liquidity or a mixture of instruments. A legal share list can show the holders after issuance while leaving the price and priority structure private. Treating the nominal denominator as the financing amount would turn a useful register fact into a false valuation signal.
The next document should complete the map
The next decision-changing record is a later shareholder list or the full notarial deed dated 16 April 2026. A later list could show whether the ownership changed again around the public announcement. The deed or a filed financing document could disclose the issue price, the class of shares and whether the €10 million included instruments outside the registered capital increase.
Until that document appears, Kuro's financing can be stated with unusual precision and appropriate limits: the company announced €10 million led by UVC Partners; the May register lists UVC, Foundamental, Realyze and helloworld at 37.70% of nominal capital together; and two founder-linked vehicles retain 60.05% of the visible denominator. The public record maps the shares. It does not yet price them.
Continue reading
Related Research
Salesforce Raised Its SPREAD Stake Through A Founder Secondary
German shareholder lists show Salesforce acquired 612 existing SPREAD shares from two founder vehicles, raising its stake from 5.5% to 6.7% without new capital.
StandardX's £10m Seed Round Put Two Preferred Classes Ahead of Ordinary Shares
StandardX announced a £10m isotope seed. Companies House filings show £9.81m of priced allotments, senior preferred rights and a pre-round funding gap.
Reactive Technologies’ €19m EIB Debt Meets a £25m Preference Stack
Reactive Technologies’ €19m EIB debt is non-dilutive, but filings show £25m of Series D preference rights and an HSBC charge over IP and assets.
DeepSlate's €7.7m seed left founders at 55.76% in the latest list
DeepSlate's €7.7m seed put 42CAP at 16.94%; the latest register list shows Alstin at 11.27% after 384 founder shares moved, leaving founders at 55.76%.