
Atira's $17.5m raise leaves a 58.54% founder block visible
Atira's $17.5m funding headline maps to 16.92% across three Accel funds, while founder vehicles retain 58.54% of the latest visible register today.
On this page
Conduct your own private market research
Add dossaro to Claude or ChatGPT and run source-backed register research from your own workspace.
 Add to Claude
 Add to ChatGPT
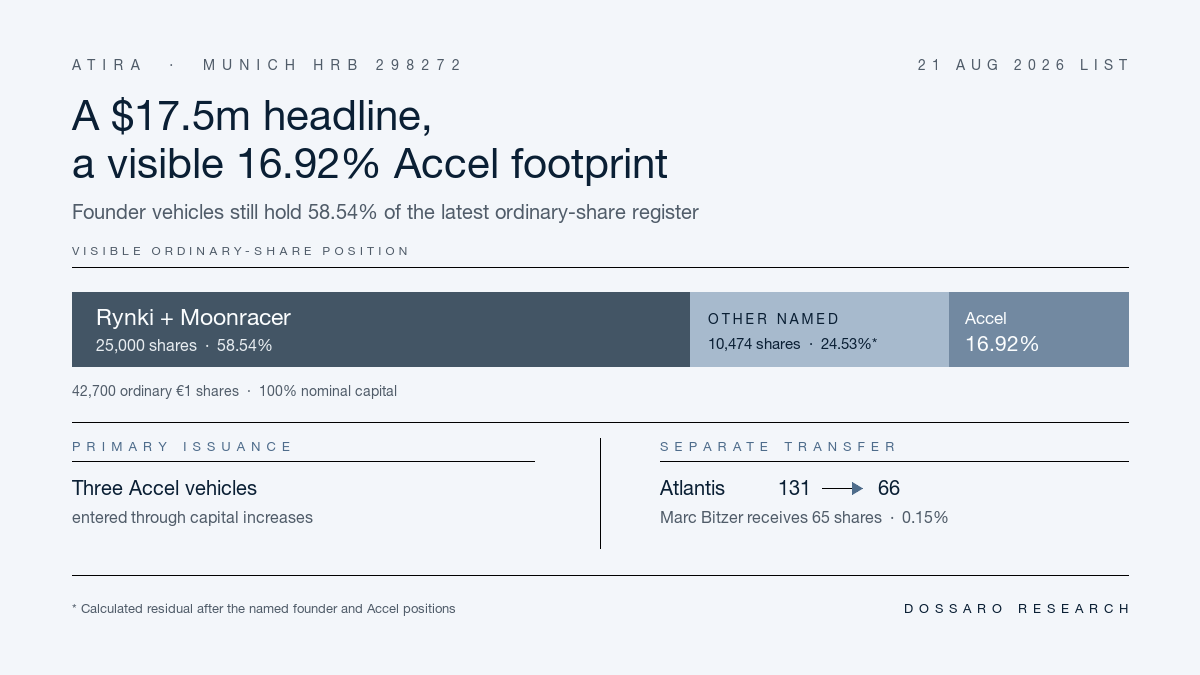
Atira's public financing headline is $15 million of seed capital led by Accel and $17.5 million raised in total. The latest shareholder list, taken into the Munich register folder on 21 August 2026, gives that headline a measurable ordinary-share footprint: three Accel London VIII vehicles hold 7,226 of Atira's 42,700 shares, or 16.92 percent. Rynki Ventures GmbH and Moonracer Ventures GmbH still hold 12,500 shares each, 58.54 percent together.
That is an ownership map, not a cheque allocation. The list records €1 nominal shares and the new Accel positions as capital increases, but it does not state the price paid above nominal value, the valuation or the exact share of the announced $15 million seed represented by those positions. The result is a sharper reading of the round: a public funding story now sits above a visible, still founder-heavy register structure.
The $17.5m headline sits above a visible equity footprint
Atira announced the financing on 3 September, thirteen days after the latest list was filed. The company's announcement says Accel led a $15 million seed and that the total reached $17.5 million after adding a previously unannounced $2.5 million pre-seed. It says the money will support engineering, commercial hiring and international expansion for its software that automates industrial sales processes.
UVC Partners' financing note and the UnternehmerTUM release repeat the split between the Accel-led seed and the earlier UVC, Fortino and Booom pre-seed. Fortune's independent report says Atira declined to disclose a valuation and names industrial investors including Marc Bitzer and Bastian Nominacher.
The public sources answer the event question. The register answers a different one: which legal holders were added to the ordinary-share denominator before the announcement. It names the Accel vehicles separately and records that their blocks came through an authorised-capital increase. That turns “Accel-led” from a single label into a set of three legal positions without pretending that the register contains the financing term sheet.
The latest list still starts with the founder vehicles
Atira GmbH is registered with the Munich local court under HRB 298272 and has its seat in Gräfelfing. The historical lists show how far the company moved before the latest round. On 11 December 2024, Rynki Ventures GmbH and Moonracer Ventures GmbH were the only holders, with €25,000 of capital split 50 percent each. The January 2025 list then showed each at 37.57 percent after UVC Fonds IV and other investors entered through a capital increase.
The 21 August 2026 list records €42,700 of capital. Rynki and Moonracer remain the two largest visible blocks at 29.27 percent each. The register does not describe those vehicles as a control agreement or a voting pool. It establishes their ordinary-share positions; any additional rights would have to come from other documents.
The key positions can be read directly from the share intervals and the percentages printed in the list:
| Register position | Shares in 21 August list | Visible share |
|---|---|---|
| Rynki Ventures GmbH | 12,500 | 29.27% |
| Moonracer Ventures GmbH | 12,500 | 29.27% |
| Accel London VIII L.P. | 6,496 | 15.21% |
| Accel London VIII Entrepreneurs L.P. | 198 | 0.46% |
| Accel London VIII Investors (2024) L.P. | 532 | 1.25% |
| Three Accel vehicles combined | 7,226 | 16.92% |
| Remaining named holders and residual shares, calculated | 10,474 | 24.53% |
The combined Accel position is the key calculation: 6,496 plus 198 plus 532 equals 7,226 shares, and 7,226 divided by 42,700 equals 16.9227 percent, rounded to 16.92 percent. Rynki and Moonracer together hold 25,000 shares, or 58.548 percent, rounded to 58.54 percent. The residual row is a calculated remainder, not a separate holder named by the register.
Three Accel vehicles mark primary issuance, not a disclosed cheque
The list's changes column identifies each Accel block as a capital increase through the issuance of new shares and the use of authorised capital. That is different from a transfer between existing holders. It supports a primary-issuance reading for the Accel limited partnership (LP) positions, while leaving the cash economics open.
Each share carries a €1 nominal value. The Accel blocks therefore add €7,226 to the nominal denominator, not $15 million of disclosed cash. A share premium, preferred rights, a separate instrument or a negotiated allocation could sit above that denominator. None is specified in the shareholder list or in the public financing announcements used here.
This is why the timing matters without proving a payment path. The 21 August list predates the 3 September announcement, and its notarial certification refers to changes under a 30 June 2026 deed. The chronology is consistent with a financing process already reflected in the register. It is not a receipt showing that the three Accel vehicles together paid a particular dollar amount.
The distinction is familiar in private-market underwriting. A financing announcement states how much a company says it raised. A shareholder list states who holds shares after one or more legal steps. The two records meet only when the issue price, instrument class and allocation are disclosed. Atira's public materials do not provide that bridge.
The tiny Atlantis transfer is a different event
The same August list separates a small secondary movement from the Accel issuance. Atlantis Ventures GmbH's block falls from 131 shares to 66, shown as 0.15 percent. Dr. Marc Bitzer receives 65 shares, also 0.15 percent, and the changes column marks the line as an “Anteilsabtretung”, or share transfer.
The transfer is visible because the list names both sides and the reason for change. It does not materially alter the concentration of the cap table. It does, however, prevent two different events from being folded into one financing story. The Accel positions are recorded as new shares; the Bitzer position is recorded as a transfer of existing shares.
That separation also gives the public investor list more precision. Atira's announcement names Bitzer among new industrial investors. The register shows the legal movement associated with his 65 shares, while still leaving the investment price and any rights attached to those shares unpublished.
What the founder-heavy map changes for investors
The latest list makes Accel the largest named institutional position, but it leaves the two founder vehicles as the largest visible block. That combination changes the question for a venture investor. The $17.5 million headline signals the scale of the company's fundraising narrative; the 16.92 percent ordinary-share position shows the measurable footprint of the named lead. Neither number, by itself, establishes voting control or the economic priority of any investor.
For a buyer or later-stage investor, the next diligence step is therefore specific: reconcile the dollar headline with the share issue, rights and any instruments outside the ordinary list. Xorlab's analysis of a Series A-plus capital programme makes the same legal-versus-financing distinction in a different setting. Atira's register gives the ownership denominator; it does not price the round.
The structure also keeps the founder outcome in view. Rynki and Moonracer moved from 50 percent each at formation to 29.27 percent each in the latest list as new capital entered. That is visible dilution, not a conclusion about the founders' economic return. Their combined ordinary-share block remains large enough to matter in any governance analysis, while the rights attached to those shares are not in the evidence used here.
The register cannot price the headline
The difference between €42,700 of registered capital and $17.5 million of announced funding is not an inconsistency. German limited companies can issue €1 nominal shares at a premium, and financing can include instruments or contractual rights that do not appear as a simple increase in nominal capital. The public record used for this article does not say which of those mechanisms, if any, made up the gap.
That boundary is commercially important because the headline and the register answer different underwriting questions. The announcement describes capital available for product and expansion. The list describes the legal holders after capital increases and one small transfer. Investors still need the issue price, instrument terms and any voting or preference arrangements to connect the two.
The public narrative is not contradicted by a founder-heavy ordinary-share list. It is incomplete on the capital mechanics. The strongest defensible conclusion is narrower: Atira has a visible 16.92 percent Accel footprint across three LP vehicles and a 58.54 percent block in Rynki and Moonracer, while the ordinary register does not disclose how those percentages map to the $15 million seed.
The next document should connect cash to rights
The next decision-changing evidence would be the full notarial capital-increase deed referenced in the August list, together with any filed articles or shareholder agreement that sets out voting, preference or transfer rights. A later shareholder list could also show whether the structure changes after the announced round.
Until those records are public, the useful headline for underwriting is not simply “Atira raised $17.5 million.” It is that three Accel LP vehicles now hold 16.92 percent of the visible ordinary shares, while Rynki and Moonracer hold 58.54 percent together and a separate 0.15 percent transfer moved from Atlantis to Marc Bitzer. The remaining question is concrete: how much cash bought those shares, and which rights sit above the percentages?
Continue reading
Related Research
ZuriQ's $25.5m Seed Created A 28.6% Preferred Block
ZuriQ's $25.5m seed closed legally in May, creating a 28.6% preferred block and adding a Quantonation-linked director before its July reveal.
xorlab's €5m Series A+ Follows A Staged Swiss Capital Programme
xorlab's €5m Series A+ followed a 43.4% 2021 and 20.0% 2026 issued-capital rise, while Swiss filings do not identify investors or dilution yet.
DORMA-Glas's Asset Deal Was Prepared Before The Rescue Headline
DG Glas's €25,000 successor vehicle and shareholder filings predated DORMA-Glas's rescue announcement, separating operating continuity from creditor recovery.
FRYTE’s €3.5m seed leaves founders at 52.74%
FRYTE’s €3.5m seed sits beside a 43.89% share issue: founders fell from 94% to 52.74%, while 4impact and Rethink hold 21.88%. The legal list does not price the round.